Two Years On, We Can See What Trump Has Done To The U.S. Economy
As we approach the two-year mark since Donald Trump’s second election victory, it’s a good time to do a little economic scorekeeping. Before getting into where the economy is and where it’s going, it’s worth a little reminder of where it was before the election.
This is important because Trump and the Republicans continuously spew utter nonsense about an economic disaster that only exists in their imagination. By literally every standard measure, the economy was doing extremely well just before the election. The unemployment rate was hovering near 4.0 percent and nominal wages were growing at roughly a 4.0 percent annual rate.
Inflation had slowed sharply, with the year-over-year rate at 2.6 percent in October of 2024. This translated into real wage growth of close to 1.5 percent. Inflation was expected to continue to slow, with most projections having inflation coming in very close to the Fed’s 2.0 percent target by the end of 2025.
There had been a massive surge in the number of people able to work from home as a result of the pandemic, with that figure still being close to 20% by the end of 2024. These people were saving hundreds of hours a year in commuting time and thousands of dollars annually in commuting-related costs. There also had been an unprecedented explosion in factory construction, with real spending in 2024 more than double the pre-pandemic level in 2019.
Growth for the year was 2.5 percent, and it was expected to be above 2.0 percent for the near future. This story was the basis for The Economist’s famous cover story about the U.S. economy: The Envy of the World.
Trump Takes Over: The Story Darkens
Virtually without exception, the data have gotten worse under Trump. Inflation has risen; nominal wage growth has slowed. Factory construction has plummeted. The trade deficit, which he views as a central measure of economic failings, has soared. Interest rates have risen, and the United States has fallen far behind the world in the green transition. China’s production of wind and solar energy exceeds our total production of energy. People have lost health insurance coverage, and costs are soaring for those who still have it.
The economy has become almost completely dependent on the AI bubble, as most other forms of investment are being crowded out. With real wages falling and job growth slowing to a trickle due to mass deportations, consumption growth is almost entirely dependent on stock price appreciation, which is in turn almost entirely driven by AI stocks.
This darkening picture began even before Trump took office. There was a huge surge in imports of durable goods like cars and TVs, starting right after the election. Consumers and businesses tried to buy ahead of Trump’s promised tariffs. Prices for durable goods, which had been falling through 2023 and 2024, began rising at the start of 2025. They rose further when Trump imposed the bulk of his tariffs in April. Instead of falling to 2.0 percent, inflation was 2.7 percent by the end of 2025, having hit 3.0 percent as a year-over-year rate in September.
Job growth fell sharply almost immediately after Trump took office, with the average monthly rate for his first year being just 27,000, down from an average of 103,000 for the last year of the Biden administration. Part of this slowing was due to the DOGE purge of federal government employees, but even pulling out the federal government, there was a slowing from 100,000 a month to 53,000. The main factors behind the slowing were the policy of mass deportation, which cut net immigration to near zero, and the tariffs, which both raised prices and led to enormous uncertainty.
The weakening of the labor market led to a sharp slowing in wage growth. While unemployment remained relatively low, workers became much less likely to switch jobs. Since job switching accounts for a disproportionate share of wage gains, the rate of nominal wage growth slowed sharply, from over 4.0 percent in 2024 to just 3.0 percent in the most recent data. With inflation accelerating to 3.5 percent, real wages are falling.
Growth Without Wage Growth
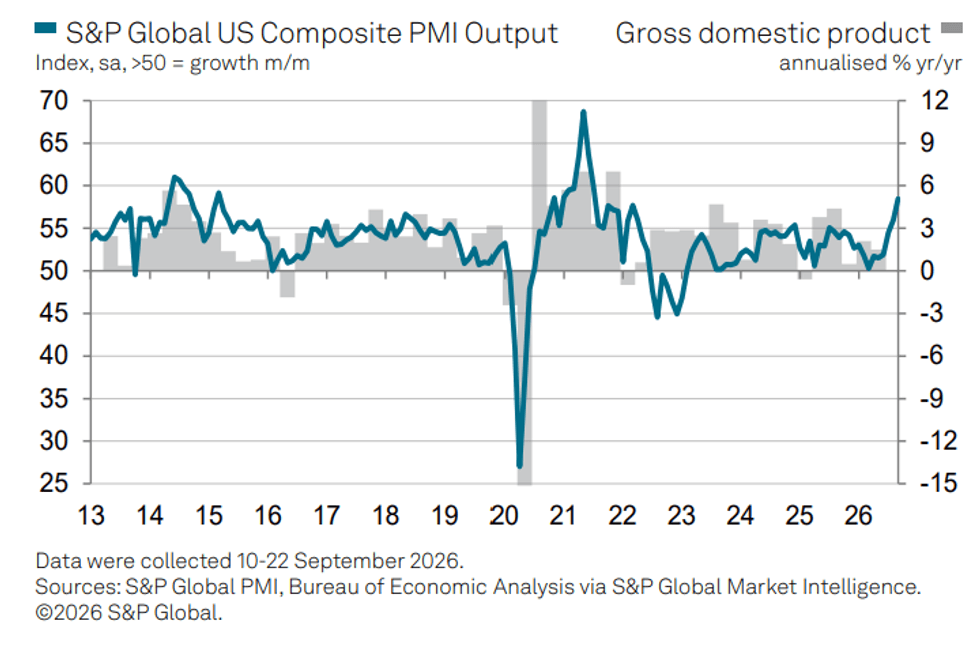
With job growth slowing to a trickle, roughly a 0.2 percent annual rate, and real wages falling, workers’ spending cannot drive consumption. While consumption is still growing at a healthy pace, it is clearly because of stock market gains. In the last three years, the market has risen by more than 80 percent, which translates into roughly $40 trillion in new stock wealth. The wealth effect on consumption is usually estimated as being close to three cents on a dollar. This means that the rise in stock wealth has added close to $1.2 trillion to annual consumption over the last three years, an amount equal to almost 4.0 percent of GDP.
This run-up was overwhelmingly an AI story. The value of AI-related companies has more than doubled over the last three years.
If AI has been driving consumption, its impact on investment has been even larger. Excluding data centers, investment in structures is down by almost 10 percent since the fourth quarter of 2024. Outside of information processing equipment, investment in equipment has been essentially flat under Trump. AI has also accounted for more than 80 percent of the investment in intellectual property products since 2024. In short, the story of investment growth under Trump is AI.
One of the ironies of the surge in spending on AI is that it has caused a sharp rise in the trade deficit. While there can be problems with a large trade deficit, such as the surge at the start of the century that cost millions of manufacturing jobs, the trade deficit had fallen back to roughly 3.0 percent of GDP when Trump took office, a level that can be easily sustained indefinitely.
The expectation of tariffs caused deficits to soar in the first quarter of 2025, but they then fell back to roughly their 2024 level after the tariffs were in effect. But they have been rising rapidly in recent months, passing $100 billion in August, due to a surge in computer chips and other AI-related items. This pace would put the trade deficit at over 4.0 percent of GDP.
Budget Deficits, Interest Rates, and Housing
At various points in his campaign, Trump promised that he was going to balance the budget or even pay off the debt. This isn’t happening. The deficit has increased under his watch, hitting $1,993 billion in fiscal 2026, up from $1775 billion in fiscal 2025. The biggest factors in this increase were a decline in corporate income taxes and higher interest payments on the debt. At more than 6.0% of GDP, the deficit is a record for a period when we are not in a war or recession.
It is worth mentioning that there have been cuts in spending that partially offset the tax cuts. While these are not large in terms of the total budget, they have had noticeable short-term effects and could have substantial long-term effects. On the short-term side, cuts to Medicaid and the ACA exchanges have led to an increase in the uninsured population. It rose by roughly 1 million from 2024 to 2025 and is virtually certain to rise considerably more in 2026 and beyond. Ending funding for the Africa AIDS program could lead to millions of preventable deaths in the years ahead.
The longer-term harm is likely to come from cuts to NIH funding and other federal research pools. In addition to the direct impact of the cuts, the arbitrary restrictions and politicization of grant awards, coupled with the harassment of leading research universities, have already sent many top researchers to other countries. As a result, they will likely be the primary beneficiaries of what otherwise would have been American innovations.
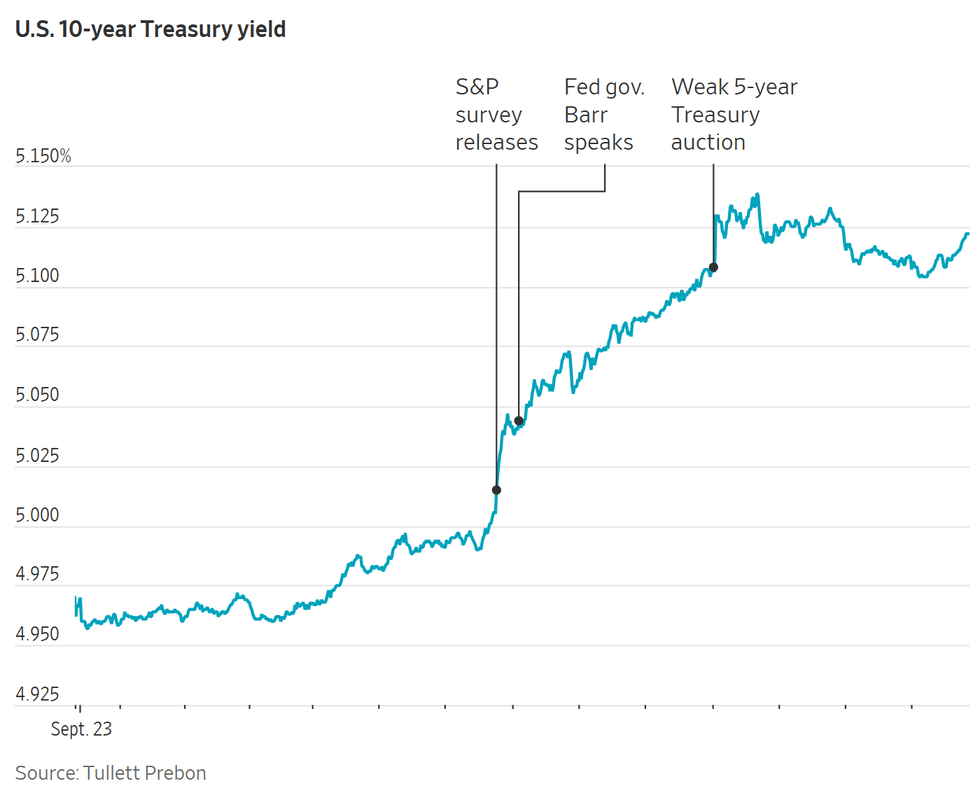
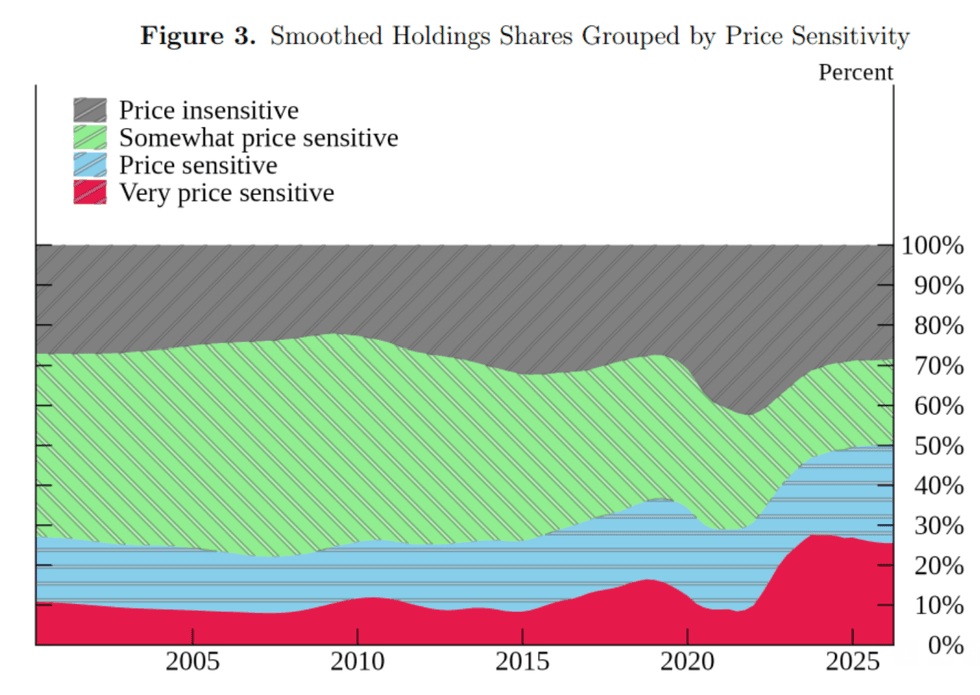
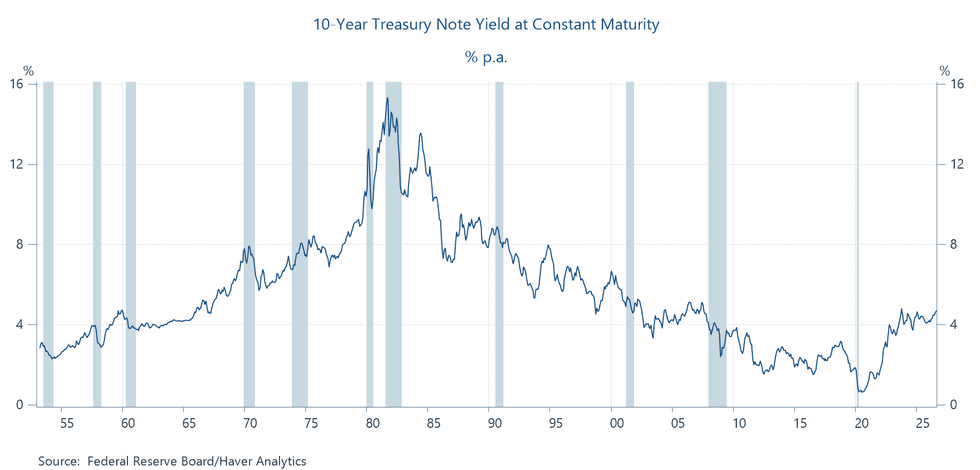
As noted, the higher deficit is partly due to higher interest rates, but the deficit does not seem to be the main cause of higher rates. Rather, the massive demand for capital to build data centers for AI is a much more important factor. In any case, long-term interest rates have risen sharply under Trump. The 10-year Treasury rate had been as low as 3.6 percent in September of 2024 and was heading downward. It turned around under Trump and now stands at almost 5.3 percent.
The high interest rates have weakened housing construction. It has averaged 1.35 million units a year. We probably need a construction rate of around 1.6-1.7 million units to have a noticeable impact in bringing house prices down. The rate was well over 1.7 million in 2022, before the Fed started raising rates.
The Future of the Economy is the Future of the AI Bubble
The Trump economy really does boil down to AI. If we believe the hype, we are about to see an incredible surge in productivity that will make us ridiculously wealthy. To date, there is no evidence to support this view. Productivity growth has been at best on its trend pace the last couple of years.
The stock market is priced as though we will see this massive AI payoff. As noted earlier, we saw a massive run-up in stock prices. Part of this is due to a rise in after-tax profits, as there has been a shift from wages to profits and a reduction in corporate income taxes. But the more important factor has been an increase in price-to-earnings ratios, with the market-wide average near the record levels hit in the tech bubble.
If we don’t see the massive gains in productivity promised by the AI enthusiasts, then we will almost certainly see a collapse in the stock market, with a serious recession almost guaranteed. On the other hand, if AI does have the promised payoff, all will be good, as long as the AI barons don’t steal all the money.
Dean Baker is a senior economist at the Center for Economic and Policy Research and the author of the 2016 book Rigged: How Globalization and the Rules of the Modern Economy Were Structured to Make the Rich Richer. Please consider subscribing to his Substack, from which this is reprinted with permission.
 Source: Tullett Prebon
 Source: Board of Governors of the Federal Reserve System International Finance Discussion Papers Number 1447
 Source: Federal Reserve Board/Haver Analytics