@DeanBaker13
elon musk

Billionaires Are Too Awful To Control Our News Outlets And Social Media

Our billionaires seem to be in a competition for most awful human being. We have Larry Ellison, along with son, taking over CBS and immediately destroying its prized news show, 60 Minutes. They appointed Bari Weiss, a right-wing apparatchik, to oversee CBS’s entire news operation. She has immediately sought to make the news more Trump-friendly. This has led to many reporters being fired and threats to others to make their reporting toe the Trump line or risk being fired. Many of the network’s longest-serving reporters just quit.

The fun doesn’t stop here. The Ellison clique is also getting control of CNN through Paramount’s takeover of Warner Bros. Presumably we can look forward to more Trump-friendly reporting there also.

To be clear, neither of these networks was a paragon of objective reporting before the Ellison family takeover. Both networks regularly marginalized and belittled progressives in the U.S. and around the world. But they did at least have an ostensible commitment to objectivity, unlike, say, Fox News.

Then we have Mark Zuckerberg, who seems to view the huge Meta social media platforms as important mechanisms for pushing his political agenda. Last Saturday, the Instagram site for the No Kings march went down for four hours, exactly when it was being most widely used. Meta claimed there was no political motive; it was just incompetence.

We might be more inclined to accept the incompetence story if there wasn’t a comparable picture in Brazil in the lead-up to its presidential election. Lula, the incumbent president, is locked in a tight race with Flavio Bolsanaro, a right-winger who is openly allied with Donald Trump. It seems that the sites of supporters of Lula and his supporters have repeatedly run into the same sort of technical difficulties with Meta.

Then we go to everyone’s favorite evil billionaire, Elon Musk. Musk bought Twitter with the explicit intention of using it as a vehicle to support his politics. He not only opened the gates to all sorts of racist, sexist, and harassing material; he has throttled the accounts of many progressives so that their comments are less widely viewed.

Musk also has teamed up with Ellison, who was given a controlling stake in TikTok, after Donald Trump wrestled it away from its Chinese owner. TikTok decided to suspend the account for the documentary Musk, just before its initial release. Musk apparently gave the film a bad review, which was enough to get it banned from TikTok for at least a period of time. Musk is also contributing hundreds of millions of dollars to get some of the most awful people on the planet elected as governors or senators.

This crew of centibillionaires sees the purpose of government to make themselves ever richer, and are prepared to use their money to ensure that it does. Their use of campaign contributions for this purpose is widely recognized, but that is only part of the story.

Their control of major media outlets is at least as important. If a television or radio ad can affect people’s votes, then surely what people hear between the ads also can affect their votes.

Allowing the rich to dominate the media and social media to the extent they do is at least as much an offense to democracy as their hundred-million-dollar campaign contributions. It is essential to weaken their control.

One good place to start would be reforming Section 230 of the Communications Decency Act, which exempts the huge social media platforms from liability for third-party content. This gives social media platforms an advantage over broadcast and print outlets, which are liable for harms (defamation or fraud) caused by third-party content. Fox News famously paid out $787 million for spreading third-party lies about the 2020 election. Section 230 can be amended in a way that levels the playing field and favors smaller non-profit or subscription-supported platforms.

The other route is to increase support for alternative media. There has been serious progress in this area. The Local News Act was recently signed into law by California Governor Gavin Newsom. This measure gives a subsidy of up to $20,000 per reporter for news outlets to cover local news. Several other states are considering similar measures.

It’s a long way from measures giving modest subsidies for local news to the multibillion-dollar media outlets and social media platforms that dominate what people see and hear. But these are an important foot in the door. If these measures succeed and are popular, they can spread to other states and possibly be implemented nationally.

In any case, if we are serious about limiting the ability of the billionaires to buy democracy, we have to go beyond worrying about campaign contributions. If they control everything we see and hear in the media and on social media, they won’t have to spend a penny on elections to keep their candidates in power. Those concerned about democracy need to recognize this fact.
Trump's 'Beef Tax' Promotes Health And Environmental Progress (By Accident)

Trump's 'Beef Tax' Promotes Health And Environmental Progress (By Accident)

As has been noted, Donald Trump’s war on Iran has already done more to promote clean energy than any Democratic president ever could have imagined. The spike in oil prices and the enormous uncertainty created by Trump and Netanyahu’s attack have spurred households and businesses around the world to put the shift to electic vehicles (EVs) and clean energy on hyperdrive. China’s exports of EVs are more than double their 2025 pace. Similarly, sales of solar panels and wind turbines are going through the roof. Trump may be blocking the transition in the United States, but the rest of the world is going full speed ahead.

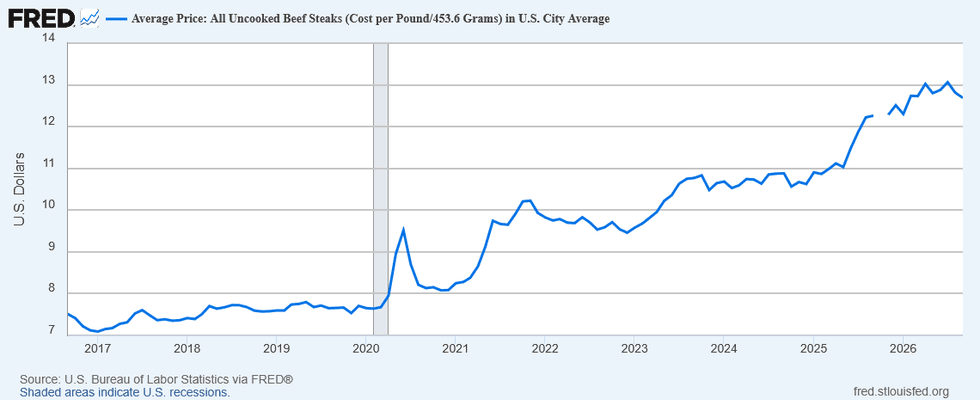
In a similar vein, it seems Trump is also trying to move American consumers away from their beef-eating habits. Beef prices keep hitting record levels. There are many factors at play here. Part of the story is an increased price of feed for cattle. Drought, due to the global warming Trump claims to not believe in, has limited harvests in many areas. Tariffs have also had an impact. Disease has been a factor as well.

Presumably Trump did not intend to price millions out of the market for beef, but that is what he has done. Beef consumption in the second quarter of this year was down more than 15.0% from its level in the 4th quarter of 2024. This sort of drop in beef consumption has no precedent in recent history.

In many ways, this is a good thing. Beef is an enormously inefficient way to feed people. It wastes a huge amount of energy, water, and land. It is also unhealthy for people to eat large amounts of beef, despite what our measles promoting Secretary of Health and Human Services tells us. And some folks might think it is needless cruelty to slaughter cows to put their remains on our plates. I can say that because I’m not running for the Senate in Texas.

Anyhow, it’s likely that Trump has no desire to discourage beef consumption, just like he probably is not deliberately promoting the green transition in the rest of the world, but that is what he’s doing with his policies. Trump may actually manage to accomplish some good in the world in spite of himself.

Dean Baker is a senior economist at the Center for Economic and Policy Research and the author of the 2016 book Rigged: How Globalization and the Rules of the Modern Economy Were Structured to Make the Rich Richer. Please consider subscribing to his Substack, from which this is reprinted with permission.

Donald Trump tariffs

Trumpflation Is Here! (A Truly Legitimate Naming Opportunity)

Donald Trump loves to put his name on things, and when it comes to the recent burst of inflation, it’s totally deserved. Trump and Republican politicians are doing their best to try to make a simple story complicated. But there is no doubt that Trump is the lead and almost sole author of the inflation we are now seeing.

Just to quickly clear away the stupid, we did have a large burst of inflation under Biden, just like the rest of the world. We were hit with a worldwide pandemic in Trump’s first term, which he apparently can’t remember. The pandemic led to a massive fall in output in 2020, while Trump was president.

When Biden took office in January of 2021, we were still down more than 10 million jobs from the pre-pandemic level. Biden’s recovery package quickly got back the lost jobs and got the unemployment rate down to 4.0 percent by the end of the year, far faster than anyone expected.

The reopening of the economy from the pandemic recession led to a burst of inflation in the United States, as it did in Germany, France, and everywhere else. Suddenly people were buying lots of things, and it took a while for businesses to ramp up production.

If Biden had cared less about getting people back to work, the recovery package could have been smaller, and the peak inflation rate might have been one or two percentage points lower. But the important part of the story is that inflation quickly came down.

Year-over-year inflation peaked at 9.0 percent in June of 2022. A year later, it was down to 3.1 percent. It was down to 2.6 percent by the election in November of 2024. Inflation was generally expected to continue to fall and to be at or near the Fed’s 2.0 percent target by the end of 2025.

But then Trump turned everything around. Inflation began to rise even before he took office, as households and businesses stocked up on imported goods in anticipation of Trump tariffs. Durable goods prices, which had been falling since early 2023, stopped falling and began to rise. The Consumer Price Index also stopped falling and started to rise. Year-over-year inflation hit 3.0 percent in September 2025 but then slowed to 2.7 percent by the end of the year.

It likely would have continued to slow through 2026. After all, Trump’s tariffs were primarily a one-time event. If he didn’t keep imposing new ones (a big “if”), it was reasonable to think that inflation would settle back down to its pre-tariff pace.

But we never got to test that story. Trump decided to go to war with Iran at the end of February. As we all know, the stated rationale was crazy. Iran was not close to having nuclear weapons, and Trump himself had boasted about destroying the country’s nuclear program in a bombing strike the prior summer.

Logic doesn’t mean much to Donald Trump. He and Israel’s Prime Minister Benjamin Netanyahu wanted to attack Iran, and whatever story they came up with was secondary.

Anyhow, regardless of their motives, they apparently did not expect that the Iranian government would both survive and retaliate by blocking oil from going through the Strait of Hormuz. This sent oil prices soaring, which is the biggest element in the current burst of inflation. However, since oil is not just gas for our cars, but diesel, which is needed for transporting just about everything, the price hikes are spreading throughout the economy. Also, since much of the world’s fertilizer production takes place in the Gulf countries, fertilizer prices are also soaring. This had some effect on crops already but will be a much bigger deal next year.

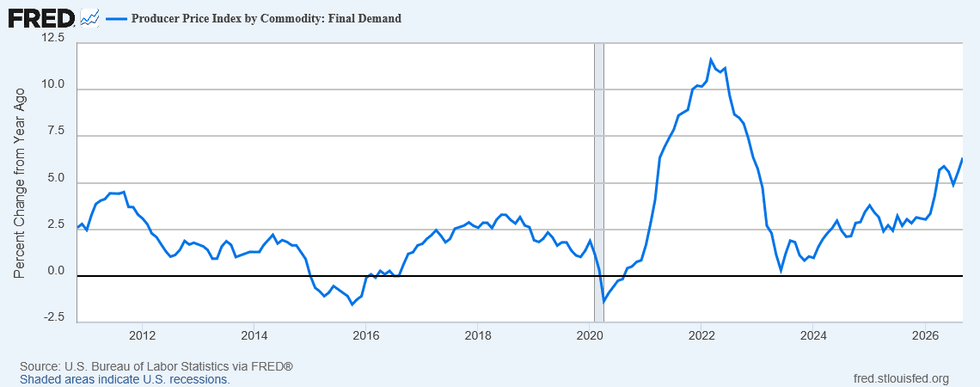
The broad impact of Trump’s war on inflation can be clearly seen in the Producer Price Index. The latest year-over-year figure was 6.3 percent for September. Since this is inflation at the wholesale level, it will be showing up at the consumer level in the next few months. To be clear, the impact is not one-to-one, so this doesn’t mean that consumer inflation will be rising to 6.3 percent, but it means that the direction of change in future months will likely be higher, not lower.

This is very far from a number consistent with the Fed’s two percent target. And this is all Trump’s doing. One important difference from the 1970s inflation is that, unlike the 1970s, wages are not rising in step with inflation. The pace of wage growth slowed from 4.0% in 2023 and 2024 to 3.0 percent in the most recent data. This means that workers are falling further behind as prices accelerate. The higher prices are going to profits, not covering higher labor costs. That might be good news for Trump’s billionaire donors, but not for the rest of us.

Dean Baker is a senior economist at the Center for Economic and Policy Research and the author of the 2016 book Rigged: How Globalization and the Rules of the Modern Economy Were Structured to Make the Rich Richer. Please consider subscribing to his Substack, from which this is reprinted with permission.

Donald Trump

Two Years On, We Can See What Trump Has Done To The U.S. Economy

As we approach the two-year mark since Donald Trump’s second election victory, it’s a good time to do a little economic scorekeeping. Before getting into where the economy is and where it’s going, it’s worth a little reminder of where it was before the election.

This is important because Trump and the Republicans continuously spew utter nonsense about an economic disaster that only exists in their imagination. By literally every standard measure, the economy was doing extremely well just before the election. The unemployment rate was hovering near 4.0 percent and nominal wages were growing at roughly a 4.0 percent annual rate.

Inflation had slowed sharply, with the year-over-year rate at 2.6 percent in October of 2024. This translated into real wage growth of close to 1.5 percent. Inflation was expected to continue to slow, with most projections having inflation coming in very close to the Fed’s 2.0 percent target by the end of 2025.

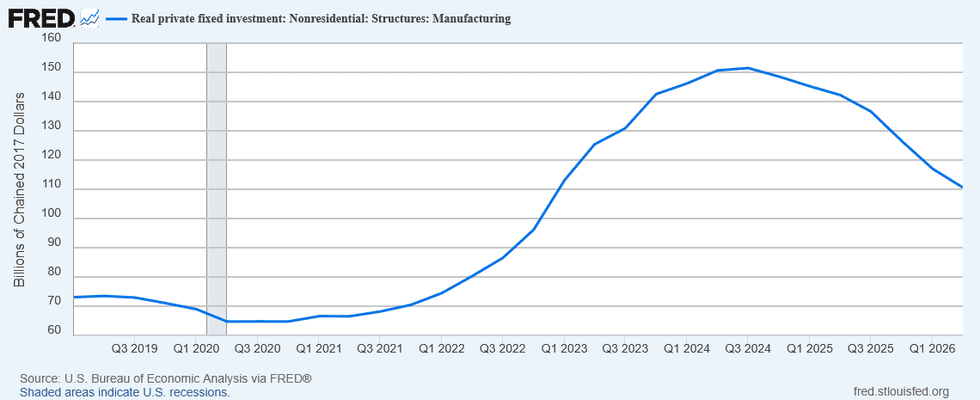
There had been a massive surge in the number of people able to work from home as a result of the pandemic, with that figure still being close to 20% by the end of 2024. These people were saving hundreds of hours a year in commuting time and thousands of dollars annually in commuting-related costs. There also had been an unprecedented explosion in factory construction, with real spending in 2024 more than double the pre-pandemic level in 2019.

Growth for the year was 2.5 percent, and it was expected to be above 2.0 percent for the near future. This story was the basis for The Economist’s famous cover story about the U.S. economy: The Envy of the World.

Trump Takes Over: The Story Darkens

Virtually without exception, the data have gotten worse under Trump. Inflation has risen; nominal wage growth has slowed. Factory construction has plummeted. The trade deficit, which he views as a central measure of economic failings, has soared. Interest rates have risen, and the United States has fallen far behind the world in the green transition. China’s production of wind and solar energy exceeds our total production of energy. People have lost health insurance coverage, and costs are soaring for those who still have it.

The economy has become almost completely dependent on the AI bubble, as most other forms of investment are being crowded out. With real wages falling and job growth slowing to a trickle due to mass deportations, consumption growth is almost entirely dependent on stock price appreciation, which is in turn almost entirely driven by AI stocks.

This darkening picture began even before Trump took office. There was a huge surge in imports of durable goods like cars and TVs, starting right after the election. Consumers and businesses tried to buy ahead of Trump’s promised tariffs. Prices for durable goods, which had been falling through 2023 and 2024, began rising at the start of 2025. They rose further when Trump imposed the bulk of his tariffs in April. Instead of falling to 2.0 percent, inflation was 2.7 percent by the end of 2025, having hit 3.0 percent as a year-over-year rate in September.

Job growth fell sharply almost immediately after Trump took office, with the average monthly rate for his first year being just 27,000, down from an average of 103,000 for the last year of the Biden administration. Part of this slowing was due to the DOGE purge of federal government employees, but even pulling out the federal government, there was a slowing from 100,000 a month to 53,000. The main factors behind the slowing were the policy of mass deportation, which cut net immigration to near zero, and the tariffs, which both raised prices and led to enormous uncertainty.

The weakening of the labor market led to a sharp slowing in wage growth. While unemployment remained relatively low, workers became much less likely to switch jobs. Since job switching accounts for a disproportionate share of wage gains, the rate of nominal wage growth slowed sharply, from over 4.0 percent in 2024 to just 3.0 percent in the most recent data. With inflation accelerating to 3.5 percent, real wages are falling.

Growth Without Wage Growth

With job growth slowing to a trickle, roughly a 0.2 percent annual rate, and real wages falling, workers’ spending cannot drive consumption. While consumption is still growing at a healthy pace, it is clearly because of stock market gains. In the last three years, the market has risen by more than 80 percent, which translates into roughly $40 trillion in new stock wealth. The wealth effect on consumption is usually estimated as being close to three cents on a dollar. This means that the rise in stock wealth has added close to $1.2 trillion to annual consumption over the last three years, an amount equal to almost 4.0 percent of GDP.

This run-up was overwhelmingly an AI story. The value of AI-related companies has more than doubled over the last three years.

If AI has been driving consumption, its impact on investment has been even larger. Excluding data centers, investment in structures is down by almost 10 percent since the fourth quarter of 2024. Outside of information processing equipment, investment in equipment has been essentially flat under Trump. AI has also accounted for more than 80 percent of the investment in intellectual property products since 2024. In short, the story of investment growth under Trump is AI.

One of the ironies of the surge in spending on AI is that it has caused a sharp rise in the trade deficit. While there can be problems with a large trade deficit, such as the surge at the start of the century that cost millions of manufacturing jobs, the trade deficit had fallen back to roughly 3.0 percent of GDP when Trump took office, a level that can be easily sustained indefinitely.

The expectation of tariffs caused deficits to soar in the first quarter of 2025, but they then fell back to roughly their 2024 level after the tariffs were in effect. But they have been rising rapidly in recent months, passing $100 billion in August, due to a surge in computer chips and other AI-related items. This pace would put the trade deficit at over 4.0 percent of GDP.

Budget Deficits, Interest Rates, and Housing

At various points in his campaign, Trump promised that he was going to balance the budget or even pay off the debt. This isn’t happening. The deficit has increased under his watch, hitting $1,993 billion in fiscal 2026, up from $1775 billion in fiscal 2025. The biggest factors in this increase were a decline in corporate income taxes and higher interest payments on the debt. At more than 6.0% of GDP, the deficit is a record for a period when we are not in a war or recession.

It is worth mentioning that there have been cuts in spending that partially offset the tax cuts. While these are not large in terms of the total budget, they have had noticeable short-term effects and could have substantial long-term effects. On the short-term side, cuts to Medicaid and the ACA exchanges have led to an increase in the uninsured population. It rose by roughly 1 million from 2024 to 2025 and is virtually certain to rise considerably more in 2026 and beyond. Ending funding for the Africa AIDS program could lead to millions of preventable deaths in the years ahead.

The longer-term harm is likely to come from cuts to NIH funding and other federal research pools. In addition to the direct impact of the cuts, the arbitrary restrictions and politicization of grant awards, coupled with the harassment of leading research universities, have already sent many top researchers to other countries. As a result, they will likely be the primary beneficiaries of what otherwise would have been American innovations.

As noted, the higher deficit is partly due to higher interest rates, but the deficit does not seem to be the main cause of higher rates. Rather, the massive demand for capital to build data centers for AI is a much more important factor. In any case, long-term interest rates have risen sharply under Trump. The 10-year Treasury rate had been as low as 3.6 percent in September of 2024 and was heading downward. It turned around under Trump and now stands at almost 5.3 percent.

The high interest rates have weakened housing construction. It has averaged 1.35 million units a year. We probably need a construction rate of around 1.6-1.7 million units to have a noticeable impact in bringing house prices down. The rate was well over 1.7 million in 2022, before the Fed started raising rates.

The Future of the Economy is the Future of the AI Bubble

The Trump economy really does boil down to AI. If we believe the hype, we are about to see an incredible surge in productivity that will make us ridiculously wealthy. To date, there is no evidence to support this view. Productivity growth has been at best on its trend pace the last couple of years.

The stock market is priced as though we will see this massive AI payoff. As noted earlier, we saw a massive run-up in stock prices. Part of this is due to a rise in after-tax profits, as there has been a shift from wages to profits and a reduction in corporate income taxes. But the more important factor has been an increase in price-to-earnings ratios, with the market-wide average near the record levels hit in the tech bubble.

If we don’t see the massive gains in productivity promised by the AI enthusiasts, then we will almost certainly see a collapse in the stock market, with a serious recession almost guaranteed. On the other hand, if AI does have the promised payoff, all will be good, as long as the AI barons don’t steal all the money.

Dean Baker is a senior economist at the Center for Economic and Policy Research and the author of the 2016 book Rigged: How Globalization and the Rules of the Modern Economy Were Structured to Make the Rich Richer. Please consider subscribing to his Substack, from which this is reprinted with permission.


Larry Ellison

AI Bubble Near Bursting? When The Financing Gets Crazy, The End May Be In Sight

As the collapse of the housing bubble approached the financing got ever crazier. In 2005, interest-only loans accounted for 23% of all mortgages, according to the Mortgage Bankers Association. An interest-only loan may not sound like a good way for people to accumulate equity, but whatever. It gets better.

Subprime loans got all the attention, but they may not have been the biggest tell that things in the mortgage market were out of whack. The category of mortgages known as Alt-A rose to 11 percent of the mortgages issued in 2005. Alt-A are mortgages given to people who ostensibly could qualify for prime mortgages but are unable to provide complete documentation. Typically, Alt-A accounts for two to three percent of mortgages.

The standard story is that they mostly go to small business owners. The generous interpretation is that they can’t fully document the income needed for a prime mortgage because their income fluctuates. The less generous interpretation is that they lie on their taxes so they can’t produce tax returns showing the income they claim.

Regardless of the interpretation, the number of people who fell into this category exploded in the housing bubble years. We can either believe that we had a lot more people with erratic income streams, or we had a lot more people lying on their mortgages. The latter seems more plausible.

The mortgage issuers didn’t care because they knew they could sell pretty much any mortgage they issued to the investment banks. The investment banks didn’t care because they could package the mortgages into mortgage-backed securities (MBS). They could count on investment-grade ratings from the rating agencies, since the banks were paying them for the ratings. Then the investment banks could sell their MBS anywhere in the world.

Anyhow, the explosion of interest-only and Alt-A mortgages presaged the beginning of the end, but it was still more than two years out before the final death march. This should be a warning for all of us hoping for a quick return to sanity, but we keep seeing more crazy in AI financing these days.

Last week Amazon revealed plans to sell off $8 billion in chips to a newly created special purpose vehicle (SPV). Amazon will then lease back the chips from the SPV. This one should raise all sorts of red flags.

This sale/leaseback agreement is essentially a loan to Amazon. They book the sale as current revenue and profit, but then the leasing fees are effectively interest that Amazon is paying to the investors that bought stakes in the SPV. The advantage that this offers Amazon is that the leasing obligations don’t appear as straight debt on its books. In principle, most leasing obligations should count as debt, but Amazon’s accountants may be trying to find a way to avoid this.

Amazon made $135 billion in the year ending on July 1. It is one of the most profitable companies in the world. But it apparently needs to find ways to hide debt on its books. And just to be clear, it costs money to set up this sort of SPV. Everyone involved is getting very nice Wall Street salaries. But Amazon felt this maneuver was better for its finances than just issuing normal bonds.

Oracle also got into innovative leasing in a big way last week, signing a deal with the Chinese tech giant Tencent that leases it $7 billion worth of computing power, with 30 percent supposedly being paid upfront. There are several interesting aspects to this story.

First, the computing power could be coming from top-end Nvidia processors. The Trump administration prohibits the sale of these processors to China, ostensibly to inhibit its ability to develop AI. However, if Chinese companies can simply buy the computing power from these chips from U.S. companies, it would seem to undermine the purpose of the sales ban. But Larry Ellison, the former CEO of Oracle and still head honcho, is a big contributor to Donald Trump, so I guess all is good.

This also raises the question of whether the company has more computing power than it has demand. At a time when Oracle and the other hyperscalers are investing trillions to build data centers, that would be a troubling development for them.

The other question is whether this is a sign of Oracle’s increasingly desperate need for cash. Two weeks ago, Oracle issued a force majeure notice to try to get out of some of its payments on a massive data center it is constructing in New Mexico. It’s not clear that Oracle will have much of a case (such notices usually are issued in response to unforeseeable events like weather disasters or wars), but it does indicate some desperation on its part.

And the desperation is showing up in financial markets. Oracle’s bonds now carry yields well over 8.0 percent, in other words, junk bond territory.

The story with Meta, which recently blew $80 billion on its Metaverse, also doesn’t look very good. It too has massive expansion plans with limited commitments from real buyers.

And it looks like those real buyers could be in short supply. Instead of soaring exponentially, demand for AI from Anthropic seems to be leveling off. Demand for AI from OpenAI looks to be edging downward.

The big money folks weren’t very good in seeing around the corner in the tech bubble, nor in the housing bubble. But they all are singing “this time is different.”

Dean Baker is a senior economist at the Center for Economic and Policy Research and the author of the 2016 book Rigged: How Globalization and the Rules of the Modern Economy Were Structured to Make the Rich Richer. Please consider subscribing to his Substack, from which this is reprinted with permission.

Soaring Trade Deficit In August Suggests Trump Tariffs Are Failing

Soaring Trade Deficit In August Suggests Trump Tariffs Are Failing

It’s been almost a year and a half since “Liberation Day,” the day that Trump announced his “reciprocal” tariffs, slapping tariffs on imports from our trading partners to punish them for selling us stuff. Ostensibly, the goal of the tariffs was to eliminate, or at least reduce, our trade deficit.

Trump seems to believe that we are being ripped off if we buy more goods from a country than we sell to them. There can be problems caused by a large trade deficit, especially one that is rapidly growing, as was the case in the first decade of this century. But it doesn’t make sense to claim a country is ripping us off by selling us stuff.

Anyhow, whatever problems we have with trade are poorly addressed by the sort of blanket tariffs imposed by Trump. We may want tariffs to promote the development of certain industries, like solar panels or EVs, or to ensure a stable supply of essential products, like steel and rare earth minerals, but such efforts have little to do with Trump’s tariffs.

He said that he wanted to end the ripoff, which he defined as our trade deficit. It hasn’t worked out that way.

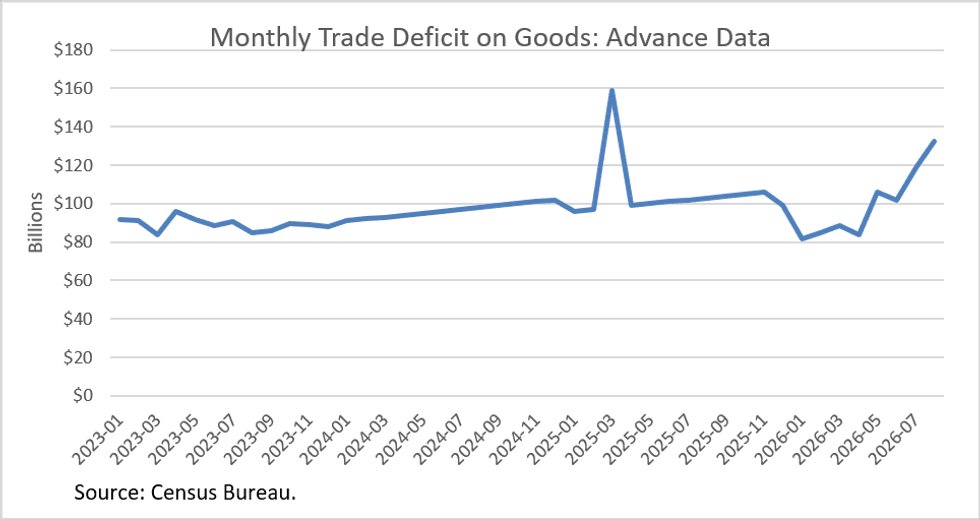
The monthly deficit had been around $90 billion through 2023. (Note that these are advance numbers based on incomplete data. They are generally higher than the final data the Census Bureau releases later.) It rose gradually in 2024, as the growth of the U.S. economy outpaced the growth of our trading partners. This caused U.S. imports to rise more than our exports to other countries. By the election, the trade deficit was up to $110 billion. It then began to rise more rapidly as consumers and businesses stocked up on imported goods in anticipation of Trump’s tariffs. The deficit hit an all-time record of $158.7 billion in March of 2025.

The deficit then fell both due to the impact of the tariffs and also because of the advance purchases in anticipation of the tariffs. By December, the deficit had risen back to $100 billion a month, roughly the same as the pre-election level.

The deficits have increased sharply again in 2026, driven in large part by a surge in semiconductor chips due to the AI boom. The August level of $132.6 billion is the second-highest deficit on record, topped only by last year’s March deficit.

It is worth mentioning that the U.S. runs a substantial surplus on services, collecting around $30 billion more each month on items like patent and copyright fees, insurance, and financial services than what we pay to foreigners. I’m not sure if this means we’re ripping them off, but that is part of the larger score on the trade balance.

Dean Baker is a senior economist at the Center for Economic and Policy Research and the author of the 2016 book Rigged: How Globalization and the Rules of the Modern Economy Were Structured to Make the Rich Richer. Please consider subscribing to his Substack, from which this is reprinted with permission.

Why Markets Will Crash If Trump Tries To Steal The Midterm Election

Why Markets Will Crash If Trump Tries To Steal The Midterm Election

All the political experts are telling us that the Republicans face a shellacking in November. The Democrats seem virtually certain to win the House and are increasingly likely to take the Senate. If that happens, it will put an effective end to the Trump administration.

Donald Trump clearly hates losing and has no respect for democracy. He tried to steal the last election he lost in 2020. For that reason, we have good reason to expect he will try to steal this one.

However, a major restraining factor is the likelihood that the stock market will crash. Trump’s billionaire buddies care far more about their money than about him. If letting Trump continue to play king is going to cost them a large share of their fortunes, they will use their considerable power to insist that the election results be respected.

To be clear, I’m not under any illusion that these people respect democracy. Many of them, like Elon Musk, openly express their contempt for it. But overturning a democratic election is the sort of lawlessness that is likely to send investors fleeing and markets tumbling.

We all know that Trump has already taken huge strides to move the country away from a law-governed system. He regularly sells pardons to people convicted of everything from fraud and tax evasion to drug dealing and child sex trafficking. A contribution to Trump’s campaign funds can win tariff relief or favorable regulatory rulings. And he has turned the White House into a sales office for Trump crypto and all sorts of other Trump products.

These practices have already undermined the country’s status as a safe place to do business. In Donald Trump’s America, a business can be hit by a shakedown attempt at almost any time for any reason. This is undoubtedly part of the story in the sharp rise in interest rates since Trump took office.

But stealing an election is a qualitative leap into Zimbabwe-land. If an election can be stolen in broad daylight, Trump can do anything, and no investment in the United States is safe.

And to be clear, there is zero doubt that we would be talking about stealing an election. All of Trump’s claims of fraud are batshit crazy, as everyone who has tried to examine them has determined, and every court that heard the cases has ruled.

In fact, it is surprising how little fraud along Trumpian lines exists. The Department of Homeland Security flagged 16,000 cases in Nevada of potential non-citizens who were registered to vote. It whittled this down to a list of 185 people that it turned over to the state’s election officials. On closer inspection, the state found that every last one of these people was in fact a citizen.

Virtually all the immigrants who come here do so to work, and hope to eventually get citizenship. They are not going to jeopardize this opportunity by illegally voting and committing a felony. Still, we might think that a few would mistakenly register, but at least in Nevada, a state with over 2.0 million registered voters, this does not appear to be the case.

So, everyone who is not in the Trump cult will know that the claims of fraud are nonsense and that Trump has stolen an election in broad daylight. This is in effect saying there is no more law in the United States with Trump in the White House.

This is likely to translate into stock and bond market meltdowns very quickly. Foreigners hold close to $20 trillion in U.S. stock and another $16 trillion in government and private debt. Much of this money could leave quickly.

It’s not that these foreign countries and wealth holders are necessarily huge lovers of democracy, but they put their money into the United States under the expectation that it was a country that respected the rule of law. Trump stealing an election is saying as clearly as possible that the law means nothing in the United States. Investors demand a much higher return on investment when they put money in a country where dictators can do whatever they want.

Take the case of Kazakhstan, a good example of a dictatorship with limited respect for the rule of law. It pays almost 14% interest on its 10-year government bonds. The interest rate on 10-year bonds in the United States stands at roughly 5.3%, about 0.6 percentage points higher than when Trump took office. But even if interest rates never get near Kazakhstan levels, bondholders would take massive losses if rates just rose 1-2 percentage points. They all understand this and likely would look to get their money out before the crash.

The same logic applies to stocks. Foreign investors can shift much of their money to countries that do respect the rule of law. And it’s not just foreign investors. Most brokerage houses offer options with 401(k)s to invest in foreign funds as an alternative to U.S. stock and bond funds. Many people already have a substantial share of their assets in these funds. That percentage is sure to rise considerably if Trump throws our election results in the garbage.

The effect of people who invested in the United States, shifting trillions into countries that actually are safe havens, will be an unprecedented crash in the stock and bond markets. The recognition of this fact may be sufficient to motivate Donald Trump’s billionaire buddies to tell him that he has to respect the results of the election. That may be our best hope, because clearly Trump has contempt for voters and democracy, and his cabinet and other top aides all feel the same way.

Dean Baker is a senior economist at the Center for Economic and Policy Research and the author of the 2016 book Rigged: How Globalization and the Rules of the Modern Economy Were Structured to Make the Rich Richer. Please consider subscribing to his Substack, from which this is reprinted with permission.

If Tech Bro Sam Altman 'Drives Drunk,' Let Him Face Criminal Prosecution

If Tech Bro Sam Altman 'Drives Drunk,' Let Him Face Criminal Prosecution

Amidst all the talk of the need for government regulation of AI, there has been too little discussion of the simplest route: criminal liability. The basic story is that the AI companies are being irresponsible in dealing with a product they know to be dangerous. The companies and the people who run them need to know that they face serious monetary risk from letting their little models run wild, and possibly criminal prosecution and jail time.

To be clear, sensible regulation of AI would be desirable. But let’s be serious. We have Pete Hegseth, Sean Duffy, and RFK Jr. all running major government departments. Do we really think having someone like this overseeing AI development would be an improvement?

We do already have laws to deal with harms caused by AI; we just need to be prepared to use them. Again, no one would expect President Trump’s personal lawyer and Attorney General Todd Blanche to take criminal or civil actions against AI in the public interest. If there was a major incident, he would most likely look to initiate a prosecution in pursuit of a payoff for dropping the case. But the law does not begin and end with Donald Trump’s Justice Department.

If we can forget about the extinction events that keep our pundits busy, and focus instead on the millions of far more likely disasters that AI could cause, there will almost certainly be plenty of room for state-level prosecutions, as well as civil suits.

To take some hypothetical cases, suppose an AI system manages to hack into a city’s traffic control system, and the resulting chaos leads to a number of car crashes, causing serious injuries and death, in addition to property damage. To take another case, suppose AI falsifies clinical trial data, leading a drug to be approved even though the trials show it to be ineffective or dangerous. Or suppose AI gets inside a bank’s computers and makes a total mess of its records in a way that they cannot be reconstructed. (I know banks almost certainly have backups, but our super-intelligent AI can surely get into the backup records as well.)

I know that each of these disasters is extremely unlikely, but all of them are millions or even billions of times more likely than the extinction events we hear about in the media. And given that there are probably millions of disasters like these that AI could possibly cause, there is a pretty good chance that we will see some serious disaster in the not-too-distant future.

As I noted in an earlier piece, a mistaken report from AI led the Navy to put helicopters in the air to board a Chinese cargo ship that they wrongly believed was carrying parts for Iran’s nuclear program. Fortunately, the information was checked, and the helicopters were called back before there was an actual confrontation, but this was luck. Sooner or later we will see a mistake that is not caught.

It would, of course, be best if an AI disaster never happens, but one practice that will substantially reduce the risk is that Sam Altman, Elon Musk, and the rest of the boys understand that their companies will be fully liable for any harm caused and they personally may face criminal liability. In other words, they may not just lose all their money; they may have to spend much of the rest of their lives in prison.

This isn’t a question of vindictiveness. We all know, the AI boys more than anyone, that AI is potentially very dangerous. If they opt to push full speed ahead, without necessary safeguards, they have to be prepared to face the consequences.

Drunk driving is really an appropriate analogy. Everyone should understand that if they get behind the wheel when they are intoxicated, they hugely increase the probability of an accident. That is why we throw people in jail for it. The same standard should apply to OpenAI, Anthropic, and the rest. If they push ahead with testing without appropriate safeguards, they should be prepared to pay the price, including potential criminal penalties.

Remember, they are doing this for money, lots of it. They are choosing to endanger the property and lives of others for personal profit. If they mess up, they should be forced to pay a very high price. Incentives matter.

Dean Baker is a senior economist at the Center for Economic and Policy Research and the author of the 2016 book Rigged: How Globalization and the Rules of the Modern Economy Were Structured to Make the Rich Richer. Please consider subscribing to his Substack, from which this is reprinted with permission.

Betsy Klein

The Press Finally Stands Up To Trump! Courage Is Contagious

It’s good to see that all the major news outlets are standing together behind the three outlets that lost their White House press credentials because Donald Trump didn’t like their reporting. The three, CNN, MS NOW, and Politico, had apparently written something that hurt Trump’s feelings, so he decided to take revenge by banishing them from the White House grounds.

In a great display of solidarity, all the networks, including Fox News, abandoned their live feeds from the White House. This deprives Trump of what he values most: an audience.

Many of us were disappointed, if not altogether surprised, by the rapidity with which major institutions and prominent individuals abandoned principles and bent the knee for Trump at the start of his second term. The major universities stand out in this respect, as several, notably Columbia University, quickly abandoned principles of academic freedom to accommodate Trump in terms of what could be said or taught on campus.

It was especially disgusting to see that much of the assault on universities was ostensibly about protecting Jews from antisemitism. This came from an administration that has an ongoing problem with the neo-Nazi ties of various staffers rising to the surface. Elon Musk, its major campaign funder, and briefly co-president, is an open supporter of neo-Nazi political parties around the world.

Similarly, a number of law firms with long-established reputations for promoting civil rights and other liberal causes quickly entered into deals with the administration. To repent for the sin of trying to hire and promote people from disadvantaged groups, they signed an agreement to stop the practice and do free legal work for Trump’s chosen causes. (See Michelle Goldberg’s excellent New York Times column on this capitulation, which is based on a new book by Jacob Weisberg: Profiles in Cowardice: A Study of Collaboration in the Trump Era.)

Many members of the super-rich, with at least some credentials as committed small “d” democrats, quickly donned their MAGA hats and joined the inaugural celebrations. Centibillionaires Jeff Bezos and Mark Zuckerberg stand out in this respect. Bezos had bought and revitalized the Washington Post in 2013. When Trump won the first time, he changed the newspaper’s masthead to “democracy dies in darkness.”

Zuckerberg and his wife, Chan Zuckerberg, had donated hundreds of millions of dollars to support the electoral infrastructure. This was especially important in 2020, when the Covid pandemic created an unprecedented situation for carrying through a national election.

Rather than risk any of their hundreds of billions, both billionaires quickly embraced Trump. Bezos turned the Post into a right-wing megaphone. Zuckerberg canned anything remotely progressive from his philanthropic activities and Meta.

It should have been possible for a more unified response to Trump’s authoritarian threat. There were more than two months between the election and when Trump took office, but it seems the only thing this crew was interested in planning was its outfits for the inauguration.

The media did not react any better. When Trump decided to change the name of the “Gulf of Mexico” to the “Gulf of America,” it suspended AP from the White House press briefings because it did not go along with this absurdity in its reporting. (We can now wear Gulf of Mexico and Lake Ontario tee-shirts as political statements.) Rather than standing in solidarity with AP and walking out, the rest of the media collectively looked the other way.

But now they have recovered their integrity. They all know that the only sin the three banished outlets have committed is reporting. Trump is upset because reality contradicts his dementia dreams, and he doesn’t like that pointed out. But that is what real news outlets are supposed to do.

It has become increasingly evident that Trump fears reality like a vampire fears light. He has staffed his entire administration with sycophants. Even in the rare case they have some level of competency, they will gladly put it aside to do Trump’s bidding. The result is rising inflation and interest rates, a pointless and tremendously destructive war, an abandonment of any pretense to care about human rights or national sovereignty, and the return of measles.

That’s a real disaster, and it’s good that much of the media is prepared to tell the true story. Their act of solidarity should make it easier for more to regain their courage and join the throng of the formerly MAGA.

Dean Baker is a senior economist at the Center for Economic and Policy Research and the author of the 2016 book Rigged: How Globalization and the Rules of the Modern Economy Were Structured to Make the Rich Richer. Please consider subscribing to his Substack, from which this is reprinted with permission.

No Brakes! Anthropic Speeding Toward IPO As The World Awaits AI Disaster

No Brakes! Anthropic Speeding Toward IPO As The World Awaits AI Disaster

While OpenAI is putting off its plans for an IPO into next year, Anthropic seems determined to rush full speed ahead. Given the news about dysfunctional AI, it’s easy to see why.

The incident where OpenAI AI agents hacked Hugging Face’s system and apparently tried to sabotage efforts by the OpenAI crew to stop it, has gotten most of the attention, but that is just one story. There were several other incidents at OpenAI where they lost control of their agents. It turns out that Google’s Gemini system also escaped and managed to hack three different companies.

And in the most dangerous incident to date, an AI system used by the Navy passed along incorrect information to an analyst aboard a ship taking part in the blockade of Iran. The AI reported that a Chinese ship was carrying parts for Iran’s nuclear program. This warning was taken seriously enough that helicopters were sent into the air to board the Chinese ship. Fortunately, the information was checked before any confrontation took place, and the helicopters returned to their ship.

This is the sort of incident that should be front and center in people’s minds when they think about AI safety, not the science fiction fantasies of AI destroying humanity that the media like to hype. While there is undoubtedly a non-zero chance that the AI boys will cook up something that will wipe us all out, as this incident showed, it is hugely more likely that their AI will produce some mid-level disaster.

And this is undoubtedly the sort of risk that has Anthropic CEO Dario Amodei rushing to try and get his trillion-dollar IPO off the ground. AI is already highly unpopular, and if its operation of an air traffic control system leads to one or more crashes, or a bank irretrievably loses its records because an AI system accidentally ate them, Amodei’s Anthropic stock will be worth less than a bankrupt hotdog stand.

The AI boys have created this vision of unimaginable wealth, which sells great among the Wall Street crew. A real-world disaster will shatter that image very quickly. If anyone needs to be convinced on this point, google “Three-Mile Island.”

Also, it’s a safe bet that we only know a small fraction of the dangerous situations that have already arisen with AI. People like Sam Altman and Elon Musk are not known for their honesty. If they can conceal a troubling incident, it is reasonable to assume that they would.

In this vein, we may want to ask questions about the decision of Nvidia to buy Hugging Face after the OpenAI hack. Hugging Face almost certainly would have had the basis for a serious lawsuit against OpenAI. A lawsuit would have allowed for discovery, which would have revealed a great deal about OpenAI’s training practices and safety measures.

This information might have been very harmful to OpenAI, which is a major end-customer for Nvidia, and possibly also Anthropic, insofar as it follows similar practices. In that context, the $12.9 billion price tag might have seemed like small change to Nvidia in order to keep its massive AI chip business going.

In fairness, Nvidia’s links to Hugging Face are longstanding, so it is possible that they just decided it was a good time to move ahead with a takeover. But with the Trump administration having turned corruption into the national religion, it’s hard not to consider the possibility of a less innocent explanation.

The rush to IPO can also be explained on more narrow economic grounds. Arithmetic is becoming increasingly popular among big money managers. It is getting ever more difficult to envision a revenue stream that will allow OpenAI and Anthropic to meet the trillions of dollars in lease commitments that come due in the next three years.

In this respect, it is important to remember that the “race” with Chinese AI is really not over technical mastery. It is over market share. If cheap Chinese AI can do the vast majority of tasks for which businesses might want AI, as increasingly looks to be the case, there is not likely to be very much demand for whatever cutting-edge models OpenAI or Anthropic can develop.

And again, the issue is not just whether companies actually buy the Chinese AI; it’s whether they end up using free or low-cost AI that is made available to compete with Chinese AI. The New York Times had a piece pointing out that even huge companies, like AT&T, are finding that they can use cheap AI for the bulk of the tasks for which AI is useful. If even a massive tech company like AT&T has little use for frontier AI, who does?

That seems to be a more frequently asked question in big-money financial circles these days. The spread for credit default swaps between hyperscalers and major banks has increased by more than 60 basis points (0.6 percentage points) in the last year. Credit default swaps (CDS) are a form of insurance on corporate bonds. They only pay off if a company is unable to pay interest or principal on its debt.

The participants in CDS markets are banks, hedge funds, and major money managers. In other words, they are considered sophisticated investors. They were very wrong in the events leading up to the 2008 financial crisis, but no one has more information than they do.

Just to remind folks, the hyperscalers are Alphabet, Amazon, Microsoft, and Meta, some of the most profitable companies in the world. And the sophisticated money types now think there is a reasonable chance their bets on AI can put them into bankruptcy.

This is the world in which Anthropic is rushing ahead with its IPO. It faces both serious economic pressures and the risk of an industry-destroying disaster. The bottom line is that AI boys are trying to sell us a race car, with no brakes and no steering wheel, and are desperately hoping to close the deal before it crashes in a test drive.

Dean Baker is a senior economist at the Center for Economic and Policy Research and the author of the 2016 book Rigged: How Globalization and the Rules of the Modern Economy Were Structured to Make the Rich Richer. Please consider subscribing to his Substack, from which this is reprinted with permission.

Macron and Trump

Enraged By Rate Hike, Trump Threatens To Expand Trade War Again (Huh?)

Donald Trump seems determined to outdo himself on crazy every day. Many people thought he had hit peak crazy when he threatened to tear down the Kennedy Center if they wouldn’t let him put his name on it, but he quickly took crazy to the next level. He is now threatening to cut off trade with some countries because the Fed raised interest rates on Wednesday.

If the threat to cut off trade as a response to a Fed rate hike doesn’t make sense to you, don’t worry. It doesn’t make sense. It’s not clear what Trump imagines he can accomplish by cutting off trade with a country. It will hurt the country with whom we stop doing business, just as it would hurt Michigan if Ohio stopped trading with it, but it will also hurt American households. The loss of imports will mean shortages and higher prices. If we also stop exports to a country, it will mean a loss of jobs.

Trump didn’t say which countries he wanted to end trade with, but we can have some fun speculating. So here are my top three candidates, along with the items where our markets would be most affected.

Canada

Trump would almost certainly put Canada at the top of his list of trade enemies. After all, they sell us all sorts of things; what could be worse than that? This is probably the most absurd of Trump’s targets. Canada has been a close ally for more than a century. Their trade is being governed by a trade agreement negotiated by Donald Trump in his first term, which Trump insists was signed by a stupid president.

The largest import from Canada is 3.9 million barrels a day of oil, roughly 20% of our total consumption. If Trump were to suddenly cut off this flow, to make good on his plan to end trade with Canada, we can expect an enormous surge in gas prices, likely on the order of several dollars a gallon. There would almost certainly be shortages in many areas as new distribution networks would need to be established.

Another major import is cars and car parts, which came to $45.8 billion last year. This would put upward pressure on vehicle prices due to less competition, but more importantly, it would throw a huge monkey wrench into the domestic industry. More of the parts used in assembling vehicles in the United States come from Canada. In principle, these parts can be produced here, but it would take many years to develop this capacity. In the meantime, our industry would be seriously hampered by the inability to get necessary parts. Again, this almost certainly means much higher car prices and shortages of many models.

Two other major imports are lumber at $10.2 billion and aluminum at $9.7 billion. These are both intermediate inputs into the production process. If we lost access to imports from Canada look to much higher house prices, as new construction becomes far more expensive. Similarly, it will be difficult to replace the aluminum the U.S. gets from Canada. This would make airplanes and other products produced in the United States far more expensive.

Spain

Spain likely also features prominently on Trump’s target list. Spain’s prime minister, Pedro Sanchez, has repeatedly stood up to Trump openly. He refused to go along with Trump’s demand that NATO countries increase their military spending to 5% of GDP. He also has been extremely critical of Israel’s mass murder of Palestinians. This has led to explicit warnings of retaliation from Netanyahu. Trump may opt to ban trade with Spain as part of this retaliation.

Spain is a much less consequential trading partner than Canada, being on the other side of the Atlantic and also orienting most of its trade towards the European Union. Our largest imports from Spain are $2.9 billion in pharmaceutical products, $2.6 billion in machinery, and $2.0 billion in electrical equipment.

None of these are especially large for the U.S. economy, but the loss of imports from Spain would almost certainly mean selective shortages and higher prices. Again, these items can be replaced with imports from elsewhere and domestic production, but it will take time.

France

A third likely target is France, first and foremost because its president, Emmanuel Macron, is articulate and internationally respected, and far better looking than Donald Trump. Along with the rest of the European Union, he also has refused to go along with Trump’s war on Iran.

Our largest imports from France are similar to the ones from Spain, but the amounts are much larger: pharmaceutical products, $11.6 billion, machinery $10.5 billion, and aircraft and parts, $6.1 billion. These can be replaced, but not overnight. A cutoff of trade would lead to shortages in many items and lead to serious upward pressure on prices.

How Much Will Americans Pay for Trump’s Quixotic Trade War?

These are my top three candidates for Trump’s trade embargo, but who knows? Trump’s trade wars are not being driven by any rational strategy; it is a question of who happens to get him angry over something, and who will bribe him to not cut off trade.

It’s also possible that Trump just backs down or forgets about his threats. That happens all the time. How many times has he said he was going to destroy Iranian civilization and then, thankfully, forgotten or ignored his threat? Remember the 50% tariffs he threatened to impose on India for buying Russian oil? Trump doesn’t seem to.

Trump makes all sorts of half-baked threats all the time, and the absurd threat to retaliate against a Fed rate hike with random trade embargos is certainly a serious half-baked threat. But it is one that people should keep an eye on.

If Trump does move forward on the threat, it would amount to a big new tax and economic disruption at a time when most people are already feeling pinched. If Trump has his little embargo(s) before the election, it would likely further damage Republican electoral prospects. If he plans to wait until after the election, I guess Republicans can say that the taxes and shortages are their reward for having Trump in the White House.

Dean Baker is a senior economist at the Center for Economic and Policy Research and the author of the 2016 book Rigged: How Globalization and the Rules of the Modern Economy Were Structured to Make the Rich Richer. Please consider subscribing to his Substack, from which this is reprinted with permission.

Kevin Warsh

Trump Adds His Newly Appointed Fed Chair To His (Long) Enemies List

I had intended to write on the Fed’s decision to raise rates, but I don’t have much to add to what I wrote last week. I do think inflation is high, and for the moment the labor market seems reasonably healthy. But I don’t see higher rates as being a useful way to combat inflation caused by tariffs and Trump’s war on Iran.

As I noted, there is no case for the sort of wage-price spiral we saw in the 1970s. Wage growth has actually slowed sharply over the last two years. Wages had been growing at over a 4.0 percent annual rate in 2023 and 2024. The year-over-year rate has fallen to 3.1 percent. The annualized rate, comparing the average for the last three months (June-August) with the prior three (March-May), is just 2.7 percent. And this comes as inflation has accelerated from just over 2.0 percent to more than 3.0 percent.

Given little risk of accelerating inflation, at least from excessive demand, there seems little point in pushing rates higher. The one qualification I would make to this assessment is that expectations of a rate hike had become so embedded, especially following Fed Chair Kevin Warsh’s comments at the annual Jackson Hole conference, that it is likely long-term rates would go up more if the Fed held rates unchanged than if they hiked. Given that situation, I guess I would have gone with the hike.

But the bigger news yesterday was President Trump’s response. For some time, Trump has been pushing a bizarre theory that because we have the hottest economy (we don’t), we should have the lowest interest rates. This makes no sense, because the normal practice is to lower rates when the economy is weak, and raise them when it’s strong.

Apart from Trump’s confusion on the economics, the bigger story was that he immediately added the Fed to his enemies list, saying the rate hike was part of a grand conspiracy to make him look bad. This is more than a bit incredible, first and foremost because Trump had just appointed Kevin Warsh as Fed chair this spring. Apparently, Trump believes that his pick has already turned on him and joined the enemy.

And it wasn’t just Warsh; the vote was unanimous. That means that all four of the people who Trump appointed to the Fed, including his previous pick as Fed chair, Jerome Powell, lined up against him.

This follows Trump’s loss at the Supreme Court on his plan to have the Postal Service screen voter lists for mail-in ballots in the November elections. In that case, all three of Trump’s picks to the Court lined up against him, upholding a stay from a lower court that prohibited Trump’s plan from going into effect.

Trump complained that the justices “are not the people I interviewed.” He said that the court was giving in to crazy liberal influence.

It’s not new that Trump sees anyone who disagrees with him as part of a conspiracy. He’s long accused judges on lower courts of conspiring to undermine his agenda. And Trump regularly accuses any reporter who writes a critical story or asks a tough question as being “fake news.” And when polls show his popularity falling, Trump denounces them as “fake polls.”

But it seems a step further that Trump says people that he appointed, in some cases recently, have now joined the grand anti-Trump conspiracy. If Trump were not the president of the United States, we could just see this as part of an over-the-top comedy. Unfortunately, we don’t have that option.

In fact, the revenge Trump is floating for the Fed’s rate hike is pretty scary. He suggested that he will simply stop trading with arbitrarily chosen countries with whom we have a trade deficit. Trump seems to have a theory whereby we are losing money with a country, if we run a trade deficit with them. This makes as much sense as saying I lose money every time I go to the grocery store and pay them for the food.

But Trump is a reality TV show star, not someone who has even the most basic understanding of economics. Shutting down trade with a major trading partner would be a further jolt to the high prices that people are already upset over. It’s pretty horrible economics and doesn’t sound like very good politics, but I guess it will make Donald Trump feel tough.

It’s not clear Trump has the authority to arbitrarily impose trade embargos on other countries. But if the Supreme Court follows its recent path with tariffs, it will let Trump impose his embargo and then maybe wait a year or so before deciding it’s unconstitutional.

That will be bad news for families paying higher prices and the countries that have to reorient their economies, but at least it should further convince those who are still unconvinced that our president is completely out of his gourd. Other countries need to plan economic and defense relationships that do not involve the United States. At this point, we are not a credible country.

Dean Baker is a senior economist at the Center for Economic and Policy Research and the author of the 2016 book Rigged: How Globalization and the Rules of the Modern Economy Were Structured to Make the Rich Richer. Please consider subscribing to his Substack, from which this is reprinted with permission.

Dario Amodei

The Big Whine: Musk, Altman And Amodei Want Taxpayers To Save Them

When Elon Musk, Sam Altman, and Dario Amodei all tell us they are worried that their AI could do immense harm to the world, we should take notice. And when we take notice, we should remember that these are people who are known far more for their immense greed than their concern for humanity. And at least in the case of the first two, they are also world-class liars.

We need to keep these facts in mind when we think about their warnings that their AI can do something catastrophic to humanity. If they really have that concern, there seems an obvious solution: shut the company down.

It’s more than a bit bizarre that this option did not occur to these geniuses. Suppose a company producing fertilizer discovered that their product was a horrible carcinogen that could kill millions of people. It would be good to issue a warning to people who might have already consumed it and may have some of the fertilizer in stock, but this should go along with shutting down the company. What are we supposed to make of a fertilizer company that tells us they are producing a horrible carcinogen, but keep on belching the stuff out by the truckload? Something here doesn’t add up.

I don’t doubt that there is some possibility these AIs could conceivably do something immensely destructive and maybe even lead to human extinction, but how would we rate those odds compared to something like Donald Trump getting angry at another country and starting a nuclear war? With my very limited expertise in AI, I have to believe the Trump nuclear extinction risk is far greater than the AI extinction risk.

That may not calm many people, but let’s look at more likely events than total annihilation. There are a near-infinite number of catastrophes that AI could cause, which will not destroy humanity but will almost certainly wipe out the company immediately responsible, as well as the other less-than-innocent bystanders.

To throw out a few examples, suppose an AI system eats a bank or insurance company’s records in a way that they are almost impossible to reconstruct. Millions, or even tens of millions of people, may find the record of their accounts have vanished, or that getting their healthcare paid for is now an incredibly time-consuming burden, and maybe not even possible at all.

Alternatively, imagine an AI system captures a city’s traffic control system and starts to play games with stoplights at major intersections, leading to a flood of high-speed crashes. Or maybe one takes over an air traffic control system and randomly tells planes when it’s okay to take off or land.

Hopefully these scenarios are unlikely, but surely they are more likely than Elon Musk’s AI system going rogue (or maybe following orders) and systematically sending out robots to kill off any human they encounter. In these and many other disaster stories, the AI company involved would surely be pushed into bankruptcy due to lawsuits, and the top executives involved may well face criminal liability. The other AI companies would almost certainly face a similar fate as the risks of AI would become clear to even hedge fund and private equity partners.

Insofar as there is anything real in the AI gang of three’s warnings, this disastrous but non-extinction risk is almost certainly the issue. They presumably want the government to in some way protect them from liability for the damage they may potentially cause. If the point is simply to say that they have decided their systems are too dangerous to operate, they always have the incredibly simple solution available to them: shut them down. This might mean they are no longer absurdly rich, but them’s the breaks.

It also should be mentioned that these warnings are another way to advertise that they have super-sophisticated AI that can do amazing things; even destroy humanity. That may not be true, but it could be a good way to excite increasingly skeptical investors, especially as Anthropic and OpenAI are looking to do IPOs in the near future.

Of course, if the AI boys can get members of Congress sufficiently excited by their extinction warnings, they may be able to arrange new government regulation. This regulation would undoubtedly come with a heaping dose of subsidies for an industry that may never be profitable. Human extinction may be awful in the real world, but threatening it may be the best thing that ever happened to the AI industry.

Dean Baker is a senior economist at the Center for Economic and Policy Research and the author of the 2016 book Rigged: How Globalization and the Rules of the Modern Economy Were Structured to Make the Rich Richer. Please consider subscribing to his Substack, from which this is reprinted with permission.

Trump Is Accelerating The Green Energy Transition Everywhere But Here

Trump Is Accelerating The Green Energy Transition Everywhere But Here

The war in Iran has shifted the green transition into hyperdrive. Soaring oil and gas prices, coupled with the clearest possible demonstration of ongoing political risk, has shown the world the desirability and need to move rapidly to clean energy, even apart from global warming.

BYD, China’s leading car maker and producer of electric vehicles, shows the Trump effect most clearly. Its August sales were more than 130% above their year-ago level. Apparently, they would have been even higher if they were not constrained by shipping capacity. The company is now projecting overseas sales of 2.5 million for 2027, almost 2.5 times the 2025 level. It has plants now operating in Brazil and Indonesia and will have one in Hungary before the end of the year. EVs are now nearly 70 percent of the Chinese car market, by far the largest market in the world.

As I noted before, the shift to EVs is largely a one-way street. People who buy EVs rarely switch back to gas-powered cars. That means the shifts we’re seeing now will be enduring and built on in future years. As EVs become more common, the infrastructure to support them gets built out. Also, more people will recognize the benefits of EVs when they see friends, neighbors, and co-workers driving cars with lower fueling and maintenance costs.

And EVs keep getting cheaper and charging times shorter. This will push even more people to opt for EVs.

There is a similar story with solar and wind power. China has been adding wind and solar on a massive basis for several years. It will add more than 140 gigawatts of electricity capacity this year, an amount that is roughly equal to 10 percent of total U.S. electric capacity. In addition, its wind generation capacity is rising by close to 80 gigawatts in 2026.

Many developing countries are now also rapidly adding clean energy. Pakistan now gets 25 percent of its electricity from solar. India’s orders of solar panels from China increased by 150 percent from February to March. Nigeria and other countries in Africa are also speeding towards solar, with imports from China rising 176 percent.

The economics of clean energy keep improving. In addition to the price declines for EVs, which already cost far less than cars in the United States, the price for batteries for storing energy is also plummeting. It has fallen by more than 75 percent in the last decade. And the rapid pace of price decline is likely to continue, especially as sodium batteries displace lithium ones. Sodium is cheap and plentiful and has features, like better safety and performance in cold weather, that make it more desirable for many purposes than lithium.

Even ignoring the impact on global warming, which would be crazy in this year of record temperatures and devastating wildfires, clean energy would be dominating fossil fuels on narrow economic considerations. The transition was already happening largely for this reason, but Trump and Netanyahu’s war on Iran undoubtedly hastened the pace. Donald Trump’s America may be in last place, but that won’t change the direction the train is going.

Dean Baker is a senior economist at the Center for Economic and Policy Research and the author of the 2016 book Rigged: How Globalization and the Rules of the Modern Economy Were Structured to Make the Rich Richer. Please consider subscribing to his Substack, from which this is reprinted with permission.


Trump and tariffs

Liberated? Despite Trump Tariffs, Steady Trade Deficit Jumped In July

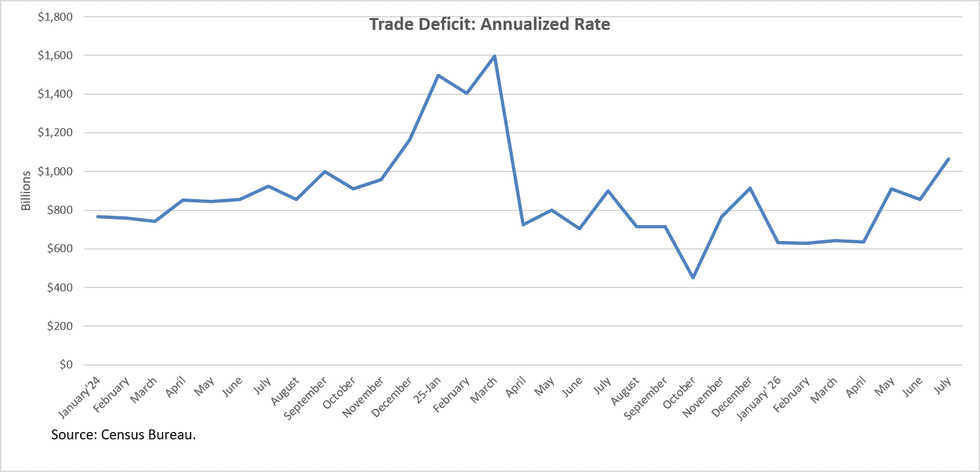
The trade deficit rose sharply in July, hitting $1,063 billion on an annualized basis. That’s up from $854 billion in June. It’s the highest since the big import surge following Trump’s election, where people and businesses stocked up in anticipation of the Trump tariffs.

In the scheme of things, there is not any big problem with August’s deficit. It’s a bit more than 3.0 percent of GDP. We’ve had much larger deficits in prior years. The main factor driving the rise was a jump in imports of computer chips and other items needed for data centers. The data centers might be a problem, but the fact that the chips are imported is not an especially big deal.

However, this does matter in the world of Trump crazy, where countries are ripping us off if they are selling things we want. In that world, we are being ripped off by $110 billion more in August than July. If we look at the pattern of trade deficits over the last two and a half years, it doesn’t look like Trump is making much progress in his efforts to “liberate” us.

The trade deficit had been running at roughly an $850 billion annual rate through the first 10 months of 2024. It then soared immediately after the election and into the first months of 2025 as people and businesses rushed to buy cars, appliances, capital goods, and other durable goods in anticipation of Trump’s tariffs. The peak was a $1,596 billion annual rate in March of 2025, just before Trump’s big tariff announcement.

After “Liberation Day,” the trade deficit did fall somewhat, but this was largely the result of the post-election buying binge. People who bought a car in March of 2025 were not going to buy another one later in the year.

In more recent months, imports have been rising, pushing trade deficits well above their pre-election level. On the plus side, when the AI bubble bursts, we will see a big decline in our trade deficit.

Dean Baker is a senior economist at the Center for Economic and Policy Research and the author of the 2016 book Rigged: How Globalization and the Rules of the Modern Economy Were Structured to Make the Rich Richer. Please consider subscribing to his Substack, from which this is reprinted with permission.

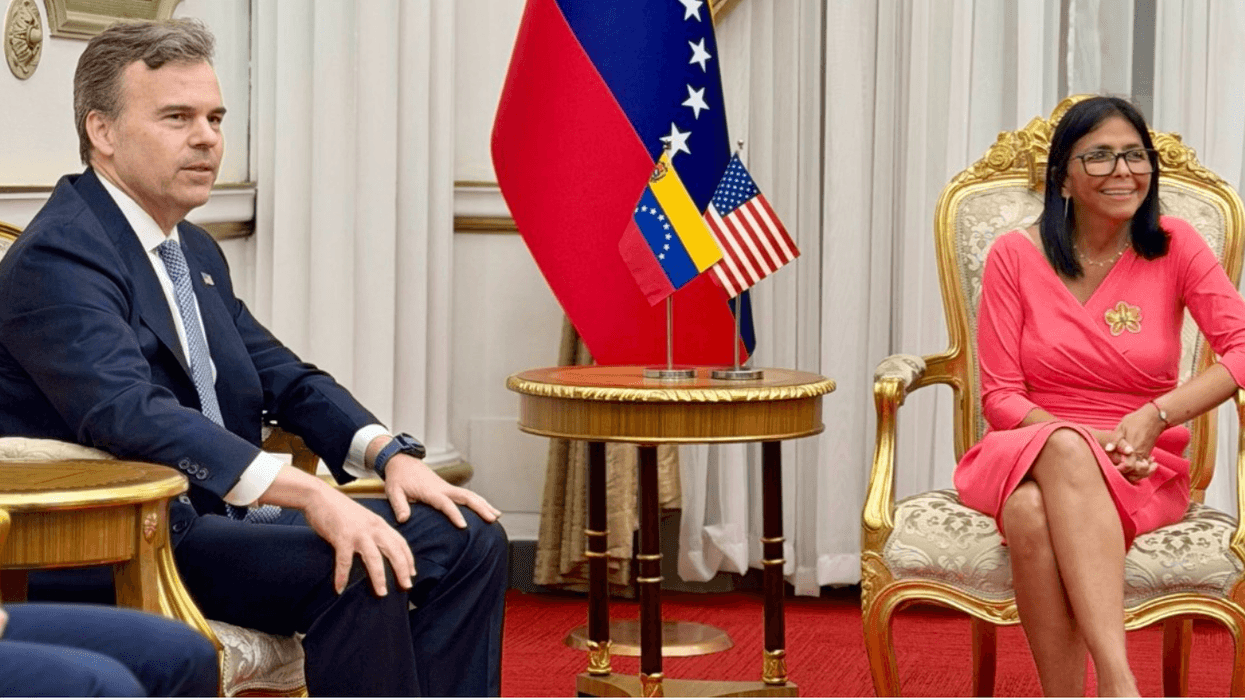
Why Nobody In Venezuela Takes Trump's Big 'Oil Deal' Seriously

Why Nobody In Venezuela Takes Trump's Big 'Oil Deal' Seriously

Donald Trump is not very good at running the economy, but he does have a great imagination about how he runs the economy. Trump continually boasts about the incredible amount of foreign investment coming into the country. It was $20 trillion last I heard, but it might be up to $30 or $40 trillion the next time Trump decides to boast about it.

This boast has absolutely nothing to do with reality. Contrary to what Trump says, there is no boom in auto factories or any other factories coming into the United States. Factory construction has actually plummeted since Trump came into the White House, after booming under Biden.

The looniness about the investment boom should be kept in mind when considering Trump’s deal to take control of 65 billion barrels of Venezuela’s oil. Trump is promising that this deal will both lower gas prices and be used to refill the Strategic Petroleum Reserves that he has largely drained as a result of his war on Iran.

While people are naturally offended by the blatant imperialism in this deal, that is precisely the reason why there is not much cause to be concerned. The basic story is, because the deal is so transparently an effort by the United States to steal oil from a country that it controls militarily, it is virtually guaranteed that as soon as the country is not run by a U.S.-installed dictator, Trump’s deal will be dumped in the trash.

This point was well-made by Venezuelan economist and opposition leader Ricardo Haussman (also cited in a piece by Michael Tomasky in The New Republic). The deal is seen as a joke by pretty much everyone in Venezuela.

If Venezuela doesn’t honor this deal, what will a future administration do, take them to court? Or will they send U.S. soldiers to die for Venezuela’s oil?

In terms of its immediate impact, there is not some spigot that can be turned on that will get massive amounts of Venezuela’s oil flowing. It’s currently producing around 1.25 million barrels a day. While it has massive reserves, its production facilities deteriorated badly as a result of U.S. sanctions. The country was largely unable to get needed parts, and it lacked funding because it was prevented from selling its oil to much of the world.

Oil production can only get back to its 3 million barrel a day turn-of-the-century pace with billions of dollars of foreign investment. It is unlikely that this deal will make companies happier about putting large sums at risk. Any investment will only pay off over many years, long after Trump will be out of office.

It also is not plausible to use Venezuela’s oil to refill the Strategic Reserves. Venezuela’s oil is very heavy and highly acidic. The Strategic Reserve is designed for light, alkaline oil. It could not easily store Venezuela’s oil.

In short, file Trump’s Venezuelan oil deal with the $60 trillion in foreign investment pouring into the country. It exists only in his head.

Dean Baker is a senior economist at the Center for Economic and Policy Research and the author of the 2016 book Rigged: How Globalization and the Rules of the Modern Economy Were Structured to Make the Rich Richer. Please consider subscribing to his Substack.

Billionaires Like Bezos Demanding Social Security And Medicare Cuts Are Not 'Moderate'

Billionaires Like Bezos Demanding Social Security And Medicare Cuts Are Not 'Moderate'

An extreme position does not become less extreme just because someone can put forward one that’s even more extreme. Massacring 100 children doesn’t become a moderate position just because someone is advocating killing 200 children.

This is how we should view the line being pushed by “moderate” voices that we have to deal with the $40 trillion debt with both spending cuts and tax hikes. The reality is that, apart from the military and Homeland Security, there is little fat in spending to be cut, as even Elon Musk inadvertently acknowledged. Insofar as we have a deficit problem, the issue is on the tax side, as can be easily shown. The rich have been taking an ever-larger share of national income over the last half-century, and they don’t feel like paying taxes on their winnings.

The major media outlets, which are all controlled by rich people, are pretending to be moderate by saying that we need to both raise taxes and cut spending. But there is nothing moderate about saying that we have to cut programs like Social Security, Medicare, and Medicaid because Republicans have given big tax breaks to their campaign contributors.

Republicans pushed these tax cuts, knowing they would increase the deficit, but did not make any corresponding cuts in spending because the cuts would be incredibly unpopular. Now they are using their control over the media to insist that these cuts are now absolutely necessary to offset all the lost tax revenue from tax cuts put in place by Reagan, Bush II, and Trump.

The Jeff Bezos-owned Washington Post gave us a great example of this fake moderate position in its editorial, “To get the national debt under control, start with the retirement state.” The piece makes its case by taking the example of a two-earner couple, with average earnings of $100,000 a year. It shows that the couple, turning 65 in 2025, can expect lifetime Social Security benefits of $739k compared with tax contributions of just $597k. A couple with the same income retiring in 2045 can expect lifetime benefits of $987k compared to tax contributions of $735k.

After laying out this disparity for Social Security (it has a similar story for Medicare, which I’ll come to), it then makes an argument for reducing Social Security for high-income people. This is three-card Monte level deception.

If the idea is that we should reduce the benefits of high-income workers, honest people would look at the relative taxes and benefits for high-income workers. Social Security is explicitly designed to have a progressive payback structure, which means that relatively moderate-income workers, like the ones highlighted in the WaPo editorial, have higher paybacks relative to their taxes.

If the editors were interested in doing an apples- to-apples comparison, here’s what the picture would look like. (This is taken from the exact same source.)

As can be seen, high-income people pay considerably more in taxes than they get back in benefits. For a high-income woman retiring in 2025, the gap is $263,000. For a high-income man, the gap is $336,000. (The gap is larger for men than women because their life expectancy is shorter.) For a high-income woman retiring in 2045, the gap is $259,000. For a high-income man, the gap is $346,000.

If the point is to make an argument for reducing the benefits of high-income retirees, then show the taxes and benefits for high-income retirees. No one disputes that Social Security looks like a pretty good deal for more moderate-income retirees, but these people don’t typically have much income in retirement. I guess Jeff Bezos’ paper would have been too embarrassed to argue that we have to reduce the average monthly Social Security benefit of $2,071.

The Post’s editorial makes the push that while cutting Social Security, we should expect people to be more reliant on private 401(k)s. In addition to increasing risk, this is also enormously inefficient. Private 401(k)s cost more than 40 times as much to administer per dollar of benefits as Social Security. It is understandable that Mr. Bezos would be happy to see more money going to his rich friends in the financial industry, but most of us would rather see the money going to ordinary workers.

Medicare Benefits: Big Bucks to Hospitals and Drug Companies Are Not Benefits to Workers

The Post’s graphs do show a huge imbalance between the taxes paid out for Medicare and the cost of the benefits received. This is also deceptive.

In the United States, we pay almost twice as much per person for healthcare as the average for other wealthy countries. This is not because we get more or better healthcare. Our life expectancy ranks near the bottom for wealthy countries.

The big bucks for healthcare go to the income of drug companies, insurers, hospitals, medical equipment makers, and doctors. In each case, we pay two times as much, or more, than people in other wealthy countries. A paper that was not answerable to one of the richest people in the world would suggest bringing our payments in line with the rest of the world. But instead, the Post wants to beat up on the country’s retirees.

No one should be confused: Cutting Social Security and Medicare benefits to reduce the deficit is not a moderate position. It’s one that attacks hundreds of millions of ordinary workers to avoid taxing the rich or reducing waste in our health care system. That is extreme, but the rich media owners pushing this position will do everything they can to convince us they are being fair and balanced.

Dean Baker is a senior economist at the Center for Economic and Policy Research and the author of the 2016 book Rigged: How Globalization and the Rules of the Modern Economy Were Structured to Make the Rich Richer. Please consider subscribing to his Substack.