Tag: biden economy
Donald Trump

Two Years On, We Can See What Trump Has Done To The U.S. Economy

As we approach the two-year mark since Donald Trump’s second election victory, it’s a good time to do a little economic scorekeeping. Before getting into where the economy is and where it’s going, it’s worth a little reminder of where it was before the election.

This is important because Trump and the Republicans continuously spew utter nonsense about an economic disaster that only exists in their imagination. By literally every standard measure, the economy was doing extremely well just before the election. The unemployment rate was hovering near 4.0 percent and nominal wages were growing at roughly a 4.0 percent annual rate.

Inflation had slowed sharply, with the year-over-year rate at 2.6 percent in October of 2024. This translated into real wage growth of close to 1.5 percent. Inflation was expected to continue to slow, with most projections having inflation coming in very close to the Fed’s 2.0 percent target by the end of 2025.

There had been a massive surge in the number of people able to work from home as a result of the pandemic, with that figure still being close to 20% by the end of 2024. These people were saving hundreds of hours a year in commuting time and thousands of dollars annually in commuting-related costs. There also had been an unprecedented explosion in factory construction, with real spending in 2024 more than double the pre-pandemic level in 2019.

Growth for the year was 2.5 percent, and it was expected to be above 2.0 percent for the near future. This story was the basis for The Economist’s famous cover story about the U.S. economy: The Envy of the World.

Trump Takes Over: The Story Darkens

Virtually without exception, the data have gotten worse under Trump. Inflation has risen; nominal wage growth has slowed. Factory construction has plummeted. The trade deficit, which he views as a central measure of economic failings, has soared. Interest rates have risen, and the United States has fallen far behind the world in the green transition. China’s production of wind and solar energy exceeds our total production of energy. People have lost health insurance coverage, and costs are soaring for those who still have it.

The economy has become almost completely dependent on the AI bubble, as most other forms of investment are being crowded out. With real wages falling and job growth slowing to a trickle due to mass deportations, consumption growth is almost entirely dependent on stock price appreciation, which is in turn almost entirely driven by AI stocks.

This darkening picture began even before Trump took office. There was a huge surge in imports of durable goods like cars and TVs, starting right after the election. Consumers and businesses tried to buy ahead of Trump’s promised tariffs. Prices for durable goods, which had been falling through 2023 and 2024, began rising at the start of 2025. They rose further when Trump imposed the bulk of his tariffs in April. Instead of falling to 2.0 percent, inflation was 2.7 percent by the end of 2025, having hit 3.0 percent as a year-over-year rate in September.

Job growth fell sharply almost immediately after Trump took office, with the average monthly rate for his first year being just 27,000, down from an average of 103,000 for the last year of the Biden administration. Part of this slowing was due to the DOGE purge of federal government employees, but even pulling out the federal government, there was a slowing from 100,000 a month to 53,000. The main factors behind the slowing were the policy of mass deportation, which cut net immigration to near zero, and the tariffs, which both raised prices and led to enormous uncertainty.

The weakening of the labor market led to a sharp slowing in wage growth. While unemployment remained relatively low, workers became much less likely to switch jobs. Since job switching accounts for a disproportionate share of wage gains, the rate of nominal wage growth slowed sharply, from over 4.0 percent in 2024 to just 3.0 percent in the most recent data. With inflation accelerating to 3.5 percent, real wages are falling.

Growth Without Wage Growth

With job growth slowing to a trickle, roughly a 0.2 percent annual rate, and real wages falling, workers’ spending cannot drive consumption. While consumption is still growing at a healthy pace, it is clearly because of stock market gains. In the last three years, the market has risen by more than 80 percent, which translates into roughly $40 trillion in new stock wealth. The wealth effect on consumption is usually estimated as being close to three cents on a dollar. This means that the rise in stock wealth has added close to $1.2 trillion to annual consumption over the last three years, an amount equal to almost 4.0 percent of GDP.

This run-up was overwhelmingly an AI story. The value of AI-related companies has more than doubled over the last three years.

If AI has been driving consumption, its impact on investment has been even larger. Excluding data centers, investment in structures is down by almost 10 percent since the fourth quarter of 2024. Outside of information processing equipment, investment in equipment has been essentially flat under Trump. AI has also accounted for more than 80 percent of the investment in intellectual property products since 2024. In short, the story of investment growth under Trump is AI.

One of the ironies of the surge in spending on AI is that it has caused a sharp rise in the trade deficit. While there can be problems with a large trade deficit, such as the surge at the start of the century that cost millions of manufacturing jobs, the trade deficit had fallen back to roughly 3.0 percent of GDP when Trump took office, a level that can be easily sustained indefinitely.

The expectation of tariffs caused deficits to soar in the first quarter of 2025, but they then fell back to roughly their 2024 level after the tariffs were in effect. But they have been rising rapidly in recent months, passing $100 billion in August, due to a surge in computer chips and other AI-related items. This pace would put the trade deficit at over 4.0 percent of GDP.

Budget Deficits, Interest Rates, and Housing

At various points in his campaign, Trump promised that he was going to balance the budget or even pay off the debt. This isn’t happening. The deficit has increased under his watch, hitting $1,993 billion in fiscal 2026, up from $1775 billion in fiscal 2025. The biggest factors in this increase were a decline in corporate income taxes and higher interest payments on the debt. At more than 6.0% of GDP, the deficit is a record for a period when we are not in a war or recession.

It is worth mentioning that there have been cuts in spending that partially offset the tax cuts. While these are not large in terms of the total budget, they have had noticeable short-term effects and could have substantial long-term effects. On the short-term side, cuts to Medicaid and the ACA exchanges have led to an increase in the uninsured population. It rose by roughly 1 million from 2024 to 2025 and is virtually certain to rise considerably more in 2026 and beyond. Ending funding for the Africa AIDS program could lead to millions of preventable deaths in the years ahead.

The longer-term harm is likely to come from cuts to NIH funding and other federal research pools. In addition to the direct impact of the cuts, the arbitrary restrictions and politicization of grant awards, coupled with the harassment of leading research universities, have already sent many top researchers to other countries. As a result, they will likely be the primary beneficiaries of what otherwise would have been American innovations.

As noted, the higher deficit is partly due to higher interest rates, but the deficit does not seem to be the main cause of higher rates. Rather, the massive demand for capital to build data centers for AI is a much more important factor. In any case, long-term interest rates have risen sharply under Trump. The 10-year Treasury rate had been as low as 3.6 percent in September of 2024 and was heading downward. It turned around under Trump and now stands at almost 5.3 percent.

The high interest rates have weakened housing construction. It has averaged 1.35 million units a year. We probably need a construction rate of around 1.6-1.7 million units to have a noticeable impact in bringing house prices down. The rate was well over 1.7 million in 2022, before the Fed started raising rates.

The Future of the Economy is the Future of the AI Bubble

The Trump economy really does boil down to AI. If we believe the hype, we are about to see an incredible surge in productivity that will make us ridiculously wealthy. To date, there is no evidence to support this view. Productivity growth has been at best on its trend pace the last couple of years.

The stock market is priced as though we will see this massive AI payoff. As noted earlier, we saw a massive run-up in stock prices. Part of this is due to a rise in after-tax profits, as there has been a shift from wages to profits and a reduction in corporate income taxes. But the more important factor has been an increase in price-to-earnings ratios, with the market-wide average near the record levels hit in the tech bubble.

If we don’t see the massive gains in productivity promised by the AI enthusiasts, then we will almost certainly see a collapse in the stock market, with a serious recession almost guaranteed. On the other hand, if AI does have the promised payoff, all will be good, as long as the AI barons don’t steal all the money.

Dean Baker is a senior economist at the Center for Economic and Policy Research and the author of the 2016 book Rigged: How Globalization and the Rules of the Modern Economy Were Structured to Make the Rich Richer. Please consider subscribing to his Substack, from which this is reprinted with permission.
Average Gas Prices Were Slightly Higher Under Biden, But Trump Is Closing In Fast!

Average Gas Prices Were Slightly Higher Under Biden, But Trump Is Closing In Fast!

As I’ve come to realize in the last five years, people take the price of gas very seriously. It features very prominently in their assessment of the economy and their personal finances. For that reason, it is worth taking a quick look at what has happened to gas prices under Donald Trump and his predecessor, Joe Biden.

When Biden came into office, in January of 2021, gas was very cheap, selling for just under $2.40 a gallon. That was primarily because the economy was still feeling the effects of the pandemic. Unemployment was 6.4 percent, and we were down six million jobs from the pre-pandemic period.

The price rose quickly as the U.S. and world economy recovered, reaching $3.40 by February of 2022. Part of the reason for the rapid rise was that oil that had been taken out of production could not be instantly restarted once demand increased. Removing oil from production during the pandemic was a political decision taken in part by Donald Trump, in order to prevent oil producers from taking large losses.

Prices rose much further when Russia invaded Ukraine in February, and Biden responded by putting sanctions on Russian oil. The price peaked at over $5 a gallon in June but then fell back quickly as more oil came online. By the end of 2022, it had fallen to around $3.20 a gallon. It hovered around this level until Biden left office.

In January of 2025, when Donald Trump took office, the price was around $3.10 a gallon. It stayed around this level through most of the year, falling somewhat below $3.00 in December and bottoming out at $2.80 in January of 2026.

Then the decision to attack Iran sent gas prices soaring. They hit $4.00 a gallon by the end of March and peaked at over $4.50 a gallon in early May. Since then, they have bounced around in response to reports of peace agreements and new threats but have mostly been near $4.00 a gallon. (They are $4.08 today.)

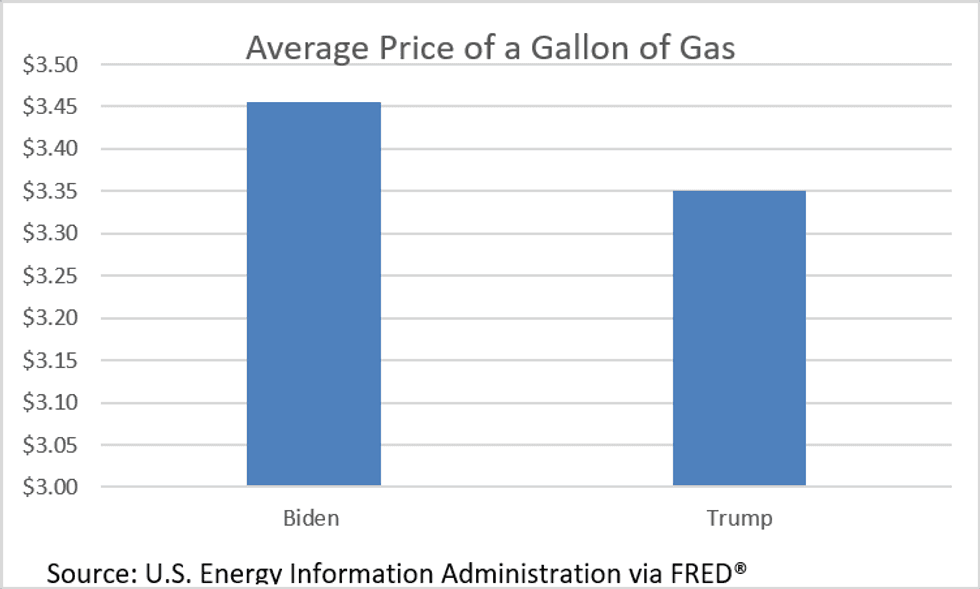
Taking the averages to date, prices are still somewhat lower under Trump than under Biden: an average of $3.35 a gallon under Trump compared to $3.46 in the four years of the Biden administration.

However, this gap is being whittled away with gas over $4.00 a gallon due to the largely closed Strait of Hormuz. If gas prices are not brought down, Trump will soon be able to boast of having higher gas prices on average than Joe Biden.

Dean Baker is a senior economist at the Center for Economic and Policy Research and the author of the 2016 book Rigged: How Globalization and the Rules of the Modern Economy Were Structured to Make the Rich Richer. Please consider subscribing to his Substack.


Will Surrendering To Iran Relieve Trump's Gas Pains? Alas, Probably Not!

Will Surrendering To Iran Relieve Trump's Gas Pains? Alas, Probably Not!

Donald Trump’s rhetoric on Iran oscillates wildly from day to day, sometimes from hour to hour. But Trump has run out of military options that don’t involve huge war crimes, so we seem to be heading for a reopening of the Strait of Hormuz on Iran’s terms. And that includes the imposition of de facto tolls, whatever they are called.

There is no mystery about Trump’s surrender: He’s desperate to end the war because he is paying a steep political price for high gasoline prices, and the midterms are only four and a half months away.

But can Trump rehabilitate his standing with American voters by throwing in the towel? Probably not, for both economic and political reasons. I would argue that there are four points of slippage between Trump’s political goals and what is likely to happen.

The state of the Strait: Even if the war is truly over, it will take time to return world oil supplies to normal levels. First, there has been substantial damage to the Persian Gulf’s infrastructure, which will take months, if not years, to repair. Second, many oil tankers are now in the wrong place and it will take weeks or months to move them. Third, some shipping channels are at risk from stray mines. Lastly, the world met the Hormuz crisis in part by running down oil inventories, which will now need to be rebuilt.

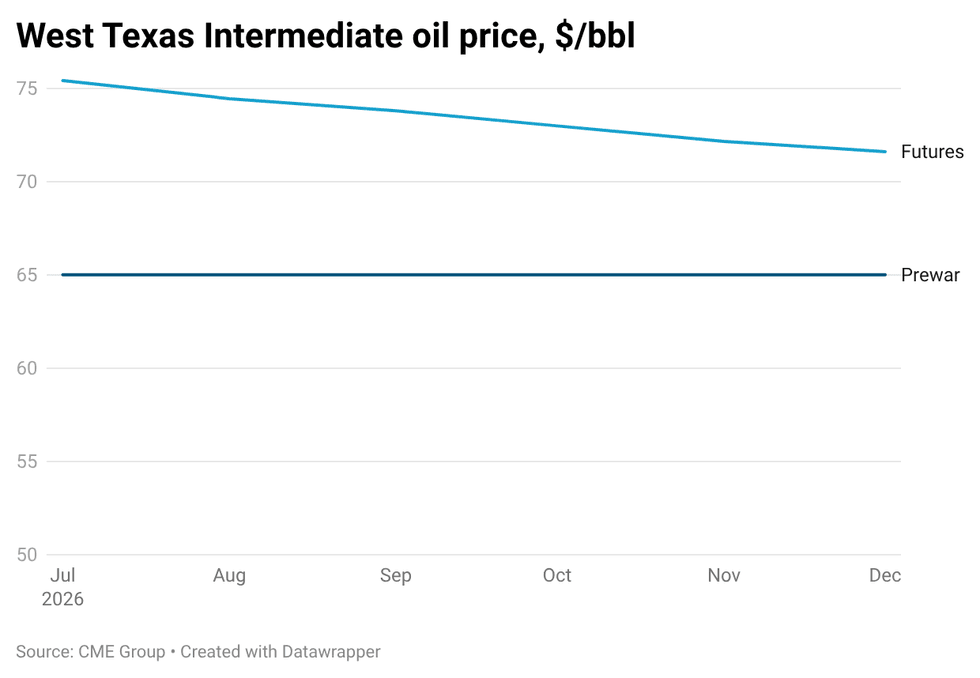
It’s true that a surge in Iranian oil exports has begun thanks to the lifting of the U.S. blockade. This will add to global oil supplies but will also strengthen the regime. But despite this surge of Iranian shipments, prices of oil futures — promises to buy or sell oil on specified dates — indicate that the oil markets expect oil prices to decline at only a slow rate for the rest of this year:

west texas intermediate oil price

Rockets and feathers: There is a well-documented pattern to how the price of gasoline responds to changes in the price of crude oil. When there is a global shock that causes the price of crude oil to soar, gasoline prices rise like a rocket. But when the crisis is over and crude prices plunge, the price of gas declines only gradually ­— it drifts down like feathers.

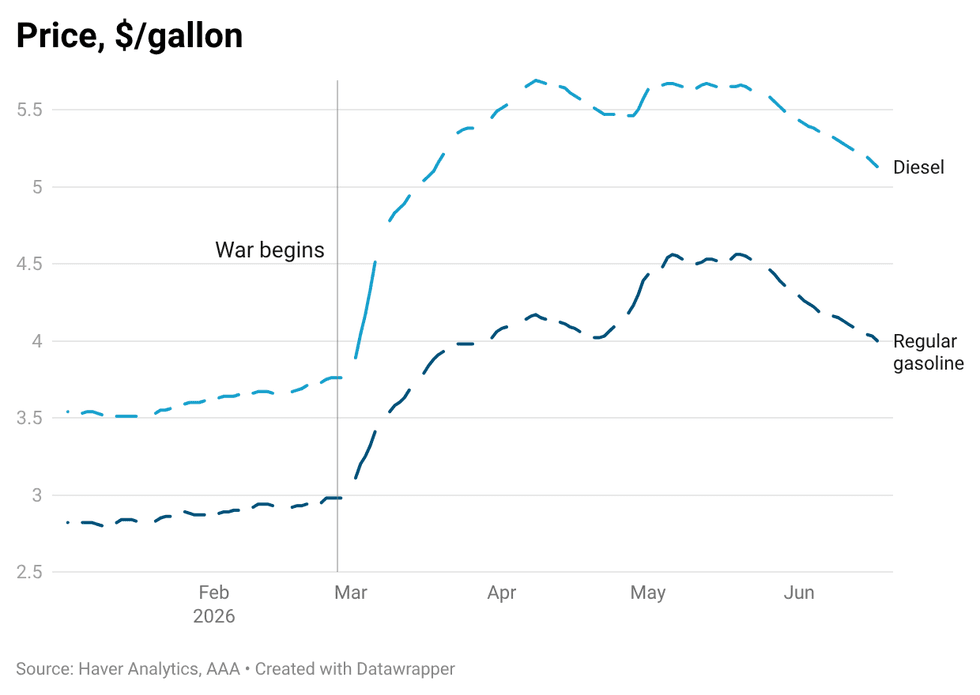
Will that happen this time? Gasoline and, to a lesser extent, diesel, have fallen considerably in price from their peak:

oil price

They are, however, still well above their prewar levels, and by more than you would expect given the commonly used rule of thumb:

$10 on price of crude = $0.25 on price of gasoline

Crude oil prices are $10-$15 a barrel higher than they were prewar, which would point to gasoline prices $0.25-$0.37 higher per gallon. Yet gasoline is currently almost $1 a gallon higher than it was before the war.

So if the “rockets and feathers” pattern continues to apply, gasoline prices will be elevated for months to come, thwarting Trumpist hopes of quick political relief from capitulating to Iran.

Prices beyond gasoline: As you can see in the chart above, the war on Iran sent the price of diesel fuel soaring by significantly more than the price of gasoline. Unlike gasoline, which is mainly purchased by consumers, diesel is mainly used by businesses, for trucking and industrial uses. So the surge in diesel prices led to a surge in business costs rather than a direct burden on consumers.

True, businesses do eventually pass higher costs on to consumers. The key word, however, is “eventually.” This means that there is probably substantial Iran war-induced inflation still in the pipeline.

Nor were soaring prices of diesel the only cost the war imposed on businesses. The Persian Gulf is normally a key supplier of many chemicals, whose prices soared when the Strait of Hormuz was closed. For example, the price of urea, a key fertilizer with industrial uses as well, temporarily rose by 75 percent when the Strait was closed. Again, some of the effect of these cost shocks still hasn’t hit consumer prices.

Moreover, the economy is delivering inflationary shocks independent of the war. Notably, the AI/datacenter boom has driven a rapid rise in electricity prices and huge increases in the prices of memory chips, which are used in almost all consumer electronics, from smartphones to laptops to game consoles. The AI boom has also pushed up interest rates on mortgages and consumer loans. Oh, and Trump’s cuts to Obamacare subsidies are causing many Americans’ health insurance costs to soar.

So while consumers are getting some relief at the gas pump, they’re facing persistent sticker shock on many other goods. It’s safe to predict that consumers won’t be in a celebratory mood on D-I [defeat by Iran] Day. Instead, they are likely to feel that any claims of victory are Pyrrhic at best.

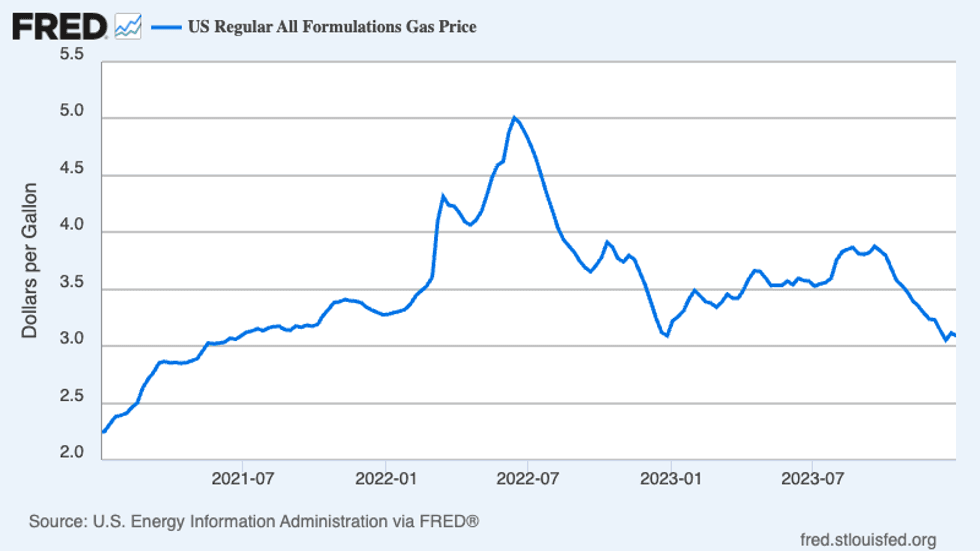
The cost of broken promises: We have just endured the second big gasoline price shock of the past five years. The previous shock, during the Biden years, briefly sent average prices of gasoline above $5 a gallon. Like the recent price spike, the 2022 run-up in gas prices was largely caused by a war — the war between Russia and Ukraine. That wasn’t a war that the U.S. president launched on a whim. Regardless, the price of gasoline fell rapidly after June 2022:

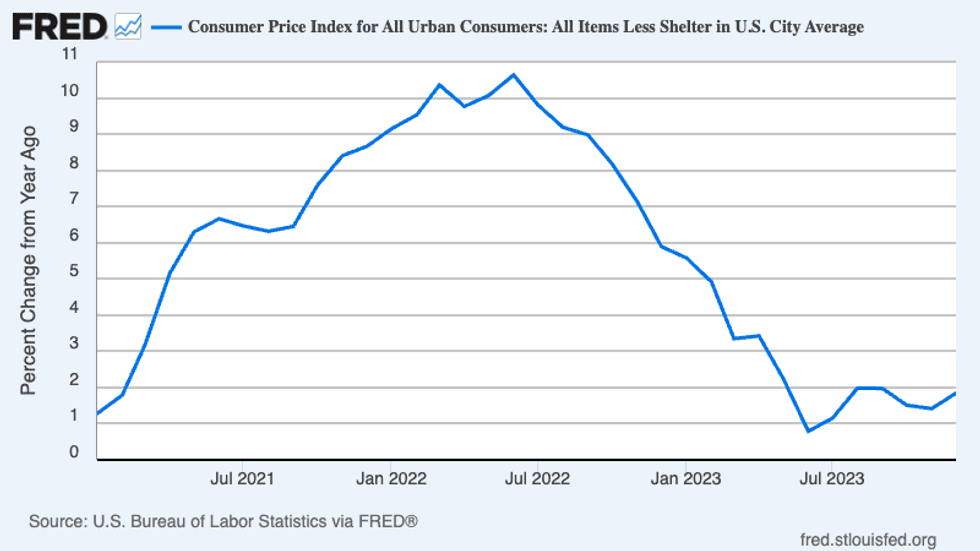
Inflation also fell rapidly, especially if you exclude the price of shelter, which as measured tends, for technical reasons, to lag far behind market prices:

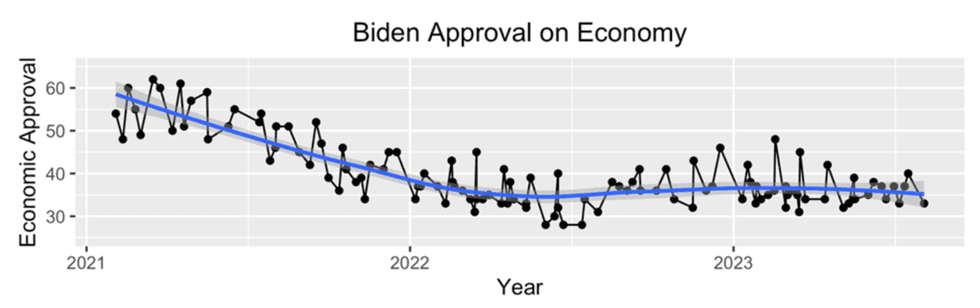
So what did cheaper gas and rapid disinflation without a recession do for perceptions about President Biden’s handling of the economy? Almost nothing. The Roper Center published an analysis of trends in Biden’s economic approval rating, and found hardly any improvement when gas prices and overall inflation plunged:

You may argue that this was unfair because Biden was punished for a global inflation shock that wasn’t his fault. Furthermore, his overall economic management was in fact very good. In fact, that’s what I have argued, and a majority of Americans now say that the economy was better under Biden than under Trump. However, that argument is beside the point for analyzing the effect of the Trump surrender. The point, instead, is that once a leader has lost the public’s economic trust, that trust doesn’t come back just because gasoline prices have receded.

I would add that it may be especially hard for the Trumpists to make the case that things have turned around when they were never willing to admit that anything was wrong in the first place, insisting even as prices soared that we were living in a “golden age.”

So will Trump’s surrender to Iran rescue him and his party from a blue wave in November? It’s very unlikely. I suggest they find themselves some lifejackets.

Paul Krugman is a Nobel Prize-winning economist and former professor at MIT and Princeton who now teaches at the City University of New York's Graduate Center. From 2000 to 2024, he wrote a column for The New York Times. Please consider subscribing to his Substack.

Reprinted with permission from Paul Krugman.


Joe Biden

Wake Up And Look At What's Really Happening In The Biden Economy

You may have noticed in recent weeks that alarming headlines about inflation – specifically, those ubiquitous stories about the cost of gasoline, or eggs, or other household goods – have vanished. Media outlets no longer feature those fearsome charts with arrows zooming skyward, or video loops displaying the latest eye-popping gas station signage.

Much as the mainstream media seemed to enjoy scourging President Joe Biden with the bad news about raging hikes in the price of everything, that depressing theme has disappeared because inflation is falling.

In October, what economists describe as “core inflation,” meaning the price of goods and services other than food and energy, declined to 2.0 percent – the target set by the Federal Reserve. And what they understandably call “headline inflation,” the more volatile measure of prices that include all consumer purchases, including groceries and gas, dropped on a monthly level to zero.

Got that? Zero. Year over year, the rise in personal consumption expenditures has plummeted to three percent.

So encouraging were those numbers to the financial sector – and presumably the central bankers at the Federal Reserve – that some now forecast a cut in interest rates. Dropping rates would likely prevent the recession that has been forecast (with glee) by many Republicans – and bring America in for a “soft landing” from the pandemic recovery.

Will Biden get any credit for this improvement? Not from most media organizations, nor from pundits who wrongly blamed him for the inflation spurt in the first place, when they knew that other countries were suffering much worse price increases in the pandemic’s wake. Indeed, too many outlets are barely even noting that inflation has collapsed.

At the same time, the president’s “Bidenomics” program has brought continued steady growth and strong employment, with the annualized gross domestic product topping 5.2 percent in October – and unemployment steady at 3.9 percent. Economists have long tended to view a four percent jobless rate as “full employment,” essentially the best that can be achieved in a capitalist system without spurring inflation. Our current unemployment level is among the lowest in the G-20 industrialized countries.

The reason is so simple that even a wingnut can understand: Under this president, the United States has seen an unsurpassed record of job creation, with 14 million new positions since he took office, far more than the last three Republican presidents combined. The social impact of high employment is profound, which is why traditional Democrats like Biden consistently promote infrastructure, education, environmental, and income support policies that boost jobs. As California Democratic Gov. Gavin Newsom explained during this week’s Fox News debate with Republican Gov. Ron DeSantis (whom he crushed), the nation is now seeing the lowest rate of poverty in our history, as employment among Blacks, Hispanics, and women have reached new peaks.

Are you starting to see a fuller picture here? Let’s add a few more features: Personal income rose over five percent in the first quarter of this year and contined to go up into the second and third quarters. Consumer spending rose 3.6 percent, while housing investment increased to 6.2 percent, almost half again what had been predicted.

You may well retort that polling consistently shows – and the media persistently emphasize – that most Americans say they are unhappy with the economy and blame the president, resulting in poor approval ratings and endangering Biden’s reelection prospects. And that’s undeniably true, as far as it goes. But more than one expert now wonders why, if so many of our neighbors feel pessimistic and even angry, they keep buying stuff as if everything is working out just fine.

Economist Dean Baker suspects the influence of slanted news coverage and can imagine a very different political scenario. “If we had the exact same economy, and Donald Trump was in the White House,” Baker says,”Trump would be endlessly saying ‘greatest economy ever.’ Every Republican politician in the country would be amplifying the claim and all the political pundits would be writing that the strong economy will make Trump almost a sure bet for re-election.”

Sooner or later, the majority of Americans will wake up and realize that Joe Biden has not only protected us from recession but has created the conditions for a generation of prosperity. Let’s hope they figure that out before it is too late – and vote to defend the future from Trump’s madness.

Shop our Store

Headlines

Editor's Blog

Trending

World