Tag: trump economy
Donald Trump

Two Years On, We Can See What Trump Has Done To The U.S. Economy

As we approach the two-year mark since Donald Trump’s second election victory, it’s a good time to do a little economic scorekeeping. Before getting into where the economy is and where it’s going, it’s worth a little reminder of where it was before the election.

This is important because Trump and the Republicans continuously spew utter nonsense about an economic disaster that only exists in their imagination. By literally every standard measure, the economy was doing extremely well just before the election. The unemployment rate was hovering near 4.0 percent and nominal wages were growing at roughly a 4.0 percent annual rate.

Inflation had slowed sharply, with the year-over-year rate at 2.6 percent in October of 2024. This translated into real wage growth of close to 1.5 percent. Inflation was expected to continue to slow, with most projections having inflation coming in very close to the Fed’s 2.0 percent target by the end of 2025.

There had been a massive surge in the number of people able to work from home as a result of the pandemic, with that figure still being close to 20% by the end of 2024. These people were saving hundreds of hours a year in commuting time and thousands of dollars annually in commuting-related costs. There also had been an unprecedented explosion in factory construction, with real spending in 2024 more than double the pre-pandemic level in 2019.

Growth for the year was 2.5 percent, and it was expected to be above 2.0 percent for the near future. This story was the basis for The Economist’s famous cover story about the U.S. economy: The Envy of the World.

Trump Takes Over: The Story Darkens

Virtually without exception, the data have gotten worse under Trump. Inflation has risen; nominal wage growth has slowed. Factory construction has plummeted. The trade deficit, which he views as a central measure of economic failings, has soared. Interest rates have risen, and the United States has fallen far behind the world in the green transition. China’s production of wind and solar energy exceeds our total production of energy. People have lost health insurance coverage, and costs are soaring for those who still have it.

The economy has become almost completely dependent on the AI bubble, as most other forms of investment are being crowded out. With real wages falling and job growth slowing to a trickle due to mass deportations, consumption growth is almost entirely dependent on stock price appreciation, which is in turn almost entirely driven by AI stocks.

This darkening picture began even before Trump took office. There was a huge surge in imports of durable goods like cars and TVs, starting right after the election. Consumers and businesses tried to buy ahead of Trump’s promised tariffs. Prices for durable goods, which had been falling through 2023 and 2024, began rising at the start of 2025. They rose further when Trump imposed the bulk of his tariffs in April. Instead of falling to 2.0 percent, inflation was 2.7 percent by the end of 2025, having hit 3.0 percent as a year-over-year rate in September.

Job growth fell sharply almost immediately after Trump took office, with the average monthly rate for his first year being just 27,000, down from an average of 103,000 for the last year of the Biden administration. Part of this slowing was due to the DOGE purge of federal government employees, but even pulling out the federal government, there was a slowing from 100,000 a month to 53,000. The main factors behind the slowing were the policy of mass deportation, which cut net immigration to near zero, and the tariffs, which both raised prices and led to enormous uncertainty.

The weakening of the labor market led to a sharp slowing in wage growth. While unemployment remained relatively low, workers became much less likely to switch jobs. Since job switching accounts for a disproportionate share of wage gains, the rate of nominal wage growth slowed sharply, from over 4.0 percent in 2024 to just 3.0 percent in the most recent data. With inflation accelerating to 3.5 percent, real wages are falling.

Growth Without Wage Growth

With job growth slowing to a trickle, roughly a 0.2 percent annual rate, and real wages falling, workers’ spending cannot drive consumption. While consumption is still growing at a healthy pace, it is clearly because of stock market gains. In the last three years, the market has risen by more than 80 percent, which translates into roughly $40 trillion in new stock wealth. The wealth effect on consumption is usually estimated as being close to three cents on a dollar. This means that the rise in stock wealth has added close to $1.2 trillion to annual consumption over the last three years, an amount equal to almost 4.0 percent of GDP.

This run-up was overwhelmingly an AI story. The value of AI-related companies has more than doubled over the last three years.

If AI has been driving consumption, its impact on investment has been even larger. Excluding data centers, investment in structures is down by almost 10 percent since the fourth quarter of 2024. Outside of information processing equipment, investment in equipment has been essentially flat under Trump. AI has also accounted for more than 80 percent of the investment in intellectual property products since 2024. In short, the story of investment growth under Trump is AI.

One of the ironies of the surge in spending on AI is that it has caused a sharp rise in the trade deficit. While there can be problems with a large trade deficit, such as the surge at the start of the century that cost millions of manufacturing jobs, the trade deficit had fallen back to roughly 3.0 percent of GDP when Trump took office, a level that can be easily sustained indefinitely.

The expectation of tariffs caused deficits to soar in the first quarter of 2025, but they then fell back to roughly their 2024 level after the tariffs were in effect. But they have been rising rapidly in recent months, passing $100 billion in August, due to a surge in computer chips and other AI-related items. This pace would put the trade deficit at over 4.0 percent of GDP.

Budget Deficits, Interest Rates, and Housing

At various points in his campaign, Trump promised that he was going to balance the budget or even pay off the debt. This isn’t happening. The deficit has increased under his watch, hitting $1,993 billion in fiscal 2026, up from $1775 billion in fiscal 2025. The biggest factors in this increase were a decline in corporate income taxes and higher interest payments on the debt. At more than 6.0% of GDP, the deficit is a record for a period when we are not in a war or recession.

It is worth mentioning that there have been cuts in spending that partially offset the tax cuts. While these are not large in terms of the total budget, they have had noticeable short-term effects and could have substantial long-term effects. On the short-term side, cuts to Medicaid and the ACA exchanges have led to an increase in the uninsured population. It rose by roughly 1 million from 2024 to 2025 and is virtually certain to rise considerably more in 2026 and beyond. Ending funding for the Africa AIDS program could lead to millions of preventable deaths in the years ahead.

The longer-term harm is likely to come from cuts to NIH funding and other federal research pools. In addition to the direct impact of the cuts, the arbitrary restrictions and politicization of grant awards, coupled with the harassment of leading research universities, have already sent many top researchers to other countries. As a result, they will likely be the primary beneficiaries of what otherwise would have been American innovations.

As noted, the higher deficit is partly due to higher interest rates, but the deficit does not seem to be the main cause of higher rates. Rather, the massive demand for capital to build data centers for AI is a much more important factor. In any case, long-term interest rates have risen sharply under Trump. The 10-year Treasury rate had been as low as 3.6 percent in September of 2024 and was heading downward. It turned around under Trump and now stands at almost 5.3 percent.

The high interest rates have weakened housing construction. It has averaged 1.35 million units a year. We probably need a construction rate of around 1.6-1.7 million units to have a noticeable impact in bringing house prices down. The rate was well over 1.7 million in 2022, before the Fed started raising rates.

The Future of the Economy is the Future of the AI Bubble

The Trump economy really does boil down to AI. If we believe the hype, we are about to see an incredible surge in productivity that will make us ridiculously wealthy. To date, there is no evidence to support this view. Productivity growth has been at best on its trend pace the last couple of years.

The stock market is priced as though we will see this massive AI payoff. As noted earlier, we saw a massive run-up in stock prices. Part of this is due to a rise in after-tax profits, as there has been a shift from wages to profits and a reduction in corporate income taxes. But the more important factor has been an increase in price-to-earnings ratios, with the market-wide average near the record levels hit in the tech bubble.

If we don’t see the massive gains in productivity promised by the AI enthusiasts, then we will almost certainly see a collapse in the stock market, with a serious recession almost guaranteed. On the other hand, if AI does have the promised payoff, all will be good, as long as the AI barons don’t steal all the money.

Dean Baker is a senior economist at the Center for Economic and Policy Research and the author of the 2016 book Rigged: How Globalization and the Rules of the Modern Economy Were Structured to Make the Rich Richer. Please consider subscribing to his Substack, from which this is reprinted with permission.

Unemployment Surges As Jobs Report Flops, But Trump Boasts Of 'Phenomenal Job'

Unemployment Surges As Jobs Report Flops, But Trump Boasts Of 'Phenomenal Job'

Just hours after President Donald Trump praised himself for supposedly doing a near-perfect job with the economy, the monthly jobs report was released—showing an increase in unemployment and fewer jobs than analysts had expected.

The Labor Department revealed Friday that the unemployment rate has risen to 4.2% and that only 29,000 jobs were added in September—a far cry from the 90,000 jobs that experts anticipated.

Jobs numbers were also revised downward for previous months.

During a rally in Texas Thursday night for failing Senate candidate Ken Paxton, Trump declared success on the economy.

“The only thing we’re doing badly at is public relations,” he said. “In other words, we’re doing a phenomenal job.”


Public opinion polling has consistently shown that voters blame Trump and the GOP for the bad economy. Since retaking office, Trump has put in place terrible policies like tariffs—which have increased prices—and launched a war in Iran—which has restricted the fuel supply, causing gas prices to surge.

But Trump argued at his rally, as he has in the past, that these concerns are fake and that the concept of affordability is simply made up by the left.

“Remember they came up with the word ‘affordability,’” Trump said. “They always come up with these words: ‘Affordability.’ So the fake news starts using it, because they’re partners with the Democrats.”


This is, of course, a completely false conspiracy theory.

Trump has spent most of his time as a public figure espousing a host of fake conspiracies, often with racist messages.

But despite his rhetoric, the location of Trump’s reality-defying speech probably says more about the precarious state of his political future than anything else.

Texas, one of the GOP’s most loyal states, is where his handpicked candidate Paxton has been flailing for months. Despite Trump’s comfortable wins in Texas in 2024, 2020, and 2016—as well as GOP dominance of the state for decades—Paxton is trailing Democratic candidate James Talarico.

That Texas is in play is a testament to how Trump’s poor economic performance is resonating with voters.

During his first term, Trump became the only president since the statistic has been recorded to see a net job loss. And in his second term, he has fulfilled the long-standing GOP tradition of underperforming on the economy.

Trump can pat himself on the back and pretend that affordability is made up all he wants. But the data paints a far more accurate picture—and that is what Americans are paying attention to.

Reprinted with permission from Daily Kos


Why Is Trump Still Boosting AI? Because He Has Nothing Except The Bubble

Why Is Trump Still Boosting AI? Because He Has Nothing Except The Bubble

Will AI transform the economy? The jury is still out on that one: So far there is little evidence for either the massive job losses or the soaring productivity growth industry leaders threatened/promised, but it’s still early days.

But AI does seem to be transforming U.S. politics. I can’t think of a technology that has inspired so much hate across such a wide political spectrum. Even the leading AI companies are warning about the dangers of their technology and pleading for government regulation to slow it down.

Which makes it more than puzzling that Donald Trump is going all in on AI, claiming that concerns about its dangers are a “hoax” and opposing any kind of regulation.

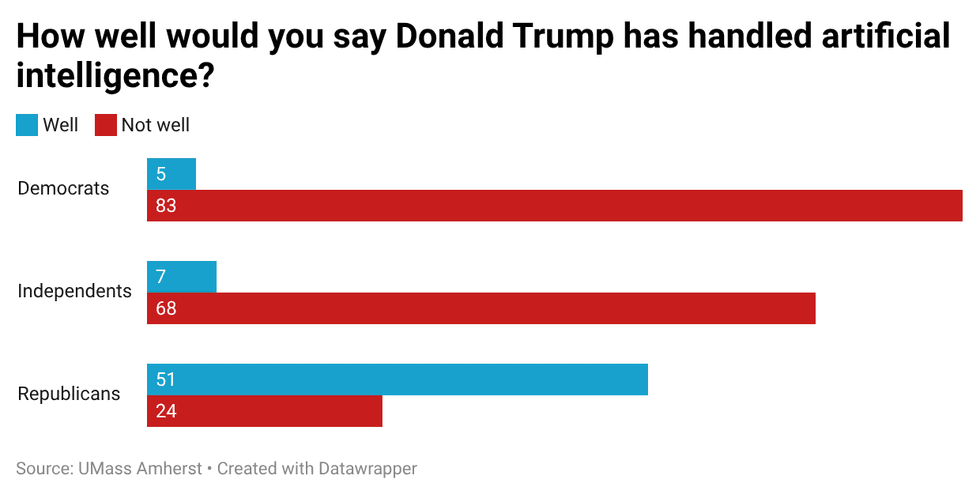
In so doing, he’s taking a wildly unpopular position. Here’s recent polling from UMass Amherst:

Notice that even a large part of Trump’s base is deserting him on this issue, with a quarter of Republicans disapproving.

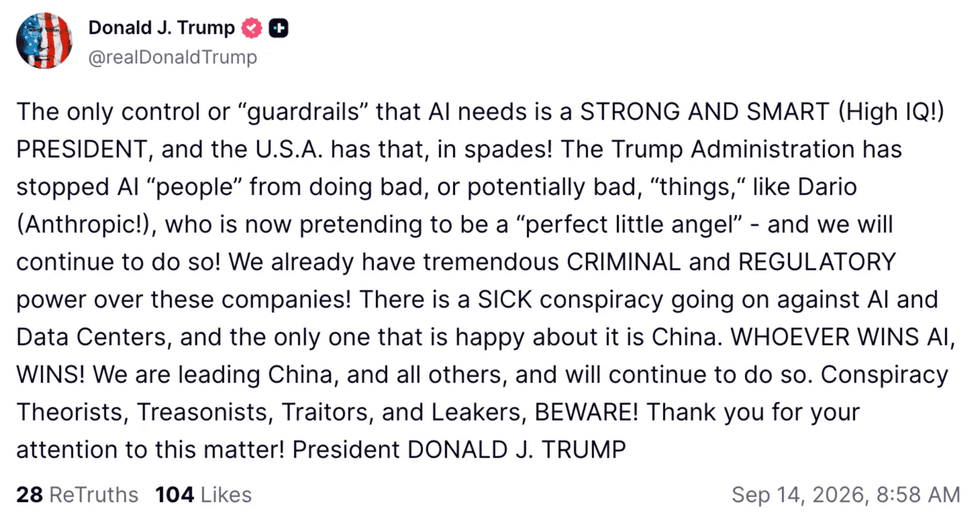
So why is Trump posting stuff like this?

Robert Reich has a good post on the subject, urging us to follow the money: As he notes, members of the Trump family have personal financial stakes in the industry. And one motive one should never, ever dismiss in current U.S. affairs is Trump’s personal greed.

I would, however, add two more points.

First, I think Reich is too glib in dismissing the idea that Trump imagines that he knows what he’s doing. “It can’t be,” Reich writes, “that he knows very much about AI.” But does he know that he doesn’t know? That Truth Social post above, in which Trump declares himself perfectly able to manage this wild new technology because he is a “STRONG AND SMART (High IQ!) PRESIDENT”, is like a textbook illustration of the Dunning-Kruger effect, in which incompetent people are highly confident in their own judgment because they’re too incompetent to realize that they’re incompetent.

Second, it’s important to realize how much Trump needs an AI boom.

Trump came into office believing that his tariffs would produce a huge boom in “manly” jobs. In fact, job growth has been weak — and more than all the job gains have gone to women. Meanwhile, tariffs have driven up consumer prices.

And then there’s the Iran war, which has been an economic as well as a strategic disaster. Diesel prices are now well above $6 a gallon. Trump officials love to say that gasoline was over $5 a gallon under Biden, which was true — for one week.

Yet one thing did seem to be going right under Trump II. Enthusiasm for AI was generating a huge investment boom and supporting stock prices. Trump officials, notably Scott Bessent, the Treasury Secretary — who Edward Luce of the Financial Times now dubs “the Pete Hegseth of the Treasury” (ouch) — had taken to claiming that AI will solve all their problems, ending inflation by reducing costs and curing the budget deficit by generating huge economic growth.

The backlash against AI, then, is taking away the one thing the Trumpists thought they had going for them. So in a way it’s understandable that Trump is trying desperately to hold on to the magic (and possibly endangering the future of humanity, but he doesn’t care about that.)

But of course it won’t work. The AI boom, once Trump’s last remaining political asset, is now a huge liability.

Paul Krugman is a Nobel Prize-winning economist and former professor at MIT and Princeton who now teaches at the City University of New York's Graduate Center. From 2000 to 2024, he wrote a column for The New York Times. Please consider subscribing to his Substack.

Reprinted with permission from Paul Krugman.

Wall Street Blaming Bessent And Warsh For Trump's Economic Chaos

Wall Street Blaming Bessent And Warsh For Trump's Economic Chaos

President Donald Trump's ongoing war on the Federal Reserve has been so persistent, it has started negatively impacting the economy. Now the economic editor of a conservative website is warning that Trump's economic policies are so erratic, two officials who otherwise were regarded as reliable are being met with unease on Wall Street.

"Within days of Mr. Bessent’s confirmation, at least, it was obvious this was a misjudgment," The Bulwark's economics editor Catherine Rampell wrote for The New York Times on Thursday. "One of his earliest actions as secretary was giving DOGE access to the sensitive Treasury payments system, which disburses some $6 trillion in payments annually. This was supposedly to investigate “fraud,” but it also was an attempt to help the Trump administration unilaterally freeze payments required by Congress. (A federal judge restricted DOGE’s access before this happened.)"

She added, "Soon after, Mr. Bessent also allowed the I.R.S. to share confidential tax data with immigration enforcement — undermining decades of work to convince immigrants that if they paid their taxes honestly, the payments wouldn’t be weaponized against them. (Federal judges have blocked that, too.)"

Rampell continued, "Now, after criticizing his predecessor for allegedly trying to juice the economy ahead of an election, Mr. Bessent appears to have attempted exactly that. Last week, he announced that the U.S. Treasury would ramp up repurchases of its long-term government bonds, a move intended to reduce their interest rates (which could in turn reduce the cost of mortgages and other financial products). Midterms are looming, and looser money tends to make for happier voters. Mr. Bessent’s plan backfired. Instead, after a brief dip, bond rates rose."

In short, the market realized that Bessent's plan would do nothing to address rising inflation, the dangerous national debt and the ongoing economic problems posed by AI.

"If anything, Mr. Bessent’s buyback play (announced along with comments insisting we can grow out way out of debt) only deepened those suspicions. It made Treasury leadership look feckless," Rampell wrote. She had similar reporting on how the markets are responding to Trump's Federal Reserve pick, Kevin Warsh.

"Mr. Warsh, like Mr. Bessent, has had a wobbly start to his tenure," Rampell wrote. "His most recent news conference was something of a disaster; Mr. Warsh either would not or could not articulate what the Fed’s plan was for tackling inflation, or why that plan did not appear to include interest rate increases. (Mr. Trump is demanding rates be lowered.) At one point Mr. Warsh seemed to suggest the Fed might switch its main yardstick for measuring inflation, raising concerns about backdoor attempts to soften the central bank’s commitment to reducing inflation."

She continued, "To make matters worse, Mr. Trump himself weighed in. He insisted that Mr. Warsh really truly wanted to reduce interest rates, but couldn’t because 'he’s got a board, and it’s a political board.' Days later Mr. Trump renewed his efforts to fire one of the members of that Fed board, which the Supreme Court had prevented him from doing. Markets were not happy about any of this."Rampell is not alone in her assessment of Warsh. Speaking with AlterNet earlier this week, an economic adviser to Presidents Bill Clinton and Barack Obama broke down the problems with Warsh.

"My own guess is that he'll wait until right before or right after the election to raise rates, because he doesn't set policy alone — interest rate policy is made by a committee at the Federal Reserve comprising the seven members of the Board plus five of the regional bank presidents, and there's increasing pressure among them to raise rates," Dr. Robert J. Shapiro explained. "They're letting him put it off a little while longer, but there's no good news on inflation. Just this week, Trump announced 50 percent tariffs on our largest trading partner, Canada, which will further increase inflation. The markets don't have much confidence in Warsh anymore, so they're pricing in a higher-than-normal likelihood that he'll cut rates — even though I don't think he will — and in anticipation of the inflation that would result, they're raising long-term rates."

Reprinted with permission from AlterNet

Shop our Store

Headlines

Editor's Blog

Trending

World