Tag: economic growth
What Even Our Smartest Economists Get Wrong About The Debt

What Even Our Smartest Economists Get Wrong About The Debt

The $40 trillion debt point naturally prompted much griping among pundits, many of whom see their job as promoting hysteria in order to justify cuts to Social Security, Medicare, and other popular social programs. As is clear to anyone not on the payroll of the rich and very rich, the debt is overwhelmingly the result of tax cuts, mostly to high earners, put in place by Presidents Reagan, Bush II, and Trump.

Unfortunately, confusion on the debt can spread even among the sane. Paul Krugman and Jared Bernstein, two top-notch economists (also friends) had a discussion of the debt in a podcast posted on Saturday. At one point, they noted that interest rates have risen, creating a situation where the interest rate is higher than the rate of growth, which could lead to explosive debt growing ever larger as a share of GDP.

That’s all straightforward arithmetic, but the confusion stems from the reason they see interest rates as going higher. Part of the reason is Trump’s craziness, which we all recognize undermines confidence in the economy and the debt. However, part of the reason is the investment boom from building AI data centers.

While I agree that this is a big factor in pushing rates higher, the assumption motivating this investment is that there will be some massive payoff in the form of higher profits stemming from huge gains in productivity. If these gains in productivity materialize, then we will be far richer than current projections show, and growth will have far surpassed interest rates. In other words, no explosive debt problem. Also, if we grow an extra 10-20 percentage points over the next decade, it seems a bit silly to be whining about debt, a point I will come back to.

There is also the possibility (likelihood in my view) that the productivity gains do not materialize. In that scenario, the AI-related stocks will crash at some point, the boom will bust, and we will likely be looking at a serious recession. In that world, our problem will be boosting the economy back to full employment, not the deficit. And for those who care about such things, interest rates should again be very low.

It seems this is a point that Paul and Jared should have brought into their deficit/debt discussion. I’ll give them a whack on the wrist for missing this point, but come to the more general issue that is usually lost in the tirades about gigantic debt.

Government Debt Is Not a Measure of Generational Equity

It is just atrociously bad economics to imagine the debt is some sort of measure of generational equity. At the most basic level, who owns the debt? The deficit hucksters talk like we send interest on the debt to people on another planet. In fact, the vast majority of the debt is held by U.S. citizens and U.S. corporations. We pay the debt to ourselves.

It’s true that ownership of the debt hugely skews upward, so the interest is mostly paid to higher-income people. But we can tax it back. In fact, let’s take an extreme case and say we tax back 100% of the interest.[1] In that case, is the debt a burden on future generations? We will of course not tax back 100% of the interest, but we can and should have progressive income taxes. Which, if they are actually collected, will mean that much of the money paid in interest will go right back to the government. And if we apply progressive taxes more generally, we can certainly offset any negative impact that interest payments on the debt have on income distribution.

And for trivia buffs, the rich people who will collect the interest in 30-40 years are part of future generations, the rich part. The story is again a class issue, not a generational one.

Growth and the Debt

Faster economic growth reduces the burden of the debt in the sense that it makes interest payments smaller relative to the size of the economy. But the more important point is that, in principle, faster growth makes us richer.

If the economy grows 10 percent more (in real terms) over a decade than had been expected (imagine AI actually pays off), then we would be roughly $3.9 trillion richer in 2036 than is now projected. Suppose in this story we had to pay another $500-$600 billion a year (again, in real terms) in interest compared to what we do today. Would we have done some injustice to our kids with a faster growth and higher debt story? The size of the economy is what will determine the well-being of our kids, not the amount of debt owed by the government.

But GDP growth is not everything, especially when it leads to destruction of our environment, as we are seeing now as a result of global warming. It would take some pretty batshit crazy accounting to be concerned about the debt we are passing on to our kids, but not about the environmental destruction we have caused by our use of fossil fuels.

And this is not just destruction of the lands where people like to be able to hike, fish, or hunt. It is also very much dollar-and-cents damage. The recent wildfires in Spokane are estimated to have caused over $1 billion in property damage. The damage done by the fires in Los Angeles last year may have been as high as $250 billion (0.8% of GDP). With global warming leading to more and bigger fires, as well as more frequent and severe hurricane and flooding events, we will be seriously damaging the life prospects of future generations even if we were to pay off the national debt tomorrow.

Trumpian Corruption

I know I have said this before, but the point deserves to be constantly thrown in the face of the deficit hawks: Trump’s corruption poses an infinitely greater threat to economic stability than the $40 trillion debt. Trump has been given a green light by the Roberts Supreme Court to corrupt every agency in the country (except the Fed) to enhance his power and his pocketbook. As we have seen, this means having the Justice Department and FBI focus on prosecuting his political opponents. It means selling antitrust rulings to campaign contributors. It means allowing political allies to sell unsafe food and likely drugs.

Trump has also had the Office of the Comptroller of the Currency greenlight his new crypto bank and had the Securities and Exchange Commission look the other way on his insider trading. He even ordered the Census Bureau to cook up a nonsense report on non-citizen voting to claim that, somehow, he actually won the 2020 presidential election that he lost in a landslide. (That’s the Trumpian usage of the word, where he says he won the 2024 election in a “landslide.”)

Anyhow, these are the sorts of things that happen in “shithole countries,” not advanced economies expecting the trust of investors. With Trump continually pressing his corruption further and his supporters in Congress saying it’s all good, investors should fear putting their money in the United States even if we had zero debt. That might be too difficult for the deficit hawks to understand, but most of us have parents who taught us not to do business with crooks.

[1] I know, no one would hold bonds if we taxed back all the interest, but I’m making a point. Trade economists have often assumed in their modeling that we replace tariffs with lump-sum taxes to show the benefits of trade. Unlike tariffs, lump-sum taxes don’t create economic distortions. Lump-sum taxes also don’t exist in the world, but trade economists felt it useful to assume them to make a point.
Federal Shutdown Drags On As Trump Shows Zero Interest In Ending It

Federal Shutdown Drags On As Trump Shows Zero Interest In Ending It

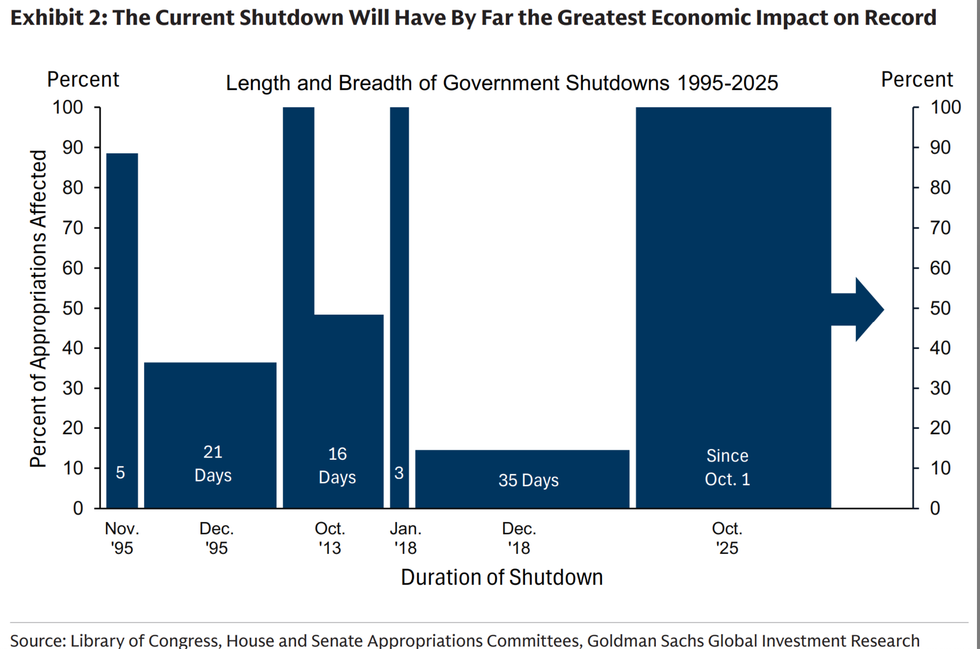
Come Wednesday, we’ll have a new record to celebrate: the longest government shutdown on record. The graph below, from Goldman Sachs Research, is particularly revealing, because the width of the bars show the length, while the height shows how much of the government was affected. The current episode is about to surpass the previous record—the 35 day shutdown in Trump’s first term, from December 18 -- January 19 — but that one affected a far smaller share of the government’s agencies.

It makes perfect sense that Trump would preside over the longest shutdowns, especially Trump 2, given the administration’s authoritarian aspirations, lack of internal opposition to the President’s instincts (less the case in Trump 1), and the false reality in which they cloak themselves, especially regarding the rule of budget law, as I wrote a few days ago.

The extent to which the administration desires to and believes they can legally ignore Congress when it comes to spending appropriations must not be underappreciated. It is a key building block in the monarchical agenda. Even the most compliant, spineless Congressional majority of our lifetimes is too much for the Trump administration to deal with, making shutdowns a welcome environment for them. It also makes this White House a deeply non-trustworthy counterparty in budget negotiations.

The problem Trump and company are facing is that they poorly understand and fully discount the things the government does, along with the extent to which tens of millions of Americans depend on those government services. That reality is starting to bite and it is likely to herald the beginning of the end of the shutdown.

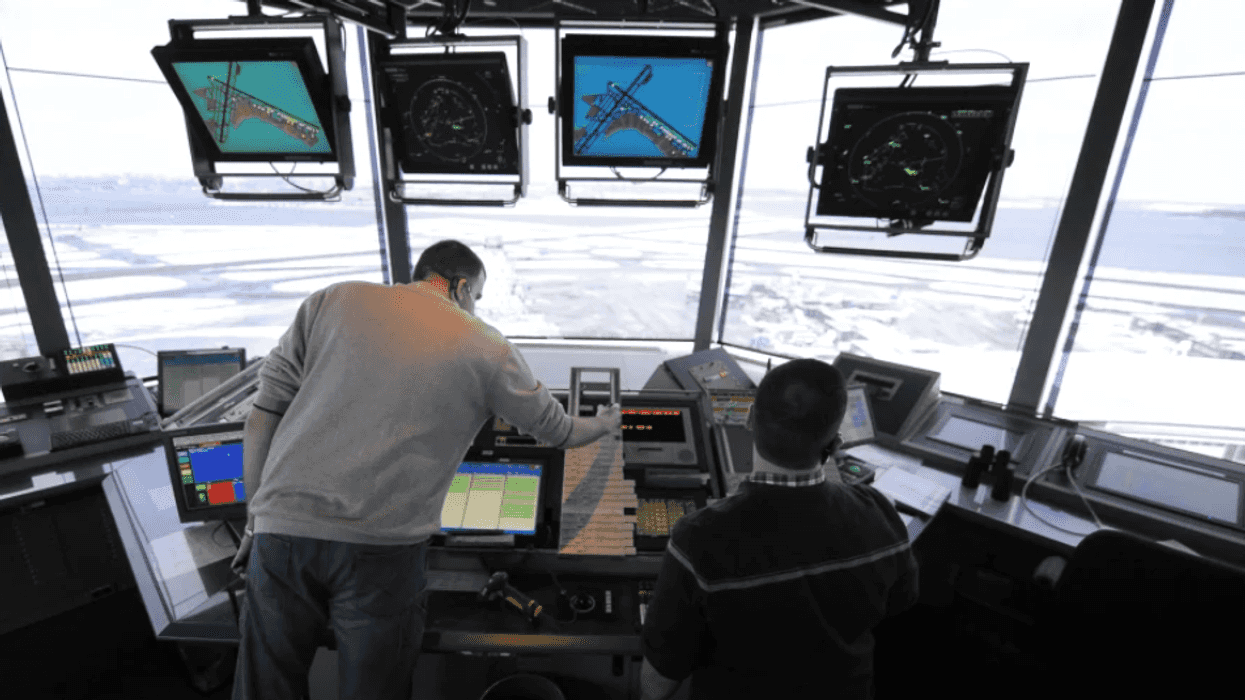
Recall that the last long shutdown ended the afternoon of the morning when the unpaid air-traffic controllers said “we’re done.” Well, “the government shutdown is straining US air travel, with air traffic controller shortages triggering hundreds of flight delays nationwide.” You can see the damage in the aptly named “misery map.”

Though the courts were unequivocal about the admin’s upside-down claim that they couldn’t use the SNAP contingency fund to pay SNAP benefits, there’s still going to be a disruption to nutritional support received by one in eight Americans, many of whom reside in Republican districts. It’s the same story, in terms of constituents, with the higher health care premiums that folks in the ACA exchanges are now officially learning about, an issue that Democrats have closely tied to the shutdown.

The fact that many hundreds-of-thousands of federal workers and contractors are not getting paid is one reason why GS researchers estimate that the current shutdown looks likely to have the greatest economic impact of any shutdown on record. They and others estimate that it will reduce annualized real GDP growth in the current quarter (Q4) but over one percentage point, to be made up in the next quarter.

If I’m right that these forces lead the shutdown to end, as is now expected in the next week or two, it raises at least two questions.

What will be the political fallout from the shutdown? My read of the polls is that most people blame the Republicans more than the Democrats for the shutdown. This is consistent with the fact that it’s usually the party in charge that takes the brunt of the blame. But there’s ample evidence that folks are unhappy with both sides.

Not a pollster, as I’m always quick to point out, but I believe the evidence shows that these shutdowns fade from the general public’s memory pretty quickly, though they leave a bad taste in your mouth. This one is different, however, in many ways, so perhaps it will have more lasting impact. My guess is its longer-term impact will depend on the fate of the ACA tax credits. If Republicans fail to extend them, it’s possible that a lot of people hurt by the increase will remember who was fighting to help them and who was busy bailing out Argentina instead.

What the heck was that all about? Especially given the economic bounce back noted above, why go through this? It’s like going on a starvation diet for six weeks followed by the same period of massive overeating. What’s the freakin’ point?!

The answer is there is no point. It’s the unavoidable consequence of the deep, partisan divide, which has only grown since Newt Gingrich got the bright idea of weaponizing appropriation expirations as a tool to elevate budget fights back in the mid-1990s.

To be clear, this is not a pox on both houses. The Democrats are and should be hard pressed to negotiate with Republicans who not only allow the Trumpies to break legally-binding spending deals, but applaud them for doing so. And the Democrats are right to use what leverage they have here to elevate the spike in healthcare premiums due to the expiration of the ACA premium credits.

It is also absolutely the case that Trump’s disinterest in any negotiation to end the shutdown has extended it. When I was in the Biden administration, we worked hard to prevent numerous pending shutdowns, and we were successful. That can be done, but it takes presidential commitment.

Of course, if a president views a shutdown as a way to further promote his kingliness, he’s going to be a lot less prone to help. As for the rest of us: “let them eat cake.”...

Jared Bernstein is a former chair of the White House Council of Economic Advisers under President Joe Biden. He is a senior fellow at the Council on Budget and Policy Priorities. Please consider subscribing to his Substack.

Reprinted with permission from Econjared.

Why Tariffs Trump Promised (But Didn't Deliver) Haven't Harmed U.S. Economy More

Why Tariffs Trump Promised (But Didn't Deliver) Haven't Harmed U.S. Economy More

A threatened tariff that is never implemented does not hurt the economy as much as a threatened tariff that is actually implemented. That simple point seems to have eluded Matthew Lynn, a financial columnist whose Washington Post column’s title told readers, “Economists were wrong about tariffs. They need to figure out why.”

While I agree that economists do tend to over-react to tariffs, and oversell the benefits of lowering them, the simple reason economists were wrong is that the tariffs Trump threatened on April 2, “Liberation Day,” were never implemented.

The tariffs Trump promised us on April 2 averaged well over 20 percent. The current nominal effective tariff rate is 17.9 percent, as calculated by the Yale Budget Lab. The reason for emphasizing “nominal” is that this is the rate we would be paying if companies actually paid the tariff rates Trump puts down on paper for a specific country and item. But the actual rate that companies end up paying is often much less than this.

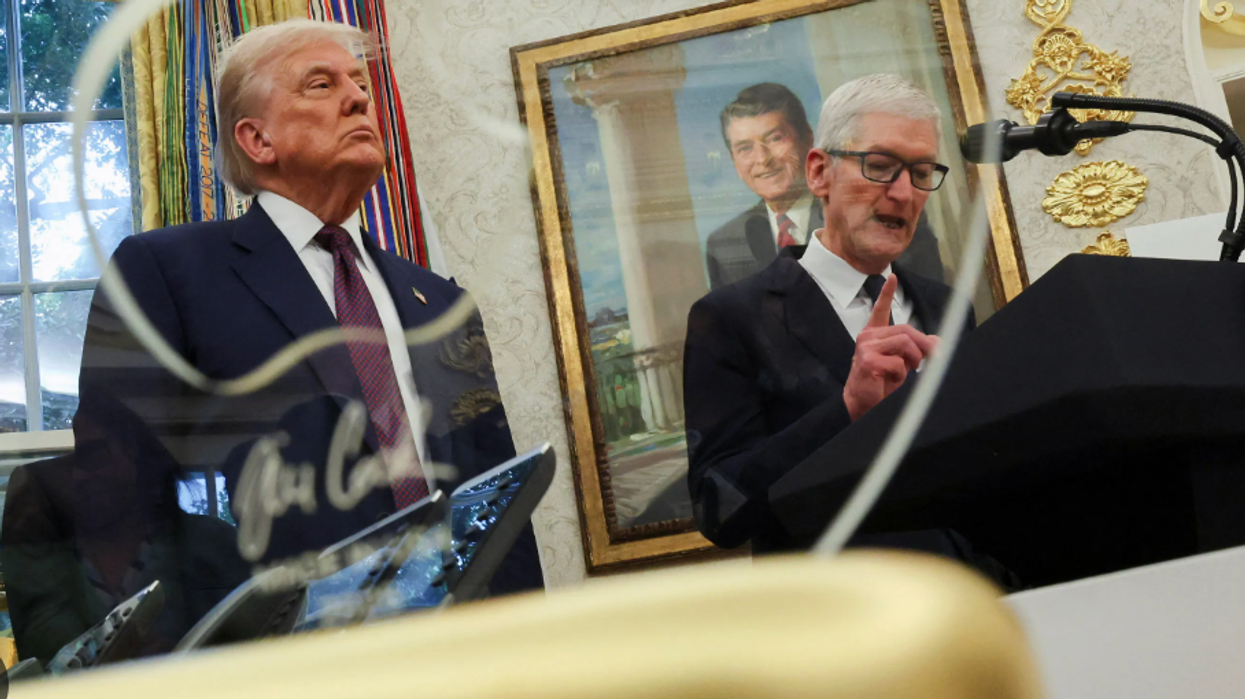
As Trump advertises, he likes to make deals. So, if CEOs head down to Mar-a-Lago bearing gifts, they can get lower tariff rates or even exemptions. Apple CEO Tim Cook led the way with his gift of a gold medallion to Trump on national TV. As a result, Apple is exempt from Trump’s 100 percent tariff on semi-conductors as well as his tariff on smartphones. With other companies (generally large companies) making similar deals, the effective tariff rate is far below the nominal rate.

We can easily calculate the effective tariff rate by looking at how much money the government is collecting in tariffs. According to the Treasury Department, it took in $30 billion in August, an increase of $23 billion from last August. Annualizing that gap, the increase in tariffs comes to $276 billion, an amount equal to about 8.5 percent of current goods imports. That is the actual increase in the tariff rate.

That will still be a hit to trade, but far less than the hit from the tariffs Trump advertised on April 2nd. If economists can be blamed in projecting out the impact of the April 2nd tariffs, it is for failing to recognize that Trump is a corrupt blowhard, and what he says on any given day has little to do with what he actually does. Hopefully, economists have learned their lesson here.

Of course, just because the tariffs ended up being far lower than advertised doesn’t mean they aren’t having a negative impact on the economy. Trump has hit the country with a massive tax increase, probably the largest ever seen. The increase is equal to 0.9 percent of GDP. Taking that over a 10-year budget horizon, as is generally done, it comes to $3.1 trillion. In other words, it’s real money.

And tariffs are taxes like any other tax. Donald Trump may think they have some mystical quality, but Donald Trump’s imagination doesn’t affect the economy. A tax increase of $276 billion pulls money out of consumers’ pockets and will slow the economy.

We are already seeing evidence of a weaker labor market, the unemployment rate had risen to 4.3 percent in August, up from 4.0 percent in January. (Trump won’t let us see the September jobs report, which was prepared before the shutdown.) This weakness will grow over time. Remember, many of these tariffs were originally delayed. Also, some tariff increases have the effect of pulling consumption forward, such as the ending of the de minimis exemption which led to a big surge in on-line sales in August. But there is no doubt that the tariffs are pulling money out of the economy and slowing growth, as economists predicted.

The other more important point about the harm tariffs do to the economy, as opposed to something like a sales tax, is that they are erratic, since Trump takes pride in changing them all the time. This both makes it difficult to make long-term investment plans and also enables businesses to get special privileges due to their bribes and access. This will hurt longer term growth since companies aren’t succeeding because they are innovative or efficient, but because they are friends with Donald Trump.

I suppose the Washington Post under its new leadership didn’t think it could make this point on its opinion page, but that is the reality.

Dean Baker is a senior economist at the Center for Economic and Policy Research and the author of the 2016 book Rigged: How Globalization and the Rules of the Modern Economy Were Structured to Make the Rich Richer. Please consider subscribing to his Substack.

Reprinted with permission from Dean Baker.

Why Corporate Economists Predict Recession -- And May Well Be Wrong

Why Corporate Economists Predict Recession -- And May Well Be Wrong

Be cautious about recession predictions.

After consulting their models of the American economy, many political naysayers and Wall Street economists are shouting “A recession is coming! A recession is coming!”

Should we trust these projections, which dominate major news reports on the economy? Count me a skeptic, given what the economic performance data show and the conflicted interests of commercial economists.

More jobs and more pay are the opposite of what the word ‘recession’ implies: “a significant, widespread and prolonged downturn in economic activity.”

In a piece typical of news articles last week, CNN reported:

“Former Federal Reserve Chairman Alan Greenspan believes a US recession is the ‘most likely outcome’ of the Fed’s aggressive rate hike regime meant to curb inflation. He joins a growing chorus of economists predicting imminent economic downturn.”

Then, without attribution, CNN added, “His views are particularly important” because he was Fed chair from 1987 to 2007 under Presidents Reagan, Clinton, and both Bushes.

Unmentioned by CNN and others: Greenspan couldn’t foresee the mortgage market collapse that led to the Great Recession in late 2007, the worst economic downturn since the Great Depression.

That’s amazing because Greenspan, now 96, cultivated an image as a clear-eyed and profound student of economic statistics. So how did he miss years of economic red lights flashing that housing prices were headed for a collapse? It was so evident that I told my New York Times editors about the problem in 2003 and then twice found a way to write about it even though it was far beyond my beat covering taxes.

In weighing Greenspan’s prognostications, remember that Ayn “Love Is Immoral” Rand trusted him to be the executor of her estate. Greenspan adored the views of Rand, who taught that altruism is a vice, selfishness a virtue, and who wrote a novel glorifying a criminal who blows up a building because it offended his aesthetics.

Greenspan’s views are, technically and philosophically, on the fringe, yet he gets treated like a centrist.

Key Indicators

That said, how is our economy doing? Let’s examine some key indicators.

The economy added a healthy 233,000 jobs in December.

Employers created more than four and a half million jobs in 2022. That’s an average of 375,000 new jobs per month, almost twice the rate of jobs growth during the Trump Administration’s pre-pandemic years.

Indeed, 2022 was the second-best year ever for job growth. The best year was 2021, but much of that was due to our coming out of the worst of the pandemic, which Donald “inject bleach” Trump badly mismanaged, pushing the jobless rate to almost 15 percent. Most of those discharged performed manual work. People who do intellectual work mostly continued working.

For context, consider job growth under Barack Obama and Trump.

President George W. Bush’s laissez-faire banking policies produced the Great Recession, so we’ll ignore the economic results he bequeathed to Obama.Then, startingg in October 2010, when the economy turned around, Obama averaged 201,600 new jobs per month for six years.

Trump, before the pandemic, averaged just 191,100 jobs added. That’s five percent less per month than Obama and barely half of Biden’s 2022 monthly average.

Voluntarily Quitting

How about job quits? The level at which people voluntarily leave their job says a lot about expectations that they will or already have found new work, often at better pay or under better conditions. People who see a recession looming usually stay put, even in a job they hate.

Each month starting in July, more than four million workers quit their jobs voluntarily. The November quit rate was a robust 2.7 percent or 1 in 37 jobs, although that’s down from the three percent rate a year earlier.

Very Low Jobless Rate

How about unemployment? The jobless rate last month was 3.5 percent under the most widely used measure.

That’s the lowest recorded level of joblessness since World War II save the slightly lower 3.4 percent rate in May 1969 when Vietnam War and NASA spending were boosting the economy, and early Boomers were entering the job market en masse without driving up the jobless rate.

Trump’s average pre-pandemic jobless rate was 3.9 percent though he hit 3.5 percent for three months shortly before the Pandemic began in early 2020.

There is an alternative and broader measure of unemployment, known as U-6 or Bureau of Labor Statistics Table A-15.

The U-6 measure counts people working part-time because they can’t find full-time employment, or are only marginally part of the workforce, or have temporarily given up trying to find work. These marginal workers, whose economic lives are filled with stress and misery, are not central to whether the economy grows or shrinks, but their numbers tell a deeper story about job quality.

The U-6 rate was 6.5 percent in December, down from 7.3 percent a year earlier. However, that doesn’t seem to suggest that a recession is at hand.

Inflation Abating

How about rising prices? While inflation is about 7.1 percent above a year ago, that isn’t the story of the last half year.

Month-over-month inflation peaked at 1.3 percent in June. Then it dropped to zero in July and 0.1 percent in August. Inflation rose to 0.4 percent in September and October. It fell back to 0.1 percent in November. The December numbers should come out around January 13.

Inflation may be whipped, although it could roar back. But for now, its withering

The decent inflationary trend appears to have grown from the pandemic when demand for goods and services fell sharply, and global supply chain problems bedeviled businesses from toy sellers to carmakers. Remember all those acres of parking lots with shiny new cars and trucks that could not be sold until computer chips arrived from Asia? And those shipping containers piled high in ports awaiting trucks to haul them away?

Those bottlenecks have been eliminated or considerably eased through White House efforts to improve coordination and cooperation between merchant sailors, stevedores, teamsters, local port, truck, and railroad managers, and the companies that employ them all.

Still, high energy and food prices continue to bedevil most Americans. Fossil fuels are a major component in food prices. It takes lots of fuel to make fertilizers to grow crops, machines to plant and harvest them, and trucks to berry foodstuffs to grocery stores nationwide.

Overall Economic Growth

How about economic growth measured by Gross Domestic Product or GDP?

There was a lot of ill-informed talk of a recession last summer because GDP was slightly negative for the year’s first half.

But the National Bureau of Economic Research’s Business Economic Cycle Dating Committee, which calls economic contractions and expansions, didn’t call it a recession, partly because the number of jobs kept growing, as did incomes. More jobs and more pay are the opposite of what the word recession implies: “a significant, widespread, and prolonged downturn in economic activity.”

We don’t have the full 2022 data yet, but the federal Bureau of Economic Analysis shows overall economic growth, not contraction in the first nine months of 2022.

By the way, Trump’s economy was slowly sinking before the pandemic, as DCReport advised readers in October 2020.

Pump Price Plummets

And what of inflation, much in the news this year?

The best news is that the national average price of gasoline has plummeted from a high of $5.11 in early June to $3.77 recently. That’s $1.34 less per gallon, a stunning 26 percent decline, not that it made much of a splash on front pages and broadcast news programs.

The sharp drop in the price of gasoline came despite Vladimir Putin’s February invasion of Ukraine which disrupted worldwide oil and grain markets and may yet lead to mass starvation in Syria and parts of North Africa that rely on Ukrainian wheat. The Biden Administration imposed severe price caps on Russian oil via shipping insurance. At the same time, the president released 180 million barrels of oil from the American Strategic Petroleum Reserve to help knock down prices at the pump.

That 180 million barrels is roughly how much oil America burns every ten days, but as is often the case in economics small changes in supply or demand can prompt big changes in price, as our coverage of electrify market manipulations has shown.

Because the Democratic Biden Administration sold oil at about $89 a barrel and will buy replacement oil at about $70 a barrel, the government is expected to turn a profit of more than $3 billion on actions that sharply lowered gasoline prices. Talk about win-win government economic policies.

An inflationary threat that may emerge is tied to rising sales of what two decades ago were called Osama Wagons—gas-guzzling trucks and SUVs that help sustain Middle East dictatorships.

Trade Deficit Shrinks

Trade numbers are also improving under Biden Administration policies, although there was a brief and severe rise in the trade deficit months ago.

During Trump’s first 23 months in office his disastrous and mismanaged trade war with China played a key role in the monthly trade deficit ballooning by 26 percent, federal Bureau of Economic Analysis data show.

The trade deficit, or surplus, comes in two parts. The first and larger measures the value of goods we buy from overseas versus what we sell to foreigners. The second measure is business services we buy from foreigners or sell them.

Our perennial surplus of exported services slightly offsets a perennial and much larger deficit in goods. President Biden has made cutting reliance on overseas manufacturers—especially for computer chips and other high-value, high-tech products—a top priority.

As of November, the deficit is down 3.6 percent compared to when Biden took office two years ago.

Mortgages and Paychecks

Another good sign, and a longer-term trend, is the falling share of personal income going to interest and principal payments on mortgages.

At the end of 2007, as the Great Recession began, Federal Reserve data showed 7.2 percent of personal income went to mortgage principal and interest. Now it’s less than four percent, with a slight uptick last year as the Federal Reserve under Chairman Jerome Powell, a Trump appointee, raised the interest rates it controls.

Americans owe about $12 Trillion in mortgage debt, down almost a fifth since the start of the Great Recession once inflation is considered.

So why do so many people feel so much economic pain?

The median weekly wage—half earn more, half less—is the same now as at the end of 2019 after taking inflation into account.

So why is the median not moving much?

Because a rapidly growing share of wages and salaries goes to executives and others paid more than $1 million per year while rank-and-file workers mostly lack unions and thus lack bargaining power.

Million Dollar Paychecks

In 2020 an eye-popping 82% of all pay raises went to the very thin and well-compensated slice of workers making $1 million or more.

That fell to 29% in 2021. However, the million-and-up club enjoyed average raises of $840,000 each while full-time workers making up to $250,000 got only $1,600. That’s a ratio of $500 to $1.

Also in 2021, the poorest-paid 60 million workers collectively made less than the best-paid 237,000, more than 500 of whom averaged about $151 million, my annual analysis of Social Security Administration payroll data shows.

The million-dollar and up pay club now collects almost seven percent of all wages and salaries, up from two percent in inflation-adjusted data from 1991. The number of these high-paid workers has exploded from 191 in 1991 to 237,000 three decades later in 2021. Last year the number of million-dollar-plus jobs grew 95 times faster than jobs overall.

Recession Risks

So, are we likely to fall into a recession, as Greenspan and many Wall Street economists warn?

The honest answer is we don’t know. As Yankees catcher Yogi Berra said, “it’s tough to make predictions, especially about the future.”

If the Fed raises interest rates too high or too fast, it could so discourage executives and entrepreneurs that they go on a capital strike, halting the new investment that is crucial to job creation. Then again higher interest rates may also draw more capital into the United States, further strengthening the dollar against other currencies.

When the dollar is high relative to other currencies, it makes what we import cheap, while other countries are burdened with high prices to purchase our goods and services.

The greenback has been riding very high for the past two years. My wife and I vacationed in New Zealand (beautiful, fascinating, and friendly) this fall. Our greenbacks were worth $1.78 against the Kiwi dollar. In Australia, the exchange rate was above $1.60. The story is similar worldwide.

My view on the chance of a recession: bringing back jobs from Taiwan and China, especially microchips and related high-tech manufacturing, will be a long-term boon to the American economy with some immediate effects.

If Biden succeeds in his goal of making America the go-to country for high-quality, high-tech manufacturing the American economic future will be bright. It will also enrich investors more than workers unless the union movement or a proxy for it becomes a major player in economic decision-making.

And as for the policies of the Fed?

It’s independent so you can’t do anything about how its regional governors vote on interest rates and whether money is hard or easy. But the notion that a recession is certain or even likely seems out there, at least for now.

Reprinted with permission from DC Report.

Shop our Store

Headlines

Editor's Blog

Trending

World