Tag: inflation
Donald Trump

Two Years On, We Can See What Trump Has Done To The U.S. Economy

As we approach the two-year mark since Donald Trump’s second election victory, it’s a good time to do a little economic scorekeeping. Before getting into where the economy is and where it’s going, it’s worth a little reminder of where it was before the election.

This is important because Trump and the Republicans continuously spew utter nonsense about an economic disaster that only exists in their imagination. By literally every standard measure, the economy was doing extremely well just before the election. The unemployment rate was hovering near 4.0 percent and nominal wages were growing at roughly a 4.0 percent annual rate.

Inflation had slowed sharply, with the year-over-year rate at 2.6 percent in October of 2024. This translated into real wage growth of close to 1.5 percent. Inflation was expected to continue to slow, with most projections having inflation coming in very close to the Fed’s 2.0 percent target by the end of 2025.

There had been a massive surge in the number of people able to work from home as a result of the pandemic, with that figure still being close to 20% by the end of 2024. These people were saving hundreds of hours a year in commuting time and thousands of dollars annually in commuting-related costs. There also had been an unprecedented explosion in factory construction, with real spending in 2024 more than double the pre-pandemic level in 2019.

Growth for the year was 2.5 percent, and it was expected to be above 2.0 percent for the near future. This story was the basis for The Economist’s famous cover story about the U.S. economy: The Envy of the World.

Trump Takes Over: The Story Darkens

Virtually without exception, the data have gotten worse under Trump. Inflation has risen; nominal wage growth has slowed. Factory construction has plummeted. The trade deficit, which he views as a central measure of economic failings, has soared. Interest rates have risen, and the United States has fallen far behind the world in the green transition. China’s production of wind and solar energy exceeds our total production of energy. People have lost health insurance coverage, and costs are soaring for those who still have it.

The economy has become almost completely dependent on the AI bubble, as most other forms of investment are being crowded out. With real wages falling and job growth slowing to a trickle due to mass deportations, consumption growth is almost entirely dependent on stock price appreciation, which is in turn almost entirely driven by AI stocks.

This darkening picture began even before Trump took office. There was a huge surge in imports of durable goods like cars and TVs, starting right after the election. Consumers and businesses tried to buy ahead of Trump’s promised tariffs. Prices for durable goods, which had been falling through 2023 and 2024, began rising at the start of 2025. They rose further when Trump imposed the bulk of his tariffs in April. Instead of falling to 2.0 percent, inflation was 2.7 percent by the end of 2025, having hit 3.0 percent as a year-over-year rate in September.

Job growth fell sharply almost immediately after Trump took office, with the average monthly rate for his first year being just 27,000, down from an average of 103,000 for the last year of the Biden administration. Part of this slowing was due to the DOGE purge of federal government employees, but even pulling out the federal government, there was a slowing from 100,000 a month to 53,000. The main factors behind the slowing were the policy of mass deportation, which cut net immigration to near zero, and the tariffs, which both raised prices and led to enormous uncertainty.

The weakening of the labor market led to a sharp slowing in wage growth. While unemployment remained relatively low, workers became much less likely to switch jobs. Since job switching accounts for a disproportionate share of wage gains, the rate of nominal wage growth slowed sharply, from over 4.0 percent in 2024 to just 3.0 percent in the most recent data. With inflation accelerating to 3.5 percent, real wages are falling.

Growth Without Wage Growth

With job growth slowing to a trickle, roughly a 0.2 percent annual rate, and real wages falling, workers’ spending cannot drive consumption. While consumption is still growing at a healthy pace, it is clearly because of stock market gains. In the last three years, the market has risen by more than 80 percent, which translates into roughly $40 trillion in new stock wealth. The wealth effect on consumption is usually estimated as being close to three cents on a dollar. This means that the rise in stock wealth has added close to $1.2 trillion to annual consumption over the last three years, an amount equal to almost 4.0 percent of GDP.

This run-up was overwhelmingly an AI story. The value of AI-related companies has more than doubled over the last three years.

If AI has been driving consumption, its impact on investment has been even larger. Excluding data centers, investment in structures is down by almost 10 percent since the fourth quarter of 2024. Outside of information processing equipment, investment in equipment has been essentially flat under Trump. AI has also accounted for more than 80 percent of the investment in intellectual property products since 2024. In short, the story of investment growth under Trump is AI.

One of the ironies of the surge in spending on AI is that it has caused a sharp rise in the trade deficit. While there can be problems with a large trade deficit, such as the surge at the start of the century that cost millions of manufacturing jobs, the trade deficit had fallen back to roughly 3.0 percent of GDP when Trump took office, a level that can be easily sustained indefinitely.

The expectation of tariffs caused deficits to soar in the first quarter of 2025, but they then fell back to roughly their 2024 level after the tariffs were in effect. But they have been rising rapidly in recent months, passing $100 billion in August, due to a surge in computer chips and other AI-related items. This pace would put the trade deficit at over 4.0 percent of GDP.

Budget Deficits, Interest Rates, and Housing

At various points in his campaign, Trump promised that he was going to balance the budget or even pay off the debt. This isn’t happening. The deficit has increased under his watch, hitting $1,993 billion in fiscal 2026, up from $1775 billion in fiscal 2025. The biggest factors in this increase were a decline in corporate income taxes and higher interest payments on the debt. At more than 6.0% of GDP, the deficit is a record for a period when we are not in a war or recession.

It is worth mentioning that there have been cuts in spending that partially offset the tax cuts. While these are not large in terms of the total budget, they have had noticeable short-term effects and could have substantial long-term effects. On the short-term side, cuts to Medicaid and the ACA exchanges have led to an increase in the uninsured population. It rose by roughly 1 million from 2024 to 2025 and is virtually certain to rise considerably more in 2026 and beyond. Ending funding for the Africa AIDS program could lead to millions of preventable deaths in the years ahead.

The longer-term harm is likely to come from cuts to NIH funding and other federal research pools. In addition to the direct impact of the cuts, the arbitrary restrictions and politicization of grant awards, coupled with the harassment of leading research universities, have already sent many top researchers to other countries. As a result, they will likely be the primary beneficiaries of what otherwise would have been American innovations.

As noted, the higher deficit is partly due to higher interest rates, but the deficit does not seem to be the main cause of higher rates. Rather, the massive demand for capital to build data centers for AI is a much more important factor. In any case, long-term interest rates have risen sharply under Trump. The 10-year Treasury rate had been as low as 3.6 percent in September of 2024 and was heading downward. It turned around under Trump and now stands at almost 5.3 percent.

The high interest rates have weakened housing construction. It has averaged 1.35 million units a year. We probably need a construction rate of around 1.6-1.7 million units to have a noticeable impact in bringing house prices down. The rate was well over 1.7 million in 2022, before the Fed started raising rates.

The Future of the Economy is the Future of the AI Bubble

The Trump economy really does boil down to AI. If we believe the hype, we are about to see an incredible surge in productivity that will make us ridiculously wealthy. To date, there is no evidence to support this view. Productivity growth has been at best on its trend pace the last couple of years.

The stock market is priced as though we will see this massive AI payoff. As noted earlier, we saw a massive run-up in stock prices. Part of this is due to a rise in after-tax profits, as there has been a shift from wages to profits and a reduction in corporate income taxes. But the more important factor has been an increase in price-to-earnings ratios, with the market-wide average near the record levels hit in the tech bubble.

If we don’t see the massive gains in productivity promised by the AI enthusiasts, then we will almost certainly see a collapse in the stock market, with a serious recession almost guaranteed. On the other hand, if AI does have the promised payoff, all will be good, as long as the AI barons don’t steal all the money.

Dean Baker is a senior economist at the Center for Economic and Policy Research and the author of the 2016 book Rigged: How Globalization and the Rules of the Modern Economy Were Structured to Make the Rich Richer. Please consider subscribing to his Substack, from which this is reprinted with permission.
Kevin Warsh

Trump Adds His Newly Appointed Fed Chair To His (Long) Enemies List

I had intended to write on the Fed’s decision to raise rates, but I don’t have much to add to what I wrote last week. I do think inflation is high, and for the moment the labor market seems reasonably healthy. But I don’t see higher rates as being a useful way to combat inflation caused by tariffs and Trump’s war on Iran.

As I noted, there is no case for the sort of wage-price spiral we saw in the 1970s. Wage growth has actually slowed sharply over the last two years. Wages had been growing at over a 4.0 percent annual rate in 2023 and 2024. The year-over-year rate has fallen to 3.1 percent. The annualized rate, comparing the average for the last three months (June-August) with the prior three (March-May), is just 2.7 percent. And this comes as inflation has accelerated from just over 2.0 percent to more than 3.0 percent.

Given little risk of accelerating inflation, at least from excessive demand, there seems little point in pushing rates higher. The one qualification I would make to this assessment is that expectations of a rate hike had become so embedded, especially following Fed Chair Kevin Warsh’s comments at the annual Jackson Hole conference, that it is likely long-term rates would go up more if the Fed held rates unchanged than if they hiked. Given that situation, I guess I would have gone with the hike.

But the bigger news yesterday was President Trump’s response. For some time, Trump has been pushing a bizarre theory that because we have the hottest economy (we don’t), we should have the lowest interest rates. This makes no sense, because the normal practice is to lower rates when the economy is weak, and raise them when it’s strong.

Apart from Trump’s confusion on the economics, the bigger story was that he immediately added the Fed to his enemies list, saying the rate hike was part of a grand conspiracy to make him look bad. This is more than a bit incredible, first and foremost because Trump had just appointed Kevin Warsh as Fed chair this spring. Apparently, Trump believes that his pick has already turned on him and joined the enemy.

And it wasn’t just Warsh; the vote was unanimous. That means that all four of the people who Trump appointed to the Fed, including his previous pick as Fed chair, Jerome Powell, lined up against him.

This follows Trump’s loss at the Supreme Court on his plan to have the Postal Service screen voter lists for mail-in ballots in the November elections. In that case, all three of Trump’s picks to the Court lined up against him, upholding a stay from a lower court that prohibited Trump’s plan from going into effect.

Trump complained that the justices “are not the people I interviewed.” He said that the court was giving in to crazy liberal influence.

It’s not new that Trump sees anyone who disagrees with him as part of a conspiracy. He’s long accused judges on lower courts of conspiring to undermine his agenda. And Trump regularly accuses any reporter who writes a critical story or asks a tough question as being “fake news.” And when polls show his popularity falling, Trump denounces them as “fake polls.”

But it seems a step further that Trump says people that he appointed, in some cases recently, have now joined the grand anti-Trump conspiracy. If Trump were not the president of the United States, we could just see this as part of an over-the-top comedy. Unfortunately, we don’t have that option.

In fact, the revenge Trump is floating for the Fed’s rate hike is pretty scary. He suggested that he will simply stop trading with arbitrarily chosen countries with whom we have a trade deficit. Trump seems to have a theory whereby we are losing money with a country, if we run a trade deficit with them. This makes as much sense as saying I lose money every time I go to the grocery store and pay them for the food.

But Trump is a reality TV show star, not someone who has even the most basic understanding of economics. Shutting down trade with a major trading partner would be a further jolt to the high prices that people are already upset over. It’s pretty horrible economics and doesn’t sound like very good politics, but I guess it will make Donald Trump feel tough.

It’s not clear Trump has the authority to arbitrarily impose trade embargos on other countries. But if the Supreme Court follows its recent path with tariffs, it will let Trump impose his embargo and then maybe wait a year or so before deciding it’s unconstitutional.

That will be bad news for families paying higher prices and the countries that have to reorient their economies, but at least it should further convince those who are still unconvinced that our president is completely out of his gourd. Other countries need to plan economic and defense relationships that do not involve the United States. At this point, we are not a credible country.

Dean Baker is a senior economist at the Center for Economic and Policy Research and the author of the 2016 book Rigged: How Globalization and the Rules of the Modern Economy Were Structured to Make the Rich Richer. Please consider subscribing to his Substack, from which this is reprinted with permission.
Don't Expect Foreign Nations To Pay Trump's Tariffs (They're Still A Tax On You)

Don't Expect Foreign Nations To Pay Trump's Tariffs (They're Still A Tax On You)

As we all know, Donald Trump likes to play the tough guy. Unfortunately, he often does it in really foolish ways, and this time I’m not talking about his war against Iran.

I’m talking about Trump’s tariffs. From the way he talks, he seems to think that foreign countries are sending us checks equal to the tariffs he has imposed on U.S. imports from them. Donald Trump’s mind can be a scary place, so it’s not worth trying to tease out his thought process, except to point out that the idea that foreigners are sending us checks is absurd.

The tariffs are collected here when the goods show up at a customs office. The party paying the tariff most immediately is the importer. The importer could be a wholesaler who may resell it to a retail store, manufacturer, or other business. Or in many cases, it will be a larger retailer like Amazon or Walmart, who arrange for the imports directly.

Either way, it is someone at this end who is most immediately out the money for the tariff. Some of what they pay will be passed on to their customers. To some extent, they will be forced to eat the tariff and make lower profits. (The evidence is that most is passed on.) But in both cases, consumers or companies here are paying the tariff.

The only way that foreign countries would pay the tariff is if the price of the goods they export to the United States falls as a result of the tariff.

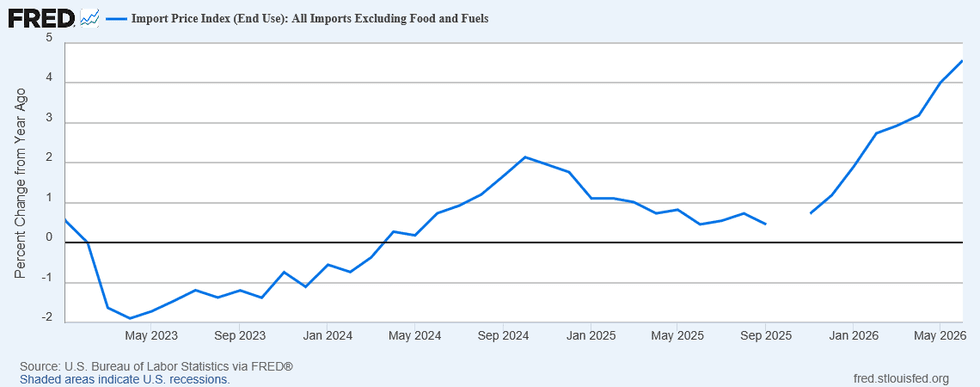
We got new evidence on that story on Friday, as the Bureau of Labor Statistics released data on import prices for June. The release showed non-fuel import prices were up 0.4 percent in June and 4.2 percent year-over-year (YOY).

Just to be clear on what these numbers mean, these are prices before any tariffs are applied. That means if the average tariff rate is 10%, then we are paying 14.2 percent more for our imports in June of 2026 than in June of 2025. That doesn’t look like a story where exporters are eating the tariffs.

It is worth noting that this is a change from past patterns. Import prices were actually falling in 2023 and rising slowly in 2024. There are a variety of factors affecting the price of producing goods elsewhere, including Trump’s war in Iran, but in any case, the story with import prices looks worse than before Trump took office, even before we consider the impact of the tariffs.

Looking across countries, it is hard to find evidence that anyone is eating Trump’s tariffs. The price of imports from the EU is up 3.7 percent YOY. The price of imported manufactured goods from Canada is up 10.3 percent. And the price of goods from China is up 1.3 percent.

While the story should have already been clear, the new data just further shore up the case. When Trump threatens countries with big tariffs, he is threatening the American people with big taxes.

This point should be made more clearly in reporting. For example, it is misleading to say that Trump is threatening to hit Brazil, Canada, or whoever with new tariffs. He is threatening to impose taxes on goods that Americans import from these countries. That would make it clear what is at stake.

We may never know, or care, what is in Trump’s head, but we have never seen a president who is so happy to raise people’s taxes.

Dean Baker is a senior economist at the Center for Economic and Policy Research and the author of the 2016 book Rigged: How Globalization and the Rules of the Modern Economy Were Structured to Make the Rich Richer. Please consider subscribing to his Substack.

Mainstream Media Still Doesn't Know What To Do With Trump's Big Lies

Mainstream Media Still Doesn't Know What To Do With Trump's Big Lies

A few days ago the Wall Street Journal published an oped by President Trump wherein he argued how great the US economy is on his watch and why tariffs are the main reason for that greatness. It’s a steaming mess of an argument, a firehose of falsehoods, though the one upside is that I haven’t seen it referenced anywhere. It sunk like a stone under the weight of its lies.

I won’t go through them here (though I’m about to link to a strong rebuttal), as it would be a waste of both of our times. Also, as you’d expect, it’s a greatest hits album with all the golden oldies he constantly blathers on about: inflation is zero (vs. 2.7 percent in the last CPI reading), prices are down, foreigners have invested “$18 trillion!” in America (that would be 60 percent of GDP; biz investment is currently 14 percent of GDP). The irony is that, as I’ve often stressed in these pages, the macro economy is, in fact, quite solid, even if the job market has worrisomely softened.

By far, the most potentially consequential macro development over the past few years is faster productivity growth. If that sticks—if we’re really, lastingly generating more output per hour of work—it means the US economy can grow faster without worrying about inflation picking up. Of course, there’s no guarantee that faster growth reaches working-class people in the form of higher wages, income, wealth; often, it has not. But those are all other discussions.

At any rate, I saw no reference to this hot mess until this morning, when a prominent newspaper ran a fulsome rebuttal to Trump’s claims. This new piece points out that solid research shows that, of course, tariffs have not been absorbed by exporters but passed through to American businesses and consumers, generating higher prices on those imports, hurting investment, and making production more, not less, expensive for our own manufactures, who have been aggressively shedding jobs (half of our imports are inputs into domestic production).

That prominent newspaper is the same Wall Street Journal that published Trump’s oped.

What should one make of this? How is one supposed to process the fact that the media publishes, without criticism or an accompanying fact check, a cascade of outright lies, only to rebut it a few days later? What does that say about our collective understanding of reality? And what should the WSJ have done in this case?

If you’re a newspaper with an oped page, and the President gives you an oped, you can argue that such a piece is de facto newsworthy. As the Journal editors themselves said in their rebuttal, “We thought we owed him the opportunity after our criticism of his tariffs.”

But unless his argument is fact-based and substantive, that’s ridiculous. The WSJ’s criticism of Trump’s tariffs has been wholly fact-driven—they’re consistently done great work on this, and I say that as someone whose ideology differs sharply from that of this ed board. If they say 2+2=4, nobody, not even the president, gets to pushback with 2+2=5.

I give them some credit for coming back with “no, it’s 4.” But that doesn’t fix what’s broken here.

I had a similar complaint about the New York Times' recent big-deal interview with Trump in the Oval. You can listen to the recording. They ask a question. He lies. They move on to the next question.

The only way to understand this is as performance art. It’s not a discussion about reality, facts, how policies play out in the real world. It’s a game, wherein Trump describes his alt reality and the media prints it because he’s the president and his reality matters. Which is true. It matters a lot and it’s one of the main reasons we’re in the mess we’re in. Never before has a president and his whole operation been so detached from reality, to the point wherein we see horrific things with our own eyes and they immediately say “no, that’s not what happened.”

But this is not benign, cute, or harmless. It’s not “oh, there he goes again! Whaddya gonna do? He’s the POTUS! You’ve got to run it.” It’s not just another flavor of our intense partisanship. It’s corrosive at best and fatal to democracy at worst. Allowing this false reality to fester has now been shown to be literally fatal to our fellow citizens.

I’m not a media expert, and I’m well aware that they’re in the business of selling news, and that clickbait = $ (though again, no one seemed to pick up on Trump’s op-ed). But there is no question in my mind that publishing falsehoods, even from the president—especially from the president—is not worth the money.

You may be thinking, “hey, it’s the op-ed page, not a column.” Well, I’ve written lots of op-eds and in every case, the editors insist that facts be verified. I’m not the president, but there’s absolutely no reason that the same rules shouldn’t apply.

Yes, of course, they have to cover him. But not like this.

Jared Bernstein is a former chair of the White House Council of Economic Advisers under President Joe Biden. He is a senior fellow at the Council on Budget and Policy Priorities. Please consider subscribing to his Substack.

Reprinted with permission from Econjared.

Shop our Store

Headlines

Editor's Blog

Trending

World