Tag: kevin warsh
Kevin Warsh

Trump Adds His Newly Appointed Fed Chair To His (Long) Enemies List

I had intended to write on the Fed’s decision to raise rates, but I don’t have much to add to what I wrote last week. I do think inflation is high, and for the moment the labor market seems reasonably healthy. But I don’t see higher rates as being a useful way to combat inflation caused by tariffs and Trump’s war on Iran.

As I noted, there is no case for the sort of wage-price spiral we saw in the 1970s. Wage growth has actually slowed sharply over the last two years. Wages had been growing at over a 4.0 percent annual rate in 2023 and 2024. The year-over-year rate has fallen to 3.1 percent. The annualized rate, comparing the average for the last three months (June-August) with the prior three (March-May), is just 2.7 percent. And this comes as inflation has accelerated from just over 2.0 percent to more than 3.0 percent.

Given little risk of accelerating inflation, at least from excessive demand, there seems little point in pushing rates higher. The one qualification I would make to this assessment is that expectations of a rate hike had become so embedded, especially following Fed Chair Kevin Warsh’s comments at the annual Jackson Hole conference, that it is likely long-term rates would go up more if the Fed held rates unchanged than if they hiked. Given that situation, I guess I would have gone with the hike.

But the bigger news yesterday was President Trump’s response. For some time, Trump has been pushing a bizarre theory that because we have the hottest economy (we don’t), we should have the lowest interest rates. This makes no sense, because the normal practice is to lower rates when the economy is weak, and raise them when it’s strong.

Apart from Trump’s confusion on the economics, the bigger story was that he immediately added the Fed to his enemies list, saying the rate hike was part of a grand conspiracy to make him look bad. This is more than a bit incredible, first and foremost because Trump had just appointed Kevin Warsh as Fed chair this spring. Apparently, Trump believes that his pick has already turned on him and joined the enemy.

And it wasn’t just Warsh; the vote was unanimous. That means that all four of the people who Trump appointed to the Fed, including his previous pick as Fed chair, Jerome Powell, lined up against him.

This follows Trump’s loss at the Supreme Court on his plan to have the Postal Service screen voter lists for mail-in ballots in the November elections. In that case, all three of Trump’s picks to the Court lined up against him, upholding a stay from a lower court that prohibited Trump’s plan from going into effect.

Trump complained that the justices “are not the people I interviewed.” He said that the court was giving in to crazy liberal influence.

It’s not new that Trump sees anyone who disagrees with him as part of a conspiracy. He’s long accused judges on lower courts of conspiring to undermine his agenda. And Trump regularly accuses any reporter who writes a critical story or asks a tough question as being “fake news.” And when polls show his popularity falling, Trump denounces them as “fake polls.”

But it seems a step further that Trump says people that he appointed, in some cases recently, have now joined the grand anti-Trump conspiracy. If Trump were not the president of the United States, we could just see this as part of an over-the-top comedy. Unfortunately, we don’t have that option.

In fact, the revenge Trump is floating for the Fed’s rate hike is pretty scary. He suggested that he will simply stop trading with arbitrarily chosen countries with whom we have a trade deficit. Trump seems to have a theory whereby we are losing money with a country, if we run a trade deficit with them. This makes as much sense as saying I lose money every time I go to the grocery store and pay them for the food.

But Trump is a reality TV show star, not someone who has even the most basic understanding of economics. Shutting down trade with a major trading partner would be a further jolt to the high prices that people are already upset over. It’s pretty horrible economics and doesn’t sound like very good politics, but I guess it will make Donald Trump feel tough.

It’s not clear Trump has the authority to arbitrarily impose trade embargos on other countries. But if the Supreme Court follows its recent path with tariffs, it will let Trump impose his embargo and then maybe wait a year or so before deciding it’s unconstitutional.

That will be bad news for families paying higher prices and the countries that have to reorient their economies, but at least it should further convince those who are still unconvinced that our president is completely out of his gourd. Other countries need to plan economic and defense relationships that do not involve the United States. At this point, we are not a credible country.

Dean Baker is a senior economist at the Center for Economic and Policy Research and the author of the 2016 book Rigged: How Globalization and the Rules of the Modern Economy Were Structured to Make the Rich Richer. Please consider subscribing to his Substack, from which this is reprinted with permission.
Wall Street Blaming Bessent And Warsh For Trump's Economic Chaos

Wall Street Blaming Bessent And Warsh For Trump's Economic Chaos

President Donald Trump's ongoing war on the Federal Reserve has been so persistent, it has started negatively impacting the economy. Now the economic editor of a conservative website is warning that Trump's economic policies are so erratic, two officials who otherwise were regarded as reliable are being met with unease on Wall Street.

"Within days of Mr. Bessent’s confirmation, at least, it was obvious this was a misjudgment," The Bulwark's economics editor Catherine Rampell wrote for The New York Times on Thursday. "One of his earliest actions as secretary was giving DOGE access to the sensitive Treasury payments system, which disburses some $6 trillion in payments annually. This was supposedly to investigate “fraud,” but it also was an attempt to help the Trump administration unilaterally freeze payments required by Congress. (A federal judge restricted DOGE’s access before this happened.)"

She added, "Soon after, Mr. Bessent also allowed the I.R.S. to share confidential tax data with immigration enforcement — undermining decades of work to convince immigrants that if they paid their taxes honestly, the payments wouldn’t be weaponized against them. (Federal judges have blocked that, too.)"

Rampell continued, "Now, after criticizing his predecessor for allegedly trying to juice the economy ahead of an election, Mr. Bessent appears to have attempted exactly that. Last week, he announced that the U.S. Treasury would ramp up repurchases of its long-term government bonds, a move intended to reduce their interest rates (which could in turn reduce the cost of mortgages and other financial products). Midterms are looming, and looser money tends to make for happier voters. Mr. Bessent’s plan backfired. Instead, after a brief dip, bond rates rose."

In short, the market realized that Bessent's plan would do nothing to address rising inflation, the dangerous national debt and the ongoing economic problems posed by AI.

"If anything, Mr. Bessent’s buyback play (announced along with comments insisting we can grow out way out of debt) only deepened those suspicions. It made Treasury leadership look feckless," Rampell wrote. She had similar reporting on how the markets are responding to Trump's Federal Reserve pick, Kevin Warsh.

"Mr. Warsh, like Mr. Bessent, has had a wobbly start to his tenure," Rampell wrote. "His most recent news conference was something of a disaster; Mr. Warsh either would not or could not articulate what the Fed’s plan was for tackling inflation, or why that plan did not appear to include interest rate increases. (Mr. Trump is demanding rates be lowered.) At one point Mr. Warsh seemed to suggest the Fed might switch its main yardstick for measuring inflation, raising concerns about backdoor attempts to soften the central bank’s commitment to reducing inflation."

She continued, "To make matters worse, Mr. Trump himself weighed in. He insisted that Mr. Warsh really truly wanted to reduce interest rates, but couldn’t because 'he’s got a board, and it’s a political board.' Days later Mr. Trump renewed his efforts to fire one of the members of that Fed board, which the Supreme Court had prevented him from doing. Markets were not happy about any of this."Rampell is not alone in her assessment of Warsh. Speaking with AlterNet earlier this week, an economic adviser to Presidents Bill Clinton and Barack Obama broke down the problems with Warsh.

"My own guess is that he'll wait until right before or right after the election to raise rates, because he doesn't set policy alone — interest rate policy is made by a committee at the Federal Reserve comprising the seven members of the Board plus five of the regional bank presidents, and there's increasing pressure among them to raise rates," Dr. Robert J. Shapiro explained. "They're letting him put it off a little while longer, but there's no good news on inflation. Just this week, Trump announced 50 percent tariffs on our largest trading partner, Canada, which will further increase inflation. The markets don't have much confidence in Warsh anymore, so they're pricing in a higher-than-normal likelihood that he'll cut rates — even though I don't think he will — and in anticipation of the inflation that would result, they're raising long-term rates."

Reprinted with permission from AlterNet

Behind Tomorrow's Federal Reserve Decision, A Delicate Economic Balancing Act

Behind Tomorrow's Federal Reserve Decision, A Delicate Economic Balancing Act

They just keep comin.’

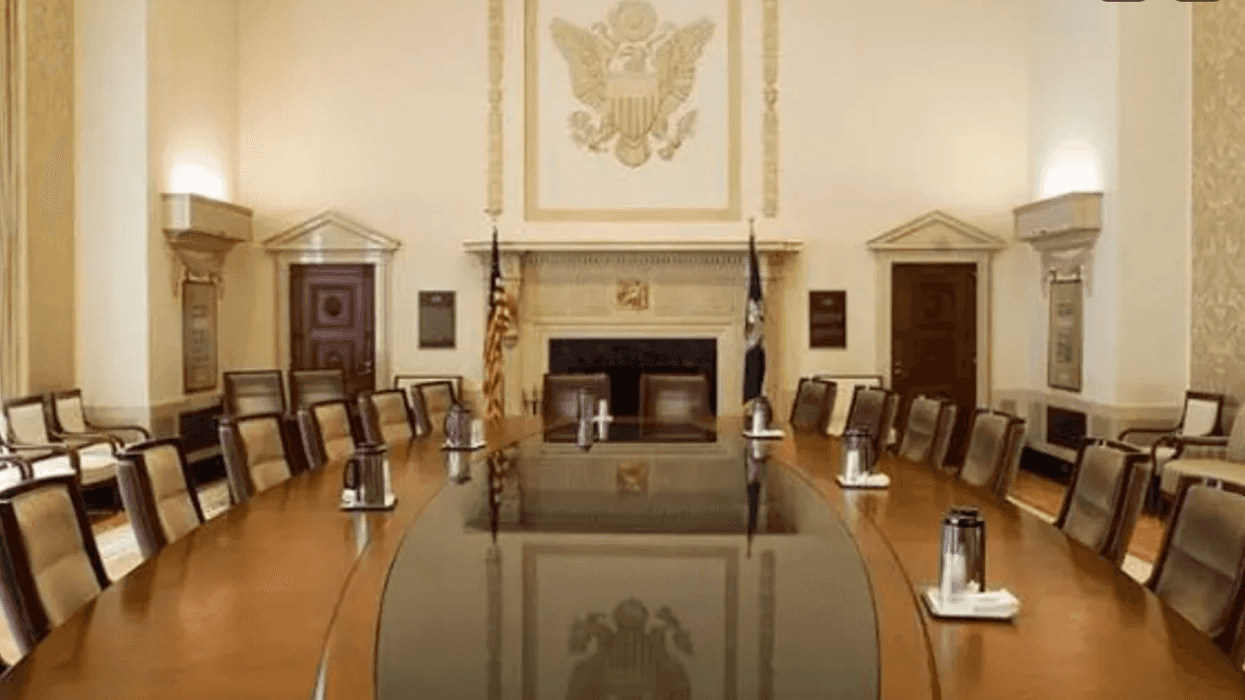
I’m talking about those FOMC (Federal Open Market Committee) meetings that take place about every six weeks in the big boardroom at the Federal Reserve’s headquarters in Washington, D.C.

The committee is meeting as we speak, and will announce their rate decision tomorrow at 2pm ET, as per usual, followed by a presser with Chair Warsh, his second since he was confirmed. Given Warsh’s campaign to do a lot less telegraphing about how the Fed is assessing the economy and the monetary policy path, there was some question as to whether Warsh would keep these every-meeting pressers going. But, at least for now, he’ll evade answer questions from the press tomorrow at 2:30.

(Note to the chair: You’re not fooling me, Kevin! Your strategy, which I grant you is clever, is to be so opaque and elusive at these pressers that the reporters give up and the markets tune out. FTR, that could work! Though it does leave a lot of investors scratching their heads in ways that seem sub-optimal to me, as I stress below.)

The big question, given inflation’s persistence above target, is will the FOMC come off of neutral and raise the interest rate they control. As I write, the market probability of a 25bps hike is 36%, up 10 ppts from a week ago.

In this brief note, I’d like to talk about the macroeconomics of the Fed’s balancing act right now, as we are in a somewhat weird macro/monetary moment. I wouldn’t call it stagnation—slow growth with high inflation—because growth is pretty good. Expectations for Q2 GDP, out later this week, are tracking around 2% (though GDPNow is at 1.6%). Job growth has picked up lately, and is probably a bit above breakeven (the number needed to keep unemployment stable). Wage growth, at around 3.5%, nominal, is a bit low relative to productivity, meaning no inflationary pressure there.

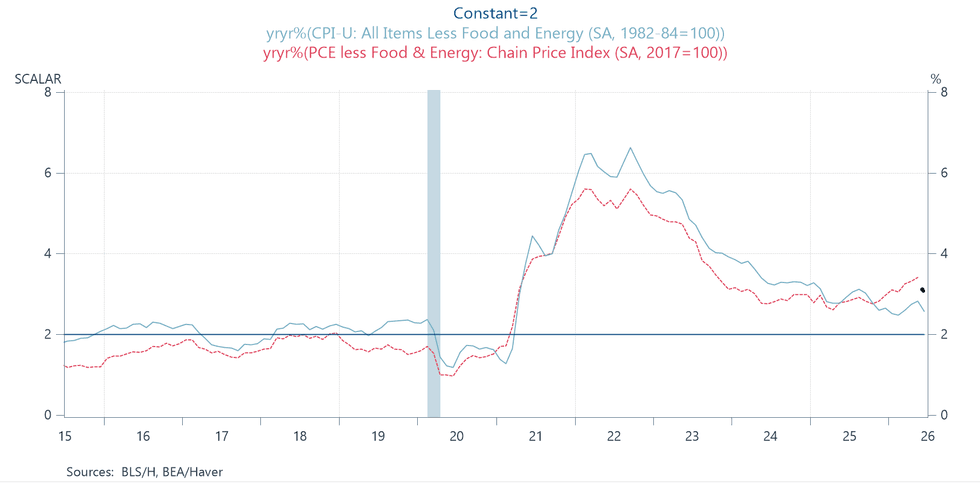
In other words, no macro overheating, yet inflation remains elevated. The figure below shows core CPI and core PCE, with a dot for the latter’s June value (also coming later this week), expected to come in at ~3%, a point above target. And that’s before energy prices, which bleed a bit into the core, picked up this month as Trump’s Iran war heated up again.

This puts us in a familiar place, one I’ve personally lived through in the Biden years, with good but not overheated growth and high inflation, in this case—a stark difference with the sitch back in my day—due mostly not to exogenous shocks (pandemic-induced supply chain disruptions), but to Trump’s inflationary policies, including tariffs and the war (there’s also demand-side inflationary pressures from AI spending).

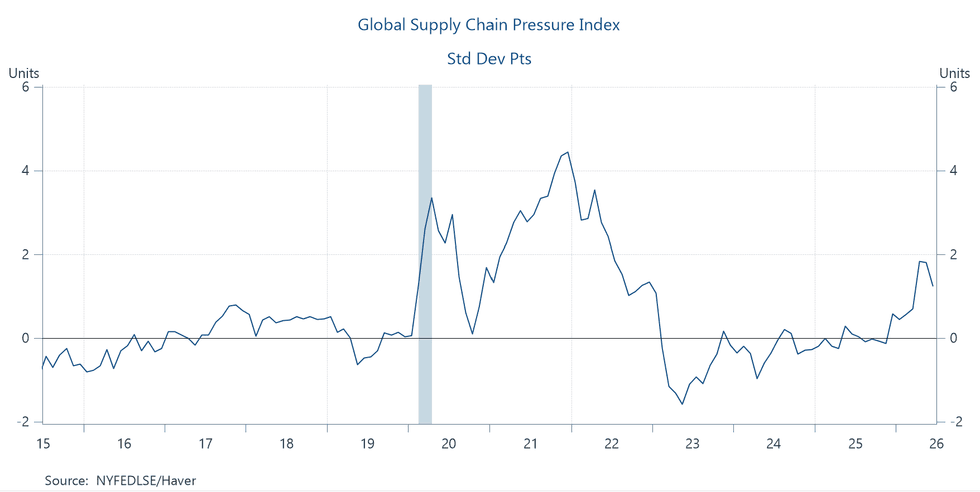
Of course, supply chains are not as battered now as they were then (see figure), but they’re clearly elevated. And isn’t the Fed supposed to “look through” that sort of thing? Doesn’t that militate against raising rates?


To an extent, yes, for two reasons. One is that such shocks tend to dissipate. Tariffs, like any tax, should give a one-time bump to the price level and then underlying inflation takes over. And the war could end. The problem with that thinking, however, is that it ignores the elephant Orange Menace in the room. Trump can’t let the tariffs rest anymore than he can extract us from his war of choice.

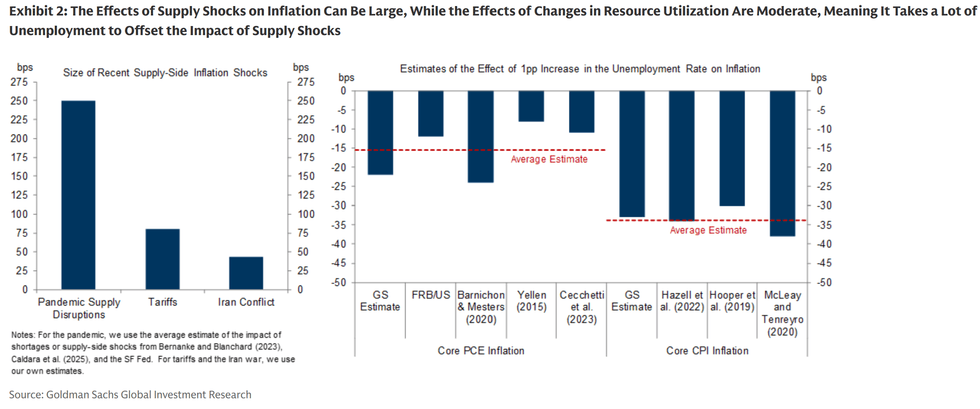
The second reason the Fed might be averse to hiking into mostly supply-shock driven inflation is that it takes too much damage to the economy’s demand side to blunt supply-side inflationary impacts. As GS recently put it: “…a key lesson of recent years is that the effects of supply shocks on inflation are often large, while the effects of changes in resource utilization [demand] are moderate.”

They cited a recent Yellen speech underscoring this point, and Janet knows a bit about this:

“Monetary policy cannot tame supply-driven inflation without exacting unacceptable unemployment costs.” Those steep costs, she added, lie behind the standard central bank wisdom that “Looking through supply shocks should remain the default strategy unless inflation expectations are at genuine risk of becoming unanchored.”

There are numbers to back up this thinking. Below you see GS’s basis-point impacts of supply shocks vs. demand shocks (a one ppt higher unemployment rate) on inflation. They’ve got the tariffs adding about 75bps and the war, about 40bps, so 1.15 ppts higher inflation. Then, on the right, they’ve got one point more unemployment reducing core PCE inflation by just 15bps, averaging over a few studies. Do the math and that’s far too much unemployment to offset Trump’s supply shocks.

But, my fellow Fed-watchers, the story does not end there. I put heavy weight on Janet’s caveat: “…unless inflation expectations are at genuine risk of becoming unanchored.”

If you’re on the FOMC, there’s no way you can be cavalier about that warning. Eyeball that first figure above and you’ll see that core inflation has exceeded the target for years. It’s fine, in specific, time-limited cases to call “supply-shock…nothing to see…move along folks.” But this isn’t that. David Mericle, GS’s Chief US economist put it exactly right in a recent podcast:

…they’re done litigating what exactly is causing inflation, asking the question of whether or not it’s appropriate to look through the different factors causing high inflation. If we continue to see high inflation, many of them feel like at this point we really need to respond to that because this has just gone on for too long, and I think everyone agrees that at some point, in principle, even if this is a long series of one-time supply shocks, it would become dangerous. It would risk making people a little bit too accustomed to high inflation and make it potentially take on a life of its own.

So, I don’t think they hike tomorrow, and based on the economic analysis above, I wouldn’t go there. But I would hope they lean into a hawkish bias in the statement. I additionally hope Warsh puts aside his man-of-mystery schtick and gives some version of the above analysis in his presser tomorrow.

RIP Alan Greenspan: Why New Fed Chair Warsh Shouldn't Imitate His Cryptic Style

RIP Alan Greenspan: Why New Fed Chair Warsh Shouldn't Imitate His Cryptic Style

I was not an Alan Greenspan fan, but I will give him some serious credit on his passing. I’ll also give him serious blame for missing two huge bubbles, the collapse of which gave us serious recessions. I’ll also add a comment about the opaque way he ran the Fed, to which I fear our new Fed chair is returning.

Starting with the positive, Greenspan allowed the unemployment rate to fall to 4.0% as a year-round average in 2000. This was huge. The prevailing view in the economics profession had been that the unemployment rate could not fall much below 6.0% without triggering spiraling inflation.

Greenspan was not a mainstream economist and therefore did not accept this view. In 1995, when the unemployment rate was already under 6.0%, he famously argued with two ostensibly more liberal Fed governors, Janet Yellen and Lawrence Meyer, over this point. They both wanted Greenspan to raise rates to head off inflation. Greenspan insisted that he didn’t see evidence of inflation and was not going to raise rates just because the unemployment rate was low.

Greenspan stood pat as the unemployment rate fell to 5.0% and then 4.5%, and finally in 2000 to 4.0% as a year-round average. We actually had several months of 3.9% and 3.8% unemployment. This allowed millions of workers to get jobs who would have otherwise remain unemployed if Yellen and Meyer had gotten their way.

Even more importantly, the low unemployment of the late 1990s gave tens of millions of workers the bargaining power to secure real wage gains. This was the first period of sustained real wage growth for low- and middle-wage earners since the early 1970s. The low unemployment of this period also set a benchmark for the future, where economists recognized that 6.0% unemployment was not a floor. (Yes, we can do better with a federal jobs policy, but that is not Alan Greenspan’s domain.)

Greenspan and the Bubbles

Greenspan decided to ignore the two huge bubbles that grew under his watch. He famously commented about the irrational exuberance in the stock market in 1996, which quickly sent stocks tumbling. Greenspan then mumbled some nonsense about growth possibly justifying market prices, and stocks recovered and continued to rise for another three and a half years.

The bubble began to deflate in March of 2000, and the market eventually lost close to half its value. The NASDAQ, where the major tech stocks were listed, lost almost 80%. The popular wisdom is that the resulting recession in 2001 was short and mild. This was not true from a labor market perspective. We went four full years without creating jobs and the strong real wage growth of the late 1990s quickly stopped and went into reverse.

The next bubble was even worse. There was already some evidence of a housing bubble in the late 1990s, as house sale prices began to outpace inflation. They also outpaced rents, which were still rising roughly in step with overall inflation.

This divergence increased in the 00s, triggered in part by low interest rates, but also incredibly lax lending standards. At their peak in 2006, house sale prices had risen 70% in real terms compared to where they were a decade before. The subsequent collapse gave us a financial crisis and the worst recession since the Great Depression, as the unemployment rate nearly reached 10.0%.

After the collapse all the people in economic policy positions gave themselves a “who could have known?” amnesty. The answer of course was everyone should have known. The dodgy lending practices of mortgage issuers were hardly a secret; they were bragging about it. People were buying houses with no money down and in many cases even borrowing more than the value of their home to cover moving expenses and closing costs. The same was true for the securitization that allowed issuers to offload any mortgages immediately after it was sold, regardless of the quality.

In an interview that Greenspan gave to the Washington Post after the crash, he commented that he had become concerned that the share of subprime mortgages had jumped to 25% in 2005. He said he couldn’t remember if he had passed this information on to his successor, Ben Bernanke, when he stepped down in 2006.

This was infuriating. The idea that the Fed chair was not aware of the explosion in subprime lending (even worse Alt-A, which had risen to 15%) was truly incredible. It’s not clear if it would be worse if Greenspan’s claim was true or not.

Remedies for Bubbles

I have written about this before, but I’ll just make a couple of points here. First, in the case of the stock bubble, I think talk would have gone a long way. Greenspan’s offhand “irrational exuberance” comment had a huge effect. Imagine he had the Fed churning out papers showing how stock prices were completely out of line with pretty much all projections of future GDP and profit growth.

The point is not that investors had to agree with Alan Greenspan, but they would have to answer him. The “who could have known?” defense might save a fund manager when it is just random gadflies yelling about a bubble. It is a very different story when a Fed chair is putting out the warning. A person managing tens of billions at a pension fund or endowment will be looking at the unemployment line if, after the crash, they say they didn’t pay Greenspan any attention.

In the case of the housing bubble, in addition to warnings, the Fed has substantial regulatory authority. The bad practices of banks and other financial institutions were easy to see. The Fed could have cracked down. Instead, they could not even be bothered to issue updated mortgage lending guidelines until after the crash.

Greenspan Thought the Fed Should be Opaque

This one is timely since our new Fed chair, Kevin Warsh, seems to want to turn back to the Greenspan era. Since I just wrote about this last week, I’ll pick up part of what I said.

“Under Alan Greenspan, the Fed was deliberately opaque. I remember walking to work one day in the mid-1990s, the day after Greenspan had given some big speech. Back then, we had newspaper boxes where you could buy the paper. I always glanced at the machines as I walked by. Half of the papers had headlines saying something to the effect of “Greenspan Plans to Raise Rates.” The headlines for the other half were something to the effect “Greenspan to Leave Rates Unchanged.”

“Greenspan, who followed his press closely, was reportedly delighted. He had given a major speech, and no one had any idea what he was talking about.

“Ben Bernanke, his immediate successor, wanted the Fed to be more transparent. He explicitly introduced the concept of “forward guidance” to Fed policy: the idea that the Fed would tell people where it expected interest rates to go in the near-term future. In their tenures as Fed chair, both Janet Yellen and Jerome Powell continued this policy. Their view was that they did not want the public to be surprised by the Fed’s decisions.”

I argued that this makes good sense both from the standpoint of the economy, being clear about Fed plans creates more certainty for investment decisions and is also important for reducing corruption. As I noted:

“Wayne Angell, who served as a Fed governor from 1986 to 1994, began consulting at the rate of $100 a minute (roughly $220 in today’s dollars) after he stepped down from his position in 1994. Angell may have been an insightful observer of the national economy, but he was obviously being paid for his knowledge of his former colleagues’ views on interest rates.

“If the Fed is fully transparent about its intentions, no one is going to get paid $220 a minute for their insights on what the FOMC is thinking. We don’t know how far Warsh will look to go with this move away from Fed transparency, but the further he goes the more room there is for corruption.”

Anyhow, Greenspan’s deliberate opaqueness was not a good policy for the Fed. We should hope that Kevin Warsh does not follow his example as chair.

Shop our Store

Headlines

Editor's Blog

Trending

World