Tag: trump inflation
wage growth v inflation chart

Trump Economy: July Inflation Index Shows Wages Fell Further Behind Prices

The Consumer Price Index rose 0.1 percent in July, with the core rate rising 0.2 percent. Over the year, the overall CPI is up 3.4 percent, while the core is up 2.5 percent.

As always, there are a few seeming anomalies. Prescription drug prices fell 0.8 percent in July and are down 3.1 percent over the last year. Nonetheless, people are spending about 2.0 percent more on drugs this year than last year. Computer prices jumped 3.5 percent in July. This is the data center story.

Rent and owners’ equivalent rent both rose 0.3 percent in July, somewhat faster than in prior months, but this is mostly due to rounding. Over the year, the indexes are up 2.9 percent and 3.2 percent, respectively. Food prices fell 0.1 percent in the month but are still up 2.7 percent year-over-year. Lettuce prices plunged 16.4 percent. Any ideas how that could have happened?

One real anomaly was a 0.3 percent drop in the car insurance index, leading to a year-over-year decline of 4.5 percent. This sort of drop is unprecedented outside of the pandemic. There were some modest declines in 1998 and 1999, but other than that, the index has always risen and typically far outpaced the rest of the CPI.

I have noted the falling car insurance index before and waited for it to turn around, but it has continued to be on a downward path since the start of the year. I’m betting for the insurance index to turn around and start rising again, but I have been making that same bet for many months. It accounts for 2.6 percent of the index, so it matters. It was a major contributor to inflation in 2022 and 2023 when there were double-digit increases.

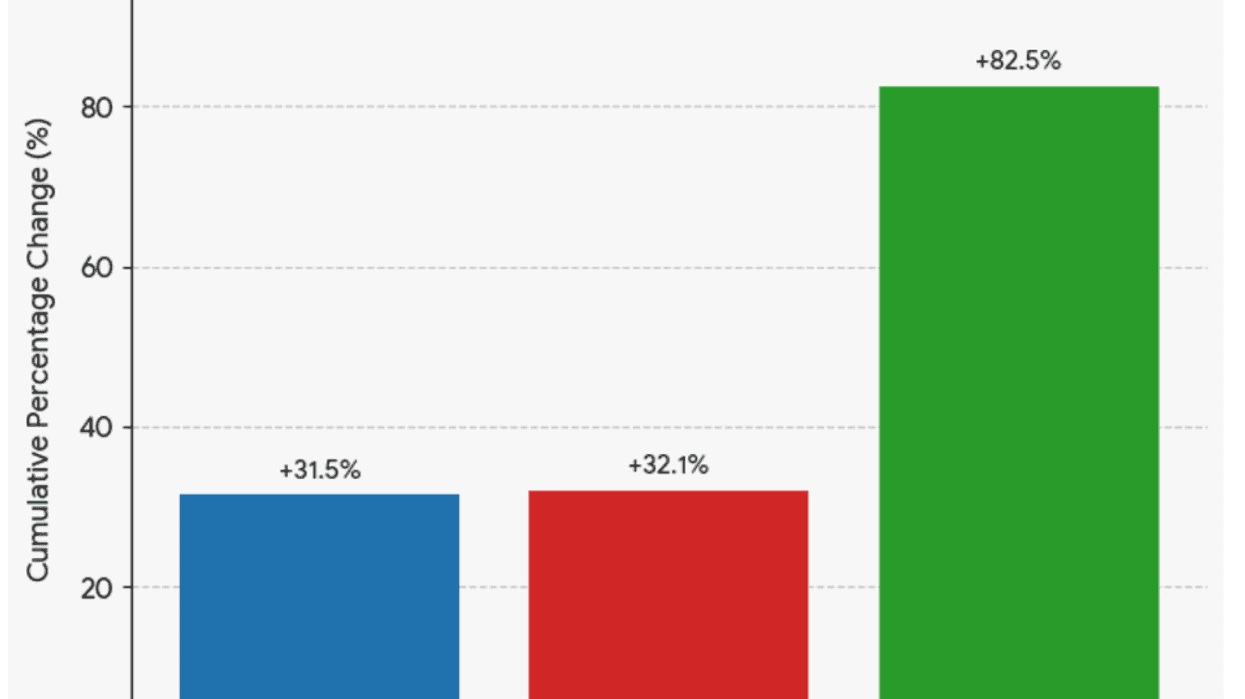
But stepping back from the specifics, this is a bad story for the economy. Inflation is not about to soar out of control, assuming Trump doesn’t do anything too crazy, but it is outpacing wages. Over the last year, the average hourly wage increased 3.2 percent. The annualized rate of increase over the last three months compared with the prior three was just 2.5 percent. This means that workers, who had already been feeling pressed, are falling further behind.

This is sort of good news from the standpoint of the Fed. It doesn’t have to worry about a wage-price spiral, but it does mean that we have an economy that will not be powered by workers’ consumption. With job growth having slowed to a crawl and real wages trending downward, workers will not have the means to increase consumption. This means that growth will be driven by AI investment and wealthy people spending based on stock gains and capital income. That does not look like a very solid basis for expansion.

Dean Baker is a senior economist at the Center for Economic and Policy Research and the author of the 2016 book Rigged: How Globalization and the Rules of the Modern Economy Were Structured to Make the Rich Richer. Please consider subscribing to his Substack.


Will Surging Tide Of Uninsured And Spiking Hospital Costs Trigger A Recession?

Will Surging Tide Of Uninsured And Spiking Hospital Costs Trigger A Recession?

All of the health care sector’s major economic indicators are headed in the wrong direction.

Major hospital chains last week began reporting a substantial rise in their uncompensated care costs after millions of people dropped health insurance. The Republican Party’s refusal to retain the Biden administration’s expansion of Affordable Care Act subsidies has already forced at least three million people into the ranks of the uninsured.

Meanwhile, the Centers for Medicare and Medicaid Services under Dr. Mehmet Oz announced Friday it will grant hospitals a 2.3 percent increase for their 2027 in-patient Medicare rates. That’s well below the general inflation rate (3.5 percent over the past 12 months) and a half percentage point behind the Bureau of Labor Statistics' measure of inflation in overall medical services (2.9 percent).

If you’re sitting in the chief financial officer’s seat at one of the nation’s hospitals, the next 12 months look bleak. Private insurers have already announced they will seek double-digit rate increases for individual and family plans sold on the exchanges later this year. Those rates are usually finalized in late October, just ahead of the start of open enrollment, which this year falls on the day before the mid-term election. Rate-shock will likely force millions more people to drop coverage.

Then there’s the One Big Ugly Bill’s imposition of work requirements in Medicaid, which will go into full effect next January (some states have already begun winnowing their roles). That’s expected to lead to nearly 12 million poor people losing coverage over the next few years, mostly due to eligible enrollees’ failure to leap over the bureaucratic hurdles established by the law.

The coming huge increase in the ranks of the uninsured — the first since passage of the Affordable Care Act in 2010 — is certain to raise the uninsured rate well into double digits. It reached an historic low of eight percent during the Biden years. The accompanying sharp rise in uncompensated care delivered by hospital emergency rooms and other providers will inevitably lead to major spikes in premium costs for employer-provided health plans, which covers an estimated 160 million workers and their family members.

A recent survey of major insurers’ actuaries found the cost of employer-based health insurance prices is expected to rise nine percent on average next year. That increase — more than two percentage points greater than this year and nearly twice the rate of economic growth — will sharply increase both employer premiums and their employees’ co-premiums, co-pays and deductibles.

Given the price pressure in other household necessities, many more workers will opt for high-deductible plans to hold down their out-of-pocket expenses. Some will decide to drop out of their employers’ plans. That’s a viable if risky option for the young and healthy, who use far less health care on average than older workers. But it’s a disaster for older, sicker employees and their families, who will see their premiums rise even faster than anticipated because the young and healthy have left the pool.

Labor costs are rising

Major health care institutions are no doubt formulating plans now for how to deal with their deteriorating financial position. Given that labor costs generally account for about half of all hospital spending, hiring freezes and job cuts will probably be on the agenda.

We’ll know more on Friday this week when the July jobs report comes out. There is a high likelihood that the central role that health care has played in U.S. job creation over the past decade, and especially in the past year, is coming to an end. Should that happen due to the sudden shock to the system from the soaring uninsured rate, it could prove devastating for the rest of the U.S. economy, where job growth has slowed dramatically this year due to the Trump regime’s tariffs, the war against Iran, and government job cuts.

The overall jobs numbers tell an interesting tale if we look at the past year and compare that to the past decade. Over the last ten years, the entire health care sector added 3.1 million new jobs. That was one in every five new jobs in the economy (roughly commensurate with a health care sector that makes up 18 percent of GDP). Hospitals alone accounted for 758,000 of those new jobs or just a shade under 25 percent of the total new health care jobs.

But in the past year, the overall economy added just 506,000 new jobs as manufacturing declined (so much for Trump’s claim he is bringing back goods-making industries). Overall service job growth couldn’t keep pace. Indeed, just one sector kept the unemployment rate from leaping into recessionary territory.

What sector was that? Health care, which added 437,000 new jobs over the past year, accounting for fully 86 percent of the new jobs total. Hospitals accounted for 118,000 or 27 percent of those new jobs.

The only way hospitals have been able to keep adding jobs is by using their market power to raise prices on the privately insured. According to the most recent Kaufman Hall National Hospital Flash Report (May), hospital expenses are up seven percent from a year ago while average patient days are down two percent.

The higher expenses are being driven mostly by the need to raise pay for physicians, nurses and support staff to keep pace with inflation, which is rising at one-and-a-half to two times the rate the Federal Reserve Bank considers optimal. Yet even with those price increases (which are angering everyone), hospital margins and profitability are shrinking compared to a year ago.

Given those numbers, there’s no way that hospitals or health care will be able to maintain its recent role as the U.S. economy’s main job generator. Given the Trump regime’s mismanagement of the rest of the economy, one can’t rule out the possibility that the emerging health care financing crisis will trigger a recession.

Merrill Goozner, the former editor of Modern Healthcare, writes about health care and politics at GoozNews.substack.com, where this column first appeared. Please consider subscribing to support his work.

Reprinted with permission from Gooz News

Will Surrendering To Iran Relieve Trump's Gas Pains? Alas, Probably Not!

Will Surrendering To Iran Relieve Trump's Gas Pains? Alas, Probably Not!

Donald Trump’s rhetoric on Iran oscillates wildly from day to day, sometimes from hour to hour. But Trump has run out of military options that don’t involve huge war crimes, so we seem to be heading for a reopening of the Strait of Hormuz on Iran’s terms. And that includes the imposition of de facto tolls, whatever they are called.

There is no mystery about Trump’s surrender: He’s desperate to end the war because he is paying a steep political price for high gasoline prices, and the midterms are only four and a half months away.

But can Trump rehabilitate his standing with American voters by throwing in the towel? Probably not, for both economic and political reasons. I would argue that there are four points of slippage between Trump’s political goals and what is likely to happen.

The state of the Strait: Even if the war is truly over, it will take time to return world oil supplies to normal levels. First, there has been substantial damage to the Persian Gulf’s infrastructure, which will take months, if not years, to repair. Second, many oil tankers are now in the wrong place and it will take weeks or months to move them. Third, some shipping channels are at risk from stray mines. Lastly, the world met the Hormuz crisis in part by running down oil inventories, which will now need to be rebuilt.

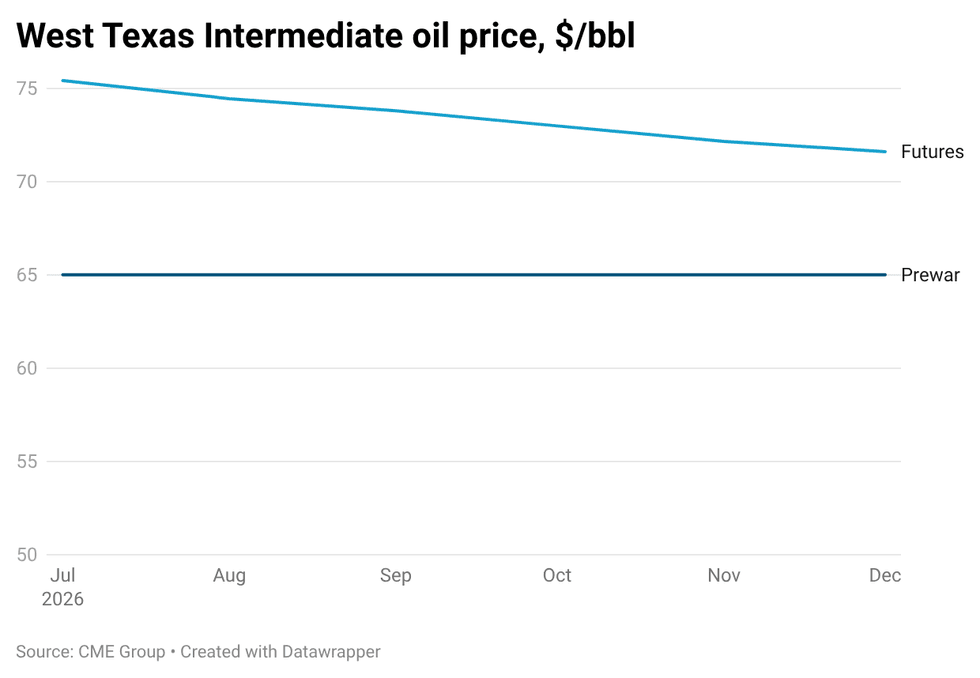
It’s true that a surge in Iranian oil exports has begun thanks to the lifting of the U.S. blockade. This will add to global oil supplies but will also strengthen the regime. But despite this surge of Iranian shipments, prices of oil futures — promises to buy or sell oil on specified dates — indicate that the oil markets expect oil prices to decline at only a slow rate for the rest of this year:

west texas intermediate oil price

Rockets and feathers: There is a well-documented pattern to how the price of gasoline responds to changes in the price of crude oil. When there is a global shock that causes the price of crude oil to soar, gasoline prices rise like a rocket. But when the crisis is over and crude prices plunge, the price of gas declines only gradually ­— it drifts down like feathers.

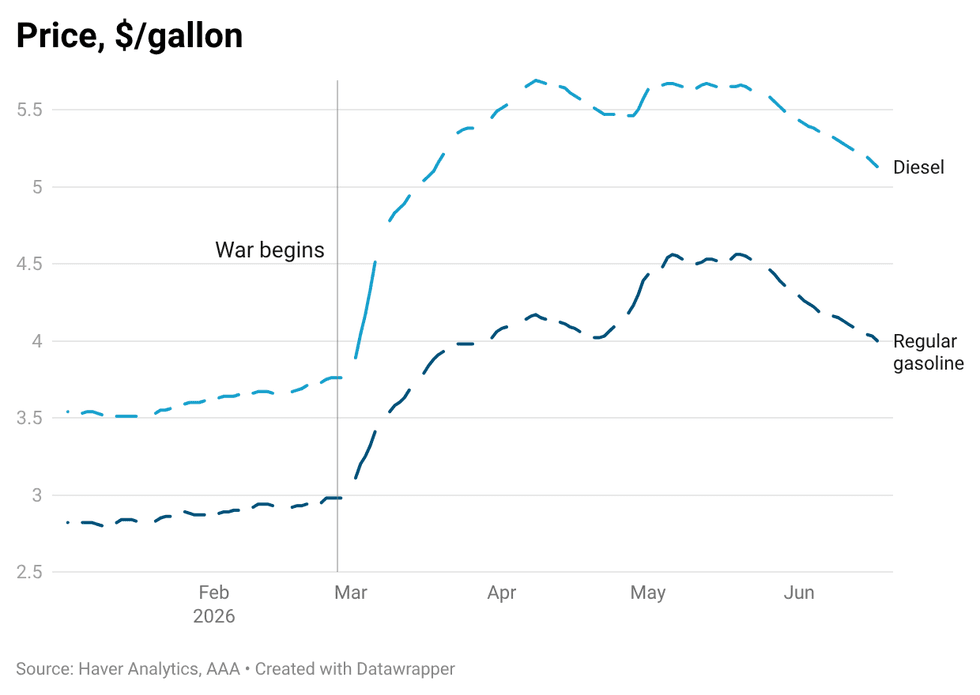
Will that happen this time? Gasoline and, to a lesser extent, diesel, have fallen considerably in price from their peak:

oil price

They are, however, still well above their prewar levels, and by more than you would expect given the commonly used rule of thumb:

$10 on price of crude = $0.25 on price of gasoline

Crude oil prices are $10-$15 a barrel higher than they were prewar, which would point to gasoline prices $0.25-$0.37 higher per gallon. Yet gasoline is currently almost $1 a gallon higher than it was before the war.

So if the “rockets and feathers” pattern continues to apply, gasoline prices will be elevated for months to come, thwarting Trumpist hopes of quick political relief from capitulating to Iran.

Prices beyond gasoline: As you can see in the chart above, the war on Iran sent the price of diesel fuel soaring by significantly more than the price of gasoline. Unlike gasoline, which is mainly purchased by consumers, diesel is mainly used by businesses, for trucking and industrial uses. So the surge in diesel prices led to a surge in business costs rather than a direct burden on consumers.

True, businesses do eventually pass higher costs on to consumers. The key word, however, is “eventually.” This means that there is probably substantial Iran war-induced inflation still in the pipeline.

Nor were soaring prices of diesel the only cost the war imposed on businesses. The Persian Gulf is normally a key supplier of many chemicals, whose prices soared when the Strait of Hormuz was closed. For example, the price of urea, a key fertilizer with industrial uses as well, temporarily rose by 75 percent when the Strait was closed. Again, some of the effect of these cost shocks still hasn’t hit consumer prices.

Moreover, the economy is delivering inflationary shocks independent of the war. Notably, the AI/datacenter boom has driven a rapid rise in electricity prices and huge increases in the prices of memory chips, which are used in almost all consumer electronics, from smartphones to laptops to game consoles. The AI boom has also pushed up interest rates on mortgages and consumer loans. Oh, and Trump’s cuts to Obamacare subsidies are causing many Americans’ health insurance costs to soar.

So while consumers are getting some relief at the gas pump, they’re facing persistent sticker shock on many other goods. It’s safe to predict that consumers won’t be in a celebratory mood on D-I [defeat by Iran] Day. Instead, they are likely to feel that any claims of victory are Pyrrhic at best.

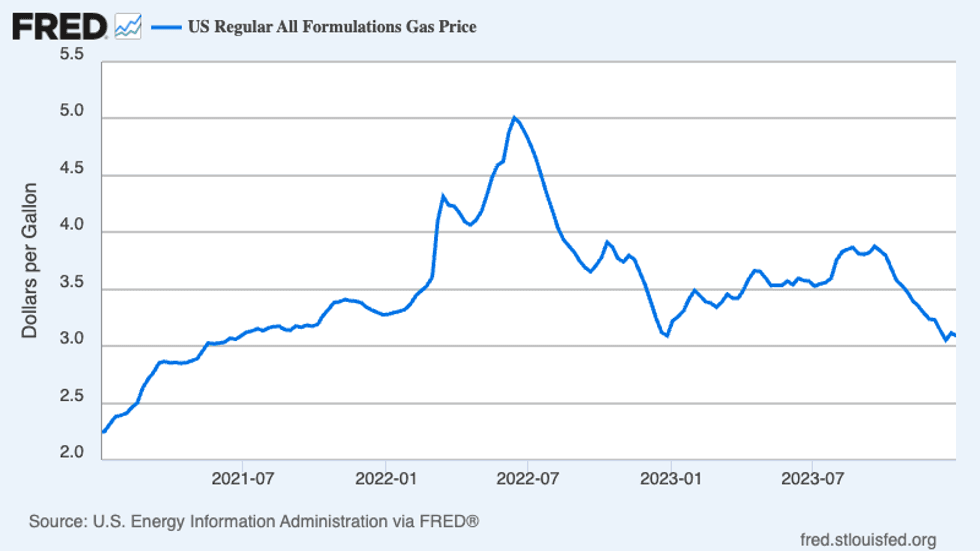
The cost of broken promises: We have just endured the second big gasoline price shock of the past five years. The previous shock, during the Biden years, briefly sent average prices of gasoline above $5 a gallon. Like the recent price spike, the 2022 run-up in gas prices was largely caused by a war — the war between Russia and Ukraine. That wasn’t a war that the U.S. president launched on a whim. Regardless, the price of gasoline fell rapidly after June 2022:

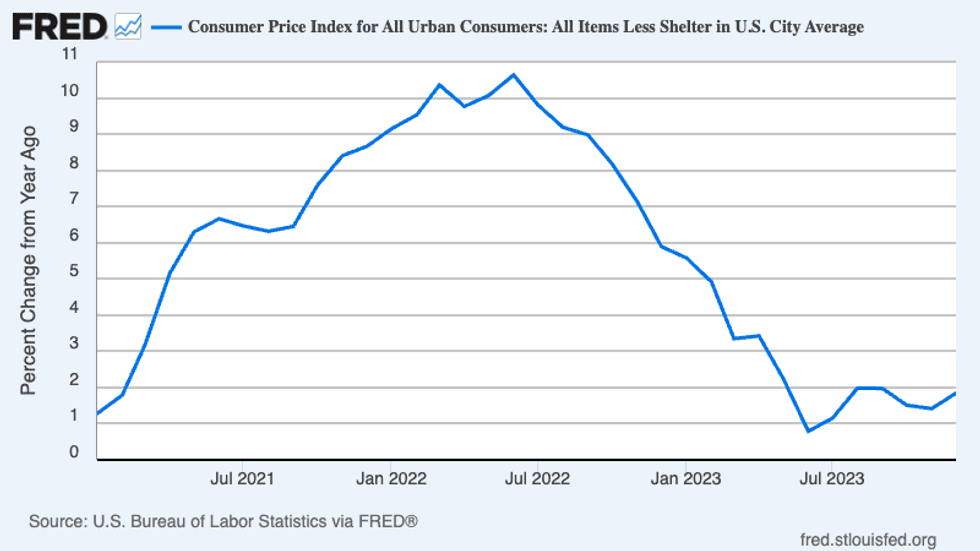
Inflation also fell rapidly, especially if you exclude the price of shelter, which as measured tends, for technical reasons, to lag far behind market prices:

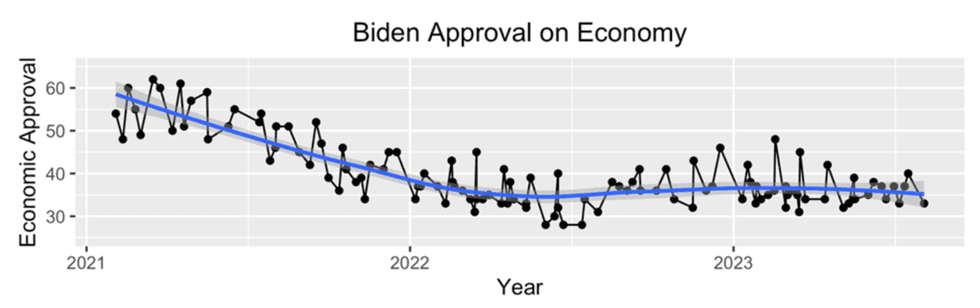
So what did cheaper gas and rapid disinflation without a recession do for perceptions about President Biden’s handling of the economy? Almost nothing. The Roper Center published an analysis of trends in Biden’s economic approval rating, and found hardly any improvement when gas prices and overall inflation plunged:

You may argue that this was unfair because Biden was punished for a global inflation shock that wasn’t his fault. Furthermore, his overall economic management was in fact very good. In fact, that’s what I have argued, and a majority of Americans now say that the economy was better under Biden than under Trump. However, that argument is beside the point for analyzing the effect of the Trump surrender. The point, instead, is that once a leader has lost the public’s economic trust, that trust doesn’t come back just because gasoline prices have receded.

I would add that it may be especially hard for the Trumpists to make the case that things have turned around when they were never willing to admit that anything was wrong in the first place, insisting even as prices soared that we were living in a “golden age.”

So will Trump’s surrender to Iran rescue him and his party from a blue wave in November? It’s very unlikely. I suggest they find themselves some lifejackets.

Paul Krugman is a Nobel Prize-winning economist and former professor at MIT and Princeton who now teaches at the City University of New York's Graduate Center. From 2000 to 2024, he wrote a column for The New York Times. Please consider subscribing to his Substack.

Reprinted with permission from Paul Krugman.

Trump's Tariffs Are Still Inflating Prices -- And Will Stop Fed From Cutting Rates

Trump's Tariffs Are Still Inflating Prices -- And Will Stop Fed From Cutting Rates

Donald Trump assured us that exporters would pay his tariffs; that it would effectively be free money to the United States. At times he even suggested a tariff dividend, where he would send us all checks of $1k to $2k with all the money that was pouring in from his tariffs.

Virtually all economists said this was nonsense. Based on extensive research, they argued that people in this country would pay the overwhelming majority of the tariffs, even if there is some question as to how much might be borne by importers and retailers, as opposed to consumers.

We quickly learned that the Trump story was wrong. Before Trump’s election, inflation had been headed down to the Fed’s 2.0 percent target. After Trump’s “Liberation Day” tariffs went into effect, inflation began rising, hitting 3.0 percent even before the Iran War. With the big war-related run-up in energy prices, inflation is now over four percent.

With everything else going on in the economy and the world, we shouldn’t lose sight of the impact of the Trump tariffs. We got new data on that yesterday, when the Bureau of Labor Statistics released May data on import prices. The data showed non-fuel import prices rose 0.8 percent in the month of May and were up 3.7 percent over the last year.

Just to be clear, these are the prices that are paid to exporters. They do not include the tariffs that are paid by importers. The tariffs are added on to these prices. If exporters were eating the tariffs, as Trump promised, import prices would fall.

To take a simple case, if Trump imposed a ten percent tariff on shoes, in the exporters eating the tariff story, the price of imported shoes would fall ten percent. That would leave businesses and consumers here unharmed and exporters getting ten percent less for the price of their shoes.

This is clearly not happening. Trump’s tariffs may not be responsible for import prices rising (although his war might be), but they clearly are not falling. As every academic study has shown, and U.S. consumers know, we are paying Trump’s tariffs.

The sharp rise in import prices will be another factor pushing inflation higher. The increase in import prices may not be fully passed on to consumers, but certainly much of it will.

To take the simple arithmetic here, imports of goods are roughly percent of GDP. If import prices rise 3.7 percent, that would add a bit less than 0.4 percentage points to inflation, and that is before the impact of any Trump tariffs. The full story will be more complicated, but this should give us some idea of what we’re looking at.

These new data come out just as the Federal Reserve Board is having its first meeting under its new Trump-appointed chair, Kevin Warsh. Trump demanded that Jerome Powell, the prior chair, lower interest rates. When he refused, Trump threatened to fire him and then prosecute him.

Trump clearly wants lower interest rates and has said that he expects Warsh to give him what he wants. With the recent data all showing inflation on an upward path (we got bad news on both the Consumer Price Index and the Producer Price Index last week), it would be very hard to envision any of the other 11 members of the Fed’s Open Market Committee (FOMC) that determines interest rates voting for a rate cut.

This leaves Warsh with the option of either being the first Fed chair ever to be in the minority on an FOMC vote or incurring Trump’s wrath on Truth Social. Being an opportunistic sycophant can sometimes get people in trouble.

Dean Baker is a senior economist at the Center for Economic and Policy Research and the author of the 2016 book Rigged: How Globalization and the Rules of the Modern Economy Were Structured to Make the Rich Richer. Please consider subscribing to his Substack.

Shop our Store

Headlines

Editor's Blog

Trending

World