Tag: health coverage
Nearly Half Of Working-Age American Adults Have No Decent Health Coverage

Nearly Half Of Working-Age American Adults Have No Decent Health Coverage

This past June, GoozNews forecast the uninsured rate would soar to 11 percent this year due to changes contained in the One Big Ugly Bill passed by the Republican-controlled Congress and signed into law by Donald Trump in July 2025. That would be a 37 percent increase from early 2025.

While official numbers won’t be released by the Census Bureau until next year, a new survey from the Commonwealth Fund confirms that back-of-the-envelope estimate. Not only did a poll of 9,360 adults conducted this past summer find this year’s uninsured rate rose over three percentage points from last year’s eight percent, but the share of working-age adults with inadequate coverage still stands at 35 percent, bring the total with no or inadequate coverage to 46 percent.

What constitutes “inadequate” coverage? It’s people who can’t afford their insurance premiums, deductibles and high out-of-pocket costs when accessing care. It’s people facing gaps in their coverage, which must be paid out-of-pocket. The survey found 31 percent of adults insured throughout the year are paying off medical bills or debt.

“Our survey shows that most Americans are struggling to get the health care they need, and things are getting worse,” said Dr. Joseph R. Betancourt, president of the Commonwealth Fund.

Americans have repeatedly told pollsters that health care affordability ranks as either their first or second most important issue this year. Despite this being an election year, not a single mainstream media outlet — print, broadcast or online — covered yesterday’s release of the Commonwealth Fund survey.

Cause and effect

It’s no mystery why both unaffordable coverage and the uninsured rate are rapidly rising. They are, respectively, cause and effect.

The Republican Congress refused to renew the expanded Obamacare subsidies for low-income workers that were passed during Covid. That non-act sent premiums on the exchanges soaring and forced millions of people without employer-based coverage to drop their individual and family plans.

The One Big Ugly Bill’s new work rules for Medicaid recipients and the requirement that state agencies conduct twice-a-year recertifications won’t go into effect until January. But expiration of the recertification waiver passed during the Covid pandemic has already forced 25 million people from the program, not because they weren’t still eligible, but because they failed or didn’t have the documents needed to fill out the necessary paperwork. After the new Medicaid rules go into effect in January, another four to five million poor people are expected to lose coverage.

The resulting massive increase in the uninsured rate has sent uncompensated care costs at the nation’s hospitals and physician practices soaring. That in turn has led to rapid price increases as providers look to the still insured to pick up those additional costs.

Insurers are glad to pass those costs along since it raises their profits. Whether they are selling their own plans or acting as third-party administrators for self-insured employers, insurers generally reap about five percent of top line revenue as profit. The larger the top line, the larger the bottom line.

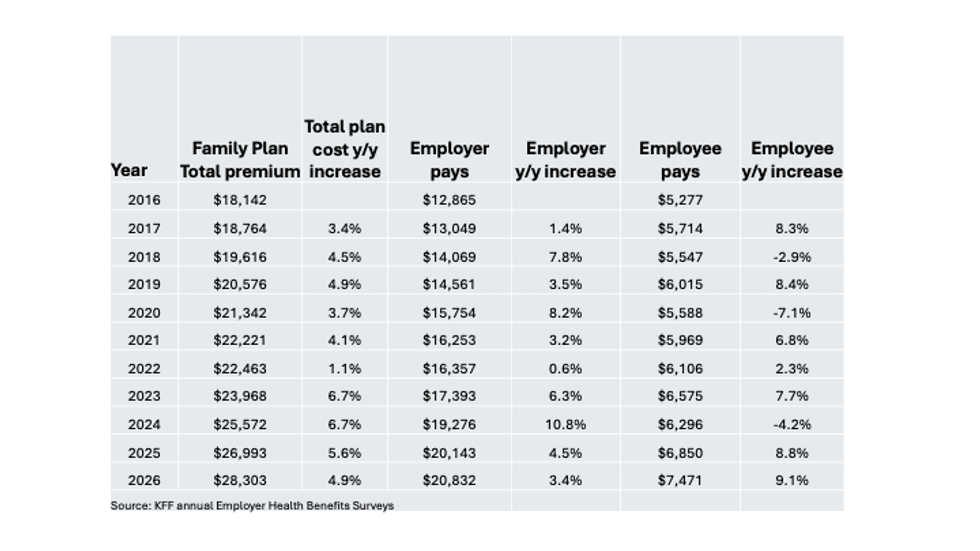
The annual KFF survey of employers, also released this week, confirmed those soaring top-line costs. It reveals how employers are responding this year by shifting more of the total cost onto their employees. The average cost of a family plan rose five percent to $28,303. But the average amount workers pay in premiums rose nine percent to $7,471 while the average cost for the employer share rose only 3.4 percent.

But to be fair, these numbers jump around a lot year over year (see the chart below). Over the past decade, rising health care costs have imposed a greater burden on employers. They saw their share of the average family plan rise 62 percent over the past decade compared to their workers’ share rising “just” 42 percent (or twice the rate of inflation on average).
But employers have an out that their employees don’t have. They can grab a larger share of total income (which they have), and they can limit workers’ wage increases (which they have).

As every health care economist will tell you, in the end, health care benefits are a form of wages. Workers wind up paying one way or the other. It is no mystery why health care costs have become many families’ most pressing economic concern.

Merrill Goozner, the former editor of Modern Healthcare, writes about health care and politics at GoozNews.substack.com, where this column first appeared. Please consider subscribing to support his work.

Reprinted with permission from GoozNews

Trump Aims To ’Terminate’ Obamacare In Midst Of Pandemic

Trump Aims To ’Terminate’ Obamacare In Midst Of Pandemic

Donald Trump on Wednesday said he still supports a Republican-led lawsuit before the Supreme Court that seeks to invalidate the Affordable Care Act, even amid the COVID-19 pandemic.

More than 1.2 million Americans have tested positive for the virus, and nearly 72,000 have died from it, according to a tally from the Washington Post.

Read NowShow less
5 Reasons The Clinton/Trump Debate May Be The Most Important Night Of Our Lifetimes

5 Reasons The Clinton/Trump Debate May Be The Most Important Night Of Our Lifetimes

When the John F. Kennedy and Richard Nixon sat down for what would be the first televised presidential debate in 1960, you could argue that the differences between America’s two major parties had never been slighter.

While African-Americans had been migrating from the party of Lincoln since the early days of the New Deal and Kennedy did seek Martin Luther King Jr.’s release from jail in Georgia during the campaign, the new president didn’t even mention civil rights in his inaugural address. Nixon was an avid Cold Warrior, but was attacked by the Democratic nominee for leaving us vulnerable to the Soviets with a “missile gap.” There was a general consensus in America, born of remarkable economic growth and the largest expansion of the middle class in human history.

So little differences mattered—a lot.

Some argue Nixon’s face cost him the debate. He was sweaty, sick, and disconcerting, having refused the makeup he was advised to wear.

Under the guidance of Roger Ailes—the TV producer now known as “the force behind many of the worst things of the last 50 years”—Nixon never debated again. But he did find ways to seem comfortable on television, thanks to plenty of face powder and less confrontational settings like town halls and Laugh-In. Ailes advised Nixon on his successful 1968 bid, coached Ronald Reagan how to decimate Walter Mondale in 1984, and then launched Fox News, the official channel of the Iraq War.

Fresh off his dismissal from Fox News after allegations of serial sexual harassment, Ailes is now reportedly coaching Donald Trump to face Hillary Clinton in a series of three debates, the first taking place at Hofstra University on Monday.

It will likely be the most highly viewed debate in the history of the world — and here’s why it could be the most consequential.

  1. The electorate feels remarkably unstable.
    Clinton’s lead in national polls is similar to the lead President Obama carried into the first debate of 2012. But Obama was outperforming those numbers in swing states and the electorate never really wavered much throughout the electoral cycle. There are more undecided voters this year and we have to add into this nebulous math the shifting variable of third-party candidates, Libertarian Gary Johnson and the Green Party’s Jill Stein, who continue to pull numbers that could be much larger than the eventual margin of victory for either Clinton or Trump. Both major party candidates have high negatives, with Trump seeing approval ratings that make him the most unpopular candidate of modern times. Even more vexing for prognosticators is Trump’s historic boost from the media, combined with his hollow shell of a campaign, which pales next to Clinton’s in terms of ad buys and organization. All of this ads up to a public that seems far more open to persuasion in recent elections and possibly uniquely open to the unique sort of persuasion that a huge television spectacle could provide.
  2. Trump’s only superpowers are being good at TV and lying.
    Trump’s mastery of television helped him overcome his failures as a developer, transforming him into a larger-than-life boss who was willing to embrace the racist undertones and overtones of birtherism. Even more unprecedented than his power to be “good on camera” is his willingness to lie without abandon while he maintains a reputation of “telling it like it is.” These are formidable superpowers in a forum where he can lash out and do serious damage in the first fifteen minutes of a debate, when most of these contests are decided. It’s true that Trump has never been in a one-on-one setting like this before, but he has clearly spent his entire life preparing to spend 90 minutes yelling at a woman.
  3. We have no idea how America will react to a woman candidate debating for the presidency.
    Clinton’s strengths are nearly the opposite of Trump’s. She’s devoted her life to public service, nurturing a depth of knowledge on issues while maintaining the cautious pose we demand of most trailblazers in American politics. How will America react to a woman who is overqualified for the job facing the most unqualified candidate imaginable? This will be a war of substance versus affect — and we all know which television favors. This debate is historic for both the mismatch of the candidates and the fact of a woman standing on stage making her case to be the president of the United States. No one has any idea of how the public will react to something it has never seen before.
  4. The differences between the two candidates are pronounced and profound.
    Donald Trump is promising to uninsure almost 20 million newly insured Americans and Hillary Clinton is promising to add 9 million more to the record number of Americans with heath coverage. And the differences only grow more stark from there. Trump wants to cut taxes for the rich, while raising taxes on many middle-class families. Clinton wants to raise taxes on the rich, while leaving them untouched for the rest of America. Trump wants to ban abortion and strip women of birth control access. Clinton wants to expand reproductive rights to the poorest Americans. Clinton wants to give undocumented immigrants a path to citizenship. Trump wants to round them up. Clinton wants to escalate the fight against climate change to avoid catastrophe. Trump wants to unleash carbon polluters to continue wrecking the climate and making the rest of us — and the planet — pay for it.
  5. The fate of the America and the world is on the line.
    Almost half of all voters in a new poll — 46 percent — think Donald Trump would detonate a nuclear bomb as president. And 22 percent of those people are Trump supporters, meaning they’re hoping for a nuclear war. Around a third of his supporters also see him creating a Muslim database, creating internment camps for undocumented immigrants, and defaulting on our debt. These are things they’re voting for, apparently. If Donald Trump gets into office, he will be a uniquely unprepared candidate with unprecedented political power and something like a mandate, built on a campaign that has elevated some of the vilest and most dangerous voices in America. Once in office, he’d face an economy overdue for a recession and a world vulnerable to acts of terror. Knowing he takes every wave of a pocket Constitution as a vicious personal attack, how will he react to mounting pressures and failures — especially knowing that his personal business interests, which he will still be personally entangled in, have over a half billion dollars in loans extended around the world? No one can predict his response, but it will likely be like nothing we’ve ever seen in America before.
Many Newly Insured Still Face Health Coverage Upheaval

Many Newly Insured Still Face Health Coverage Upheaval

By Tony Pugh, McClatchy Washington Bureau

WASHINGTON — As procrastinators rushed to buy health insurance Monday by the Affordable Care Act’s official enrollment deadline, new research estimates that about half of those with subsidized coverage obtained from federal or state marketplaces will lose it within a year because of changes in their incomes or other family circumstances, such as divorce, relocation or the births of children.

The same is true for about half of new Medicaid recipients, who are likely to lose program eligibility at some point over the next year for a variety of reasons, said Benjamin Sommers, an assistant professor of health policy and economics at the Harvard School of Public Health.

When people lose, drop or change health coverage for unforeseen reasons, it’s known as “churning.” It’s a common occurrence for consumers with individual coverage bought outside the workplace, as well as for those with Medicaid, the state-federal health program for poor people and those with disabilities.

Along with being a bookkeeping headache for insurers and Medicaid administrators, churning undermines the continuity of care between doctors and patients by causing patients to miss treatments and sometimes seek new caregivers.

It also has a financial impact, as coverage lapses may lead to costly emergency room visits when primary physicians could have provided treatment for far less.

In the 25 states that expanded eligibility for Medicaid under the Affordable Care Act, churning probably won’t leave people without coverage because there’s no gap between the income thresholds for Medicaid and subsidized marketplace coverage. Instead, millions will move between eligibility for both as their incomes are periodically updated and verified.

“It’s not exactly that they’ll lose coverage,” Sommers said in an interview. “It’s that they may have to change the coverage they have.”

But for people in states that so far have declined to expand Medicaid, “then they’re worse off,” he said. If they lose their eligibility for subsidized coverage when their incomes fall too low to qualify, “they will probably have no option for coverage,” Sommers said.

That’s because the income limits to qualify for Medicaid in non-expansion states are far below the levels at which subsidized marketplace insurance is available. That creates a “coverage gap” in which millions of people earn too much to qualify for Medicaid but not enough for federal subsidies to help them buy marketplace insurance.

“In other words, most adults who lose marketplace subsidies in non-expanding states will become uninsured,” Sommers and three other researchers wrote in their report on churning in the April edition of Health Affairs magazine.

Expansion states with lower poverty rates and higher per-capita incomes will see more churning because they have more adults with incomes near the eligibility line for Medicaid and subsidized coverage, Sommers said in the interview.

Half of Americans with individual health insurance churned in and out of coverage in 2010, according to recent congressional testimony by Medicaid Administrator Marilyn Tavenner. The reasons were myriad: Some couldn’t afford it, some switched to different plans and others may have dropped their coverage after obtaining job-based insurance.

The average Medicaid recipient loses coverage for 20 percent of the year — nearly 10.5 weeks — because of administrative violations, clerical errors, income changes or other factors that make him or her ineligible, according to researchers at George Washington University.

“The implication is that eligibility changes are likely to be a major challenge for every state as implementation of the ACA continues,” according to the Health Affairs article.

Photo via HealthCare.gov

Shop our Store

Headlines

Editor's Blog

Trending

World